Insights

Welcome! You are invited to join a webinar: Thriving in Your Golden Years. After registering, you will receive a confirmation email about joining the webinar.
Welcome! You are invited to join a webinar: Thriving in Your Golden Years. After registering, you will receive a confirmation email about joining the webinar.Tonight is Session 1 of the virtual series: **The Eric Bilger Team: Thriving in your Golden Years**.If retirement is within the next chapter for you (or your parents), structured education like this can be a great starting point.Registration: https://us02web.zoom.us/webinar/register/WN_ld3T1jM6R6SiVE88rrtY3g#/registrationSee thrivent.com/social for important disclosures.#Retirement #Webinar #FinancialEducation
Insight image
If I could only pick one behavior that consistently helps people build momentum: **automation**.Automate the good decisions (saving, investing, paying down debt) so you don’t have to rely on motivation.See thrivent.com/social for important disclosures.#PersonalFinance #Habits #Consistency
Insight image
One of the most underrated tax-season habits: keeping a running list of life changes *as they happen* (new job, bonus, move, marriage, new account, etc.).That short list makes year-end planning far easier than trying to reconstruct everything in March/April.See thrivent.com/social for important disclosures.#TaxPlanning #Organization #FinancialHabits
Insight image
REMINDER: If you’re in the Clear Lake / Houston Bay Area:David Wegenke and I are hosting a Market Update Workshop at Gloria Dei Lutheran Church on **Thursday, April 9 at 6:00 PM** (doors open **5:30 PM**). Complimentary dinner; guests are welcome.RSVP details: https://connect.thrivent.com/houston-bay-area/events?event=103241See thrivent.com/social for important disclosures.#HoustonBayArea #MarketUpdate #CommunityEvent
Insight image
A quick reminder when headlines feel intense: the market doesn’t send alerts when it’s ‘safe’ to re-enter.Most long-term progress comes from having a plan, sticking to it, and adjusting only when your goals change—not when the news changes.See thrivent.com/social for important disclosures.#Markets #LongTermInvesting #BehavioralFinance
Insight image
If retirement is on your radar, here’s a quick 3-question check-in that often reveals the next best step:1) What are my income sources—and when does each one start?2) What expenses are fixed vs. flexible?3) What’s my plan for ‘surprises’ (health, inflation, market swings)?Even getting these written down can reduce a lot of stress.See thrivent.com/social for important disclosures.#Retirement #Planning #FinancialClarity
Insight image
Sunday question I like to revisit:“What do I want my money to DO for my life?”When the purpose is clear, the ‘how’ gets easier—especially when the news cycle gets loud.See thrivent.com/social for important disclosures.#Purpose #Values #FinancialWellbeing
Insight image
Starting today, I’m going to post here every day through the end of April—short, practical financial education for real life in the Houston Bay Area.No hype. No jargon. Just frameworks, checklists, and local event reminders when we have them.If there’s a topic you’d like me to cover (retirement timing, Social Security, market volatility, Medicare, rollovers), drop it in the comments.See thrivent.com/social for important disclosures.#Houston #FinancialPlanning #RetirementPlanning
What Does a Retirement Readiness Review Actually Look Like?Most people avoid scheduling a financial consultation because they don't know what to expect.Here's exactly what happens in a Retirement Readiness Review with our team — no fluff, no sales pressure.The first 10 minutes — We listen.Where are you in your timeline? What's keeping you up at night? What does retirement actually look like to you? We don't start with spreadsheets. We start with your situation.The next 15 minutes — We assess.We look at your income sources, your savings, your projected expenses, and any major decisions on the horizon — Social Security timing, 401(k) rollover, pension elections, healthcare coverage.The final 5 minutes — We tell you where you stand.Honest, direct feedback. Are you on track? What gaps exist? What decisions are most urgent? You leave with clarity — not a folder full of brochures.The whole thing takes 30 minutes. It's complimentary. And it's available to anyone in the Clear Lake, Friendswood, League City, or Pearland area who is within 10 years of retirement.We've been doing this in southeast Houston for over 35 years. We're not going to sell you something you don't need.We're going to tell you the truth about where you stand.See thrivent.com/social for important disclosures.RetirementPlanning #HoustonBayArea
3 Questions to Ask Your Financial Advisor Before You RetireIf they can't answer all three clearly, keep looking.After working with hundreds of families across the Houston Bay Area, I've noticed a pattern: the people who feel most confident going into retirement are the ones who asked hard questions early.Here are the three I'd start with:1. "What is my sustainable withdrawal rate?"Not a generic answer. Your number — based on your portfolio, your timeline, your Social Security income, and your spending. If they give you a generic "4% rule" without context, push harder.2. "How will you help me minimize taxes in retirement?"Distribution strategy matters as much as accumulation strategy. The order you pull from taxable, tax-deferred, and Roth accounts can mean tens of thousands of dollars over a 20-year retirement.3. "What's your plan if the market drops 30% in my first year of retirement?"Sequence of returns risk is one of the most underappreciated threats to retirement security. A good advisor has a specific answer to this — not just reassurance.If your current advisor answers all three well, great. You're in good hands.If not — or if you don't have an advisor yet — I'd love to be a resource.See thrivent.com/social for important disclosures.
The Difference Between Having Money and Having a Retirement PlanI've met people with $1.2M saved who had no idea if they could actually retire.And I've met people with $600,000 who had complete clarity.The difference wasn't the balance. It was the plan.Having money is a starting point. A retirement plan answers the questions that actually keep people up at night:— Can I maintain my lifestyle without running out of money?— What do I do with my 401(k) when I leave my job?— How do I handle healthcare before Medicare?— What order should I pull from my accounts to minimize taxes?— When should my spouse and I claim Social Security?— What happens to my family if something happens to me?A number in an account doesn't answer any of those questions.A plan does.The families we work with across Clear Lake, Friendswood, League City, and Pearland aren't just looking for someone to manage their investments. They're looking for someone to help them connect the dots — so they can retire with confidence, not just hope.If you have the savings but not the plan, that's exactly the conversation I'd love to have.See thrivent.com/social for important disclosures.#RetirementPlanning #SocialSecurity #HoustonBayArea
Thrivent Social Media Privacy Policy, Guidelines, Disclosures & Disclaimers
Thrivent Social Media Privacy Policy, Guidelines, Disclosures & DisclaimersSocial Security Timing — Why Waiting Isn't Always the Right AnswerEveryone tells you to wait until 70 to claim Social Security.Here's when that advice is wrong.Waiting until 70 maximizes your monthly benefit — that part is true. But it's not the right move for everyone. Here's why:1. Your break-even age mattersThe break-even point for waiting from 62 to 70 is typically around age 80–82. If your health history or family longevity suggests you may not reach that age, claiming earlier often makes more financial sense.2. Sequence of withdrawalsIf waiting until 70 means drawing down your portfolio aggressively in your 60s to cover living expenses, you may be doing more damage than the increased benefit is worth.3. Spousal strategyFor married couples, the optimal strategy is rarely as simple as 'both wait.' In many cases, one spouse claims early and the other waits — and the math can be surprisingly different from what you'd expect.4. You actually have to live to collectA higher benefit doesn't help your household if you don't live to collect it. The goal is optimizing total lifetime income, not maximizing the monthly check.There's no universal right answer on Social Security. The right answer depends on your health, your spouse, your income sources, and your portfolio.We run personalized Social Security analyses for every client we work with — it's one of the most impactful decisions in the retirement planning process.📅 Want to know your optimal claiming strategy? Schedule a complimentary consultation — link in bio.See thrivent.com/social for important disclosures.Thrivent financial advisors and professionals have general knowledge of the Social Security tenets. For complete details on your situation, contact the Social Security Administration.
What Happens to Your NASA Pension If You Retire Early?Most aerospace and NASA employees don't ask this question until it's too late.If you're a federal employee or contractor in the Clear Lake area thinking about retiring before your full retirement age, there are a few things you need to understand about your pension:1. FERS supplement vs. Social SecurityIf you retire under FERS before age 62, you may be eligible for a Social Security supplement — but it stops the moment you hit 62, regardless of whether you claim SS. That gap matters.2. The earnings testIf you take the FERS supplement and continue to work, your supplement can be reduced based on earnings. Many people don't plan for this.3. FEHB in retirementYou can keep your federal health benefits in retirement — but only if you've been enrolled for the 5 years immediately before you retire. Timing matters more than most people realize.4. The survivor benefit decisionAt retirement, you'll make a permanent decision about survivor benefits for your spouse. Get this wrong and it can't be undone.These aren't scare tactics. They're decisions that deserve a second set of eyes before you sign anything.If you're a NASA or federal employee in the Houston Bay Area thinking through your retirement timeline, I'm happy to walk through your specific situation.📅 Schedule a complimentary consultation — link in bio.See thrivent.com/social for important disclosures.Thrivent financial advisors and professionals have general knowledge of the Social Security tenets. For complete details on your situation, contact the Social Security Administration.#RetirementPlanning #NASAPension #HoustonBayArea
In the years advising families across Clear Lake, League City, Friendswood, and the Greater Houston area, this one mistake shows up more than any other.People confuse having money with having a plan.We've sat across from couples with $800,000 saved who had no idea:— When to claim Social Security— How to bridge healthcare before Medicare at 65— What order to pull from their accounts to minimize taxes— Whether their savings would actually last 25–30 yearsThey had done everything right — saved consistently, maxed their 401(k), stayed the course through market downturns.But they had never built a retirement income plan. Just a retirement savings account.Those are two very different things.The good news: it's never too late to build one. And the earlier you do, the more options you have.If you're within 10 years of retirement and haven't mapped out your income plan yet, that's the conversation to start.📅 Schedule a complimentary Retirement Readiness Review — no obligation, no pressure, just clarity. Link in bio.See thrivent.com/social for important disclosures.#RetirementPlanning #HoustonBayArea #FinancialPlanning
Are your retirement savings on track?
Are your retirement savings on track?Want to help boost your 2025 tax savings? Let's connect to explore how you can balance your retirement goals with your day-to-day.
How to know if you're saving enough for retirement
How to know if you're saving enough for retirementRoadblocks happen, but they don't have to stop your progress. Discover how to stay on track with your retirement goals. 👇
Insight image
From education-specific accounts to general savings, different vehicles offer different rules, flexibility and potential tax advantages. The right mix depends on your timeline and goals. If you’re starting to save for college, take a look at this helpful overview of college savings plan options: https://bit.ly/3ZDyXPn
Insight image
Interest rates are shifting. Understanding the purpose and timeline of your cash can help you decide whether and how to invest it for optimal returns. Ask yourself two questions. ⬇️See thrivent.com/social for important disclosures.
The cost of cash: Where to invest when interest rates shift
The cost of cash: Where to invest when interest rates shiftWhether you’re saving for something big, looking to generate a steady income, or seeking flexible access to your cash, there are smart ways to keep your money productive and there for you when you need it—regardless of shifting interest rates.Explore your options below and let’s connect to keep your goals on track as interest rates change.
Insight image
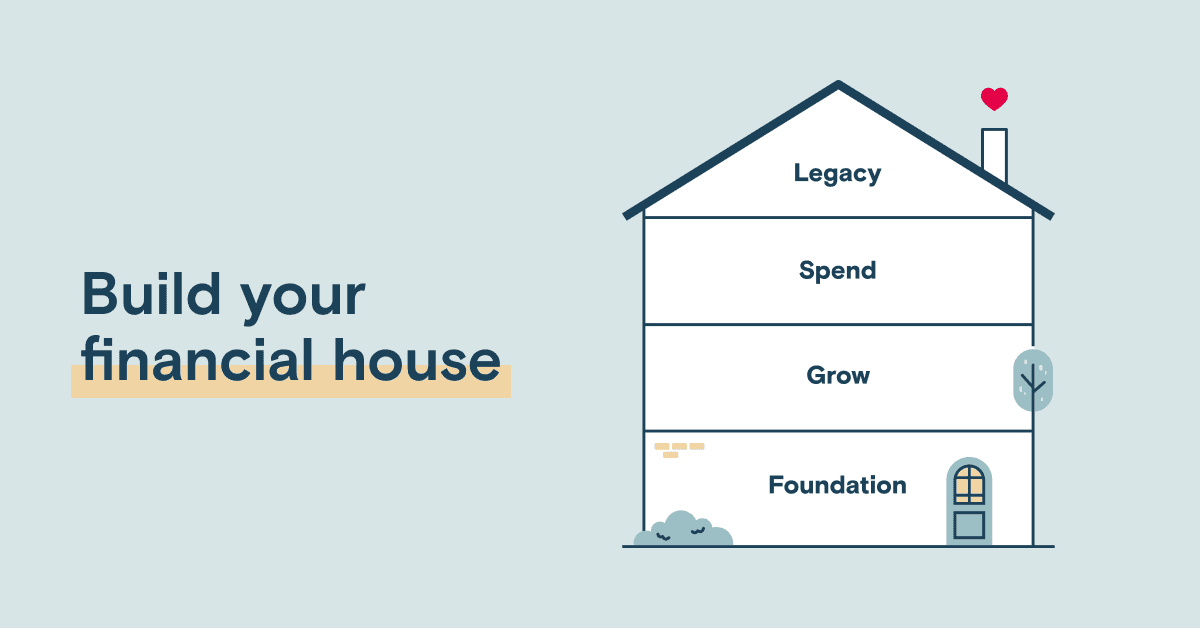
🏡 Your financial house should be built to last—and you can make it stronger with the right help.Whether you’re working to lay a solid foundation, grow your money or shape your legacy, financial planning can help you:✅ Prepare for the unexpected✅ Save and invest for major milestones✅ Adapt as your goals evolveTogether, we can create a financial plan with clarity and confidence, the same way a house is constructed. Reach out to learn more.See thrivent.com/social for important disclosures.