Insights
Financial wellness deserves a bigger place in the conversation around employee well-being.
A recent survey of more than 1,100 first responders found that financial stress was among the most commonly reported concerns, with over 60% identifying it as a top stressor and more than half expressing interest in financial education resources.
Financial stress can affect many areas of life, including focus, confidence, overall well-being, and the ability to prepare for future goals. While organizations often prioritize physical and mental wellness initiatives, financial education can be another valuable component of a comprehensive wellness strategy.
Building financial knowledge isn't about predicting markets or finding quick solutions. It's about understanding foundational concepts such as:
• Budgeting and cash flow management
• Emergency savings preparedness
• Debt management strategies
• Retirement planning basics
• Long-term financial goal setting
When individuals feel more informed about their finances, they may be better equipped to make thoughtful decisions that align with their personal goals and circumstances.
Financial wellness is not just a financial topic. It's a wellness topic.
See thrivent.com/social for important disclosures.
#FinancialWellness #FinancialLiteracy #RetirementPlanning #EmployeeWellbeing #FinancialEducation #FirstResponders #PersonalFinance

🚓🚒🚑 First Responders: Is Your Financial Plan Aligned With Your Goals?
As first responders, you're trained to prepare for the unexpected. The same mindset can be valuable when it comes to your financial life.
One of the most overlooked aspects of financial planning is making sure your accounts, investments, and savings strategies are aligned with your short-term needs, retirement objectives, and legacy goals.
Many people accumulate accounts over time—a workplace retirement plan, deferred compensation plan, IRA, brokerage account, savings account, pension benefits, and insurance policies. But if these accounts aren't working together toward a common objective, opportunities can be missed.
A well-coordinated strategy can help:
✅ Support tax planning by considering how different account types may be taxed today and in retirement.
✅ Strengthen retirement funding by aligning contributions and investment strategies with your retirement timeline and income needs.
✅ Increase flexibility by maintaining access to assets for both planned and unexpected life events.
✅ Create optionality so you have choices regarding when to retire, how to generate income, and how to adapt to changing circumstances.
✅ Support legacy planning by ensuring beneficiary designations and account structures reflect your wishes for family members and loved ones.
For first responders, retirement planning can be especially complex due to factors such as pensions, DROP programs, deferred compensation plans, overtime earnings, shift differentials, and unique retirement timelines. That makes periodic reviews even more important.
Taking the time to evaluate whether each account has a purpose—and whether that purpose aligns with your overall goals—can help create greater confidence in the road ahead.
The question isn't simply, "How much have I saved?"
It's, "Is every dollar working toward the future I want to create?"
#FirstResponders #FinancialPlanning #RetirementPlanning #TaxPlanning #WealthManagement #LegacyPlanning #FinancialWellness #PoliceOfficer #Firefighter #EMS #PublicSafety #RetirementReadiness
See thrivent.com/social for important disclosures.
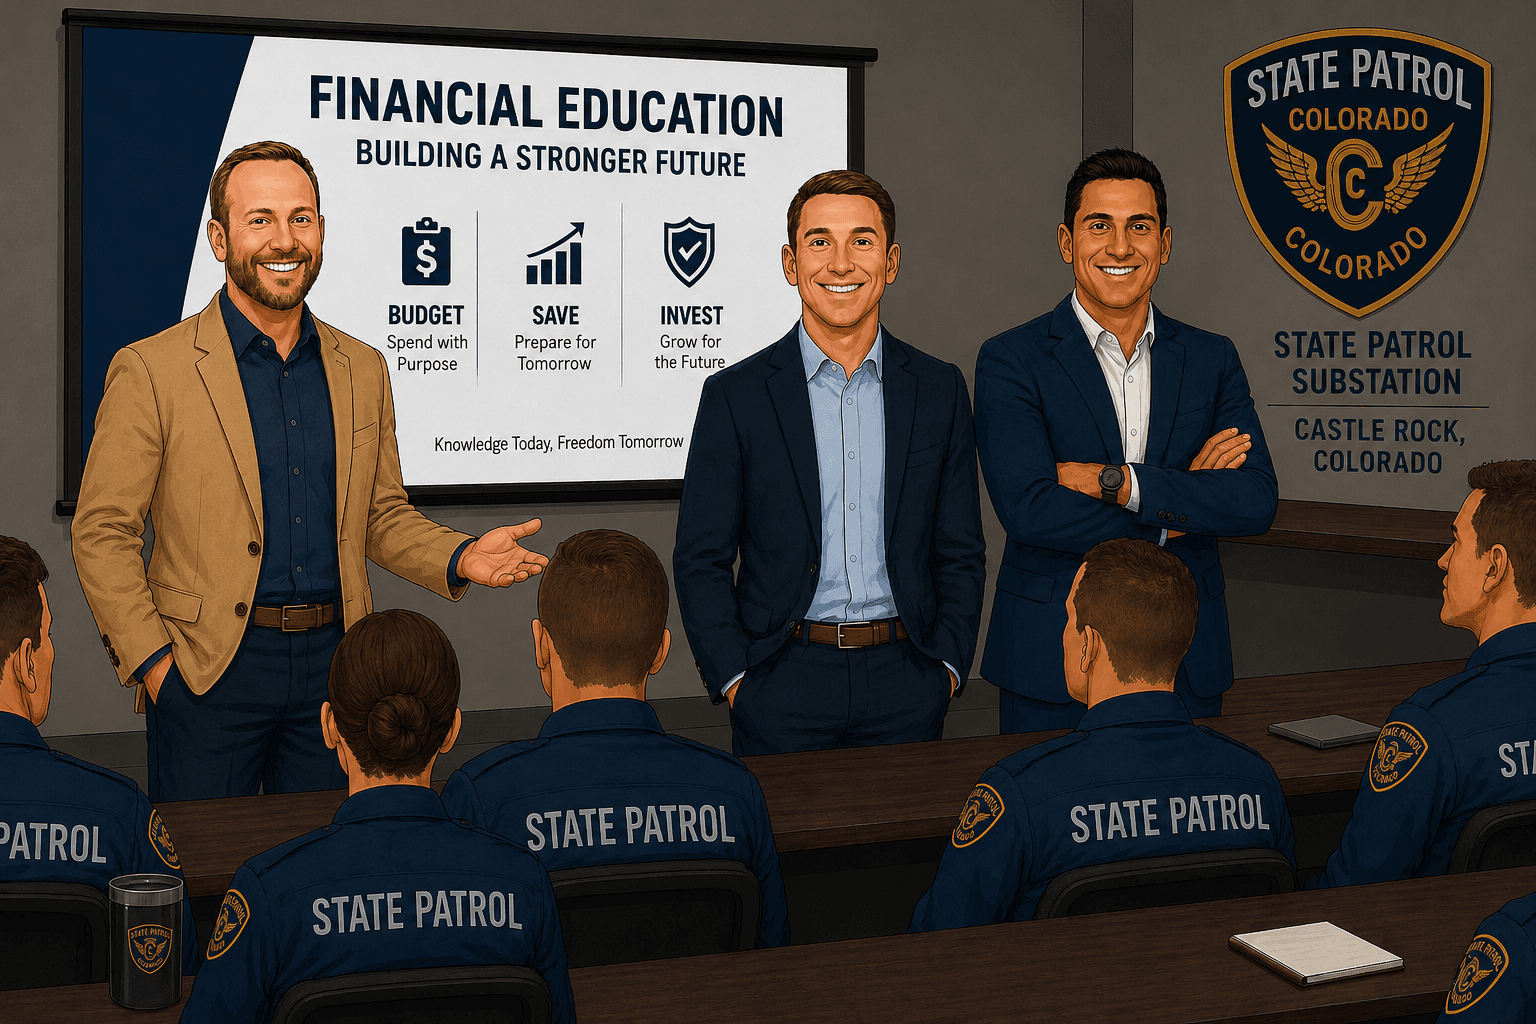
Grateful for the opportunity to join the Colorado State Patrol at their Castle Rock, CO substation last week alongside Nathan Hardy and Paul Osckel, MBA to facilitate another financial wellness workshop.
It was great to connect with such an engaged group of professionals and have meaningful conversations around financial planning and preparedness.
Supporting those who serve our communities every day is a responsibility we don't take lightly. When agencies invest in the financial well-being of their officers, the positive effects extend well beyond the badge—benefiting their families, strengthening their futures, and enhancing the communities they protect.
Thank you to the Colorado State Patrol for the warm welcome and for making financial wellness a priority for your team.
See thrivent.com/social for important disclosures.
Many first responders understand that financial planning is important.
They spend their careers preparing for the unexpected, making critical decisions under pressure, and protecting others. Yet when it comes to their own financial future, I've noticed something interesting:
When it's time to make financial decisions, create a plan, or make short-term sacrifices for long-term goals, the conversation often goes quiet.
Why is that?
Is it lack of time? Information overload? Uncertainty about where to start? Concern about making the wrong decision? Or is it simply easier to focus on everyone else's needs before your own?
Building a financial strategy isn't always about knowing exactly what to do. Sometimes it's about taking the first step and committing to a process.
I'm curious to hear from first responders and those who work closely with them:
What do you think is the biggest reason people hesitate to take action on financial decisions, even when they know planning is important?
#FirstResponders #FinancialPlanning #PersonalFinance #FinancialWellbeing #RetirementPlanning #FinancialConfidence
See thrivent.com/social for important disclosure information.
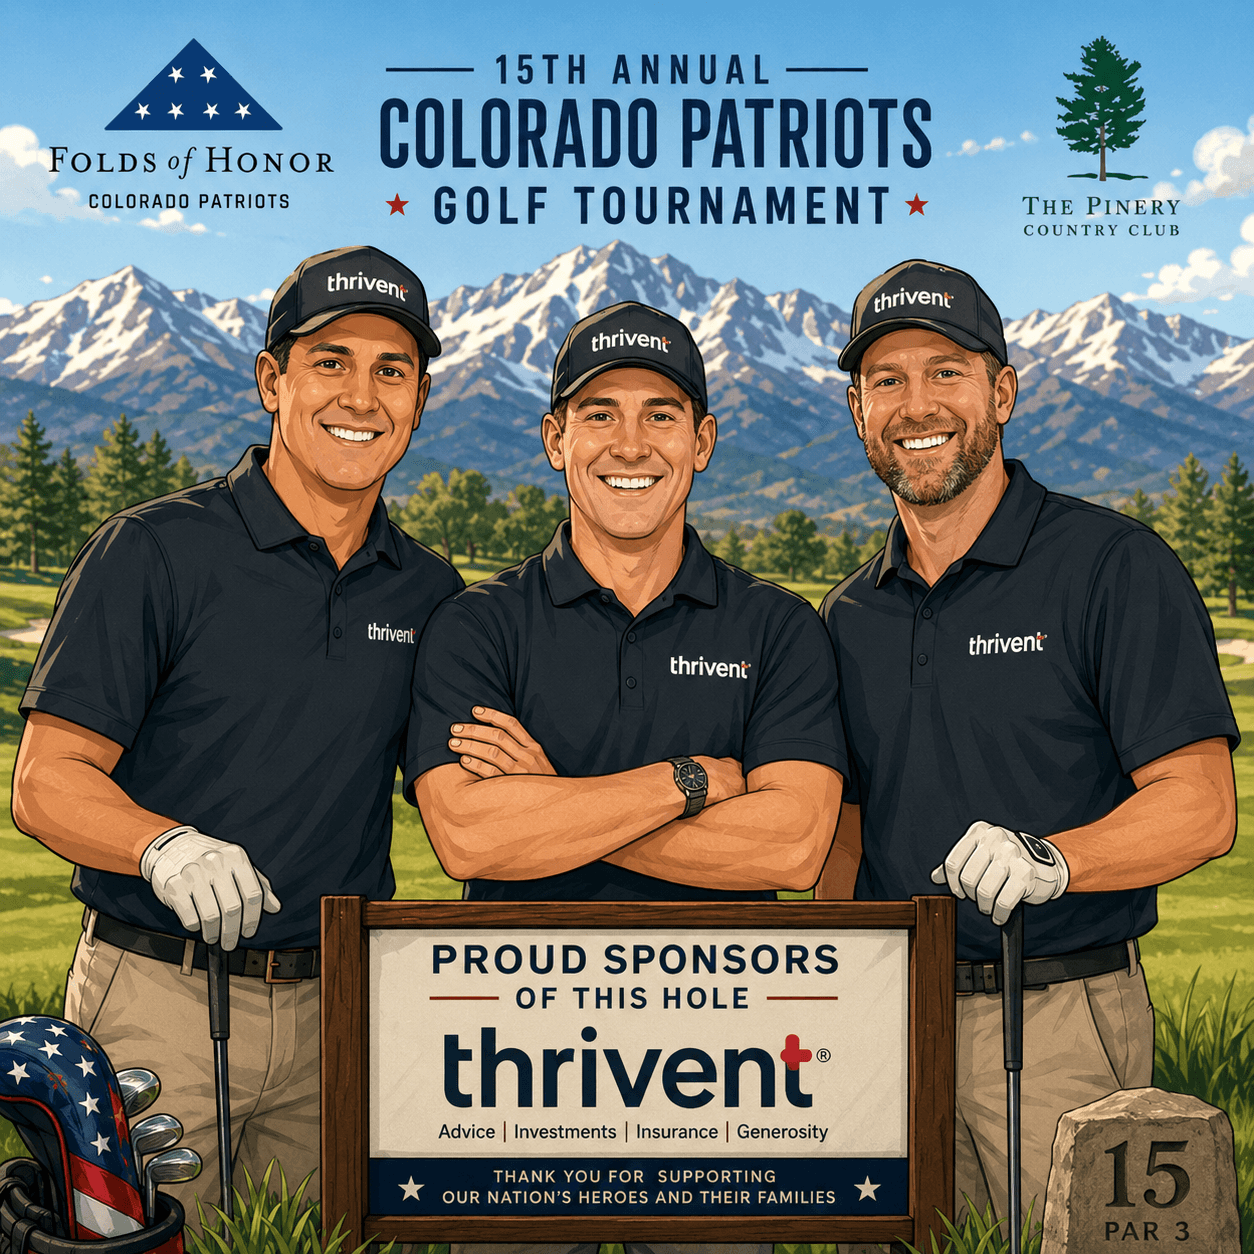
This week, Nathan, Paul, and I had the opportunity to sponsor a hole on a beautiful course with an even better mission behind it—supporting families of our nation’s heroes through Folds of Honor Colorado Patriots.
It’s always special to be surrounded by great people, strong community, and a shared purpose. Events like this remind me why I love what I do—serving others both professionally and personally.
Grateful to be part of a firm like Thrivent that encourages giving back and making an impact where it matters most.
To the organizers, participants, and everyone who made the day possible—thank you for an unforgettable event.
#FoldsOfHonor #ColoradoPatriots #Thrivent #GiveBack #Gratitude #GolfTournament #Community #FirstResponders #Veterans #ParkerCO
See thrivent.com/social for important disclosures.
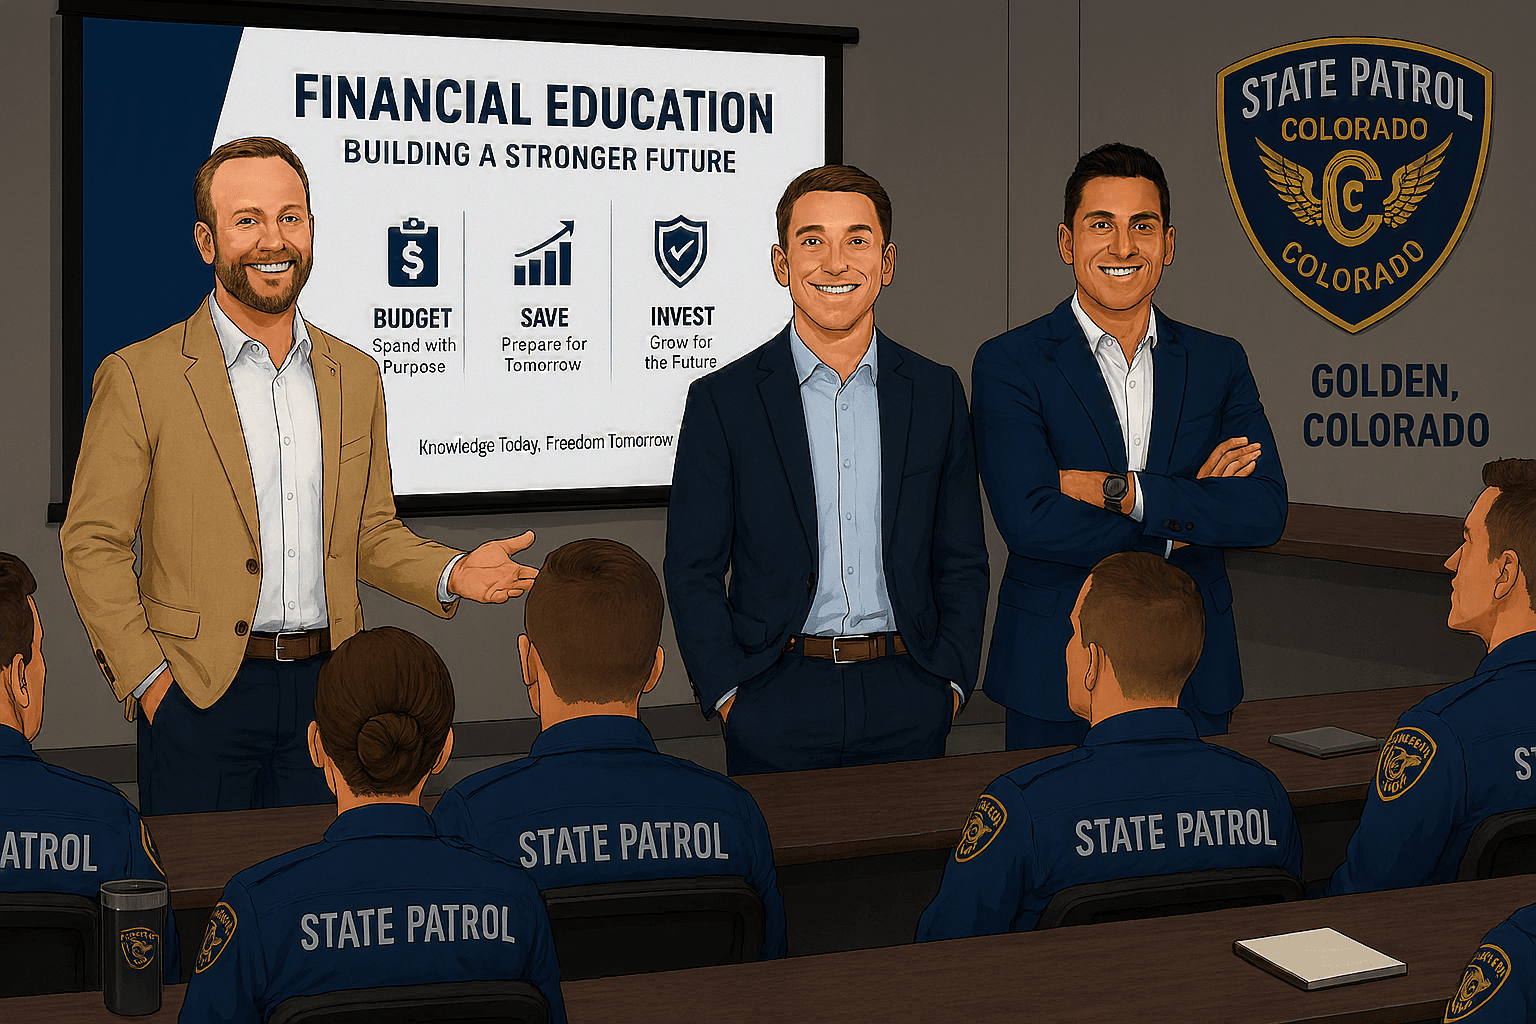
Grateful for the opportunity to spend time with the Colorado State Patrol in Golden, CO this week alongside Nathan Hardy and Paul Osckel, MBA to lead another financial wellness workshop.
We truly appreciated the conversation, engagement, and the chance to support such a dedicated group of professionals.
When law enforcement leaders prioritize the financial well-being of their officers, the impact extends beyond the workplace—supporting not only the officers themselves, but also their families and the communities they serve.
Thank you again for having us out.
See thrivent.com/social for important disclosures.

Most first responders will retire at 55 with a pension they never fully understood — and a financial plan they never started.
That's not a personal failure. It's a system failure.
The financial services industry has spent decades building products and advice for W-2 employees who work 9-to-5, max their 401(k), and retire at 65. First responders don't fit that model — and almost no advisor is built to serve them differently.
───────────────────────
THE PAIN POINTS NOBODY TALKS ABOUT
───────────────────────
The pension illusion.
Most first responders assume their pension is enough. The reality: DROP program decisions, survivor benefit elections, and lump sum vs. annuity choices are often irrevocable — and made without professional guidance. One wrong election can cost hundreds of thousands of dollars over a retirement that could last 30+ years.
The overtime trap.
Overtime routinely makes up 20–40% of a first responder's actual income — but it's rarely factored into savings rates, mortgage decisions, or retirement projections. When it ends, the lifestyle math breaks without warning.
The compressed earning window.
A career that ends at 52 or 55 leaves a decade-long gap before Social Security and Medicare eligibility. That gap has a real cost — in healthcare, in sequence-of-returns risk, and in withdrawing from retirement accounts too early.
The tax time bomb.
Pension income, deferred compensation, and Social Security can stack in retirement to create an unexpectedly high tax burden.
The identity cliff.
Research consistently shows that first responders who retire without a structured second chapter — financially or purposefully — face dramatically higher rates of depression, isolation, and financial instability. The plan has to go beyond the badge.
───────────────────────
WHAT ADVISORS BUILT FOR THIS COMMUNITY DO DIFFERENTLY
───────────────────────
✓ Pension analysis done years before retirement — not months
✓ Income replacement strategies that account for overtime and shift differentials, not just base salary
✓ Tax planning built around the compressed earning window and early retirement gap
✓ Estate and beneficiary planning that protects pension rights through life transitions
✓ A retirement vision that defines purpose and structure — not just a number
───────────────────────
First responders spend an entire career protecting people at their most vulnerable moments.
The financial planning industry has largely returned the favor with generic advice, ill-fitted products, and advisors who don't know what a DROP program is.
This community deserves better. Understanding your plan, protecting your income, and building a life after the job isn't a luxury — it's the mission that comes after the mission.
See thrivent.com/social for important disclosure information.
#FirstResponders #LawEnforcement #Firefighters #EMS #PensionPlanning #RetirementPlanning #FinancialWellness #FirstResponderWellness #PublicSafety
First responders are trained to operate one call at a time.
You assess the situation.
You respond with a plan.
You execute under pressure.
But when it comes to finances and retirement planning… many carry that same mindset — handling things as they come, rather than building a long-term strategy.
See thrivent.com/social for important disclosure information.
The challenge is that, unlike a call, time is always moving.
And the cost of waiting can be significant:
• Fewer years for compounding to work
• Missed opportunities for tax-efficient strategies
• Less flexibility when it comes to retirement decisions
The same operational planning skills used on the job — preparation, discipline, and thinking ahead — can be just as valuable when applied to your financial life.
This isn’t about having all the answers today.
It’s about starting the process earlier, so you have more options later.
If you’re in a role where you’re used to protecting others, it’s worth taking time to build a plan that protects your future as well.
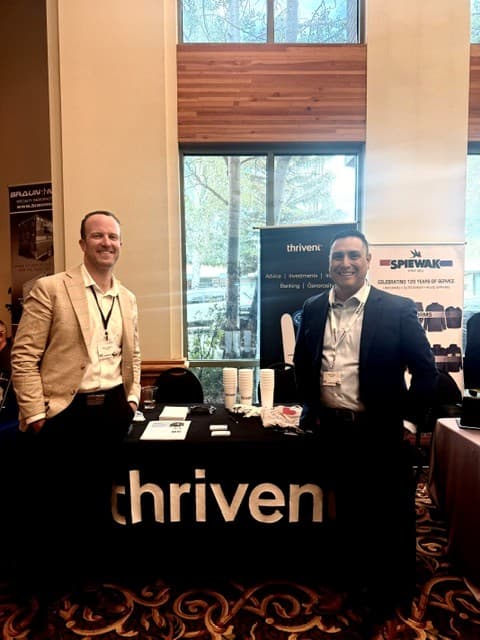
I had a great experience connecting with law enforcement leaders from across Colorado at the CACP Conference in Estes Park. It was especially meaningful to be able to hear more about the impactful work happening across our state.
One of the most valuable parts of the conference was engaging in conversations around financial awareness within the law enforcement community. These discussions continue to reinforce a belief I hold strongly: financial education plays an important role in overall wellness.
Paul and I—both having previously served in law enforcement—are passionate about staying connected to the profession in a different capacity. There is a meaningful opportunity to support officers and their families by helping increase understanding and confidence around financial topics.
We truly appreciated the many thoughtful conversations and perspectives shared throughout the event. It’s clear there is growing interest in financial education, and continued dialogue in this area can play a positive role in broader wellness efforts.
See thrivent.com/social for important disclosure information.
#CACP #Leadership #PublicSafety #ColoradoLawEnforcement
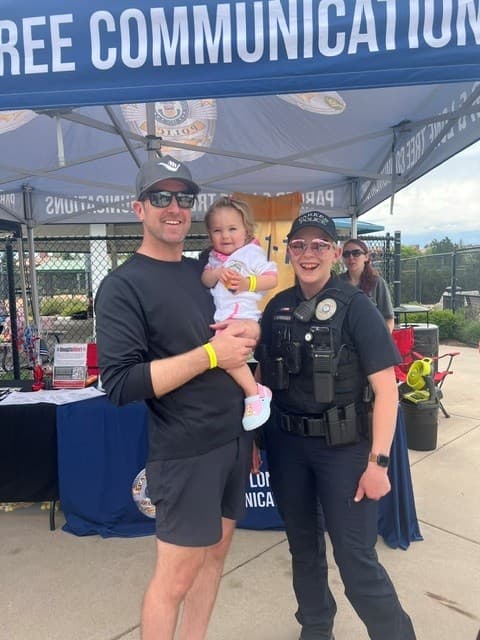
We had an awesome time kicking off summer at the H2O’Brien Pool event with the Parker Police Department!
It was such a great afternoon filled with family fun, interactive activities, and the chance to connect with so many incredible people in our community. From meeting officers to hands-on demos—and of course popsicles to beat the heat—it was an event done right.
The highlight for me? Seeing my daughter light up when she received her honorary Parker PD badge sticker. Moments like that mean everything.
I truly enjoy getting out into the community with my family, and events like this are a great reminder of how fortunate we are to have such dedicated local first responders. Huge thank you to Parker PD and South Metro Fire Rescue for everything you do to keep our community safe and engaged.
Here’s to a great start to summer!
#Community #Family #Grateful #FirstResponders #ParkerCO #SummerFun
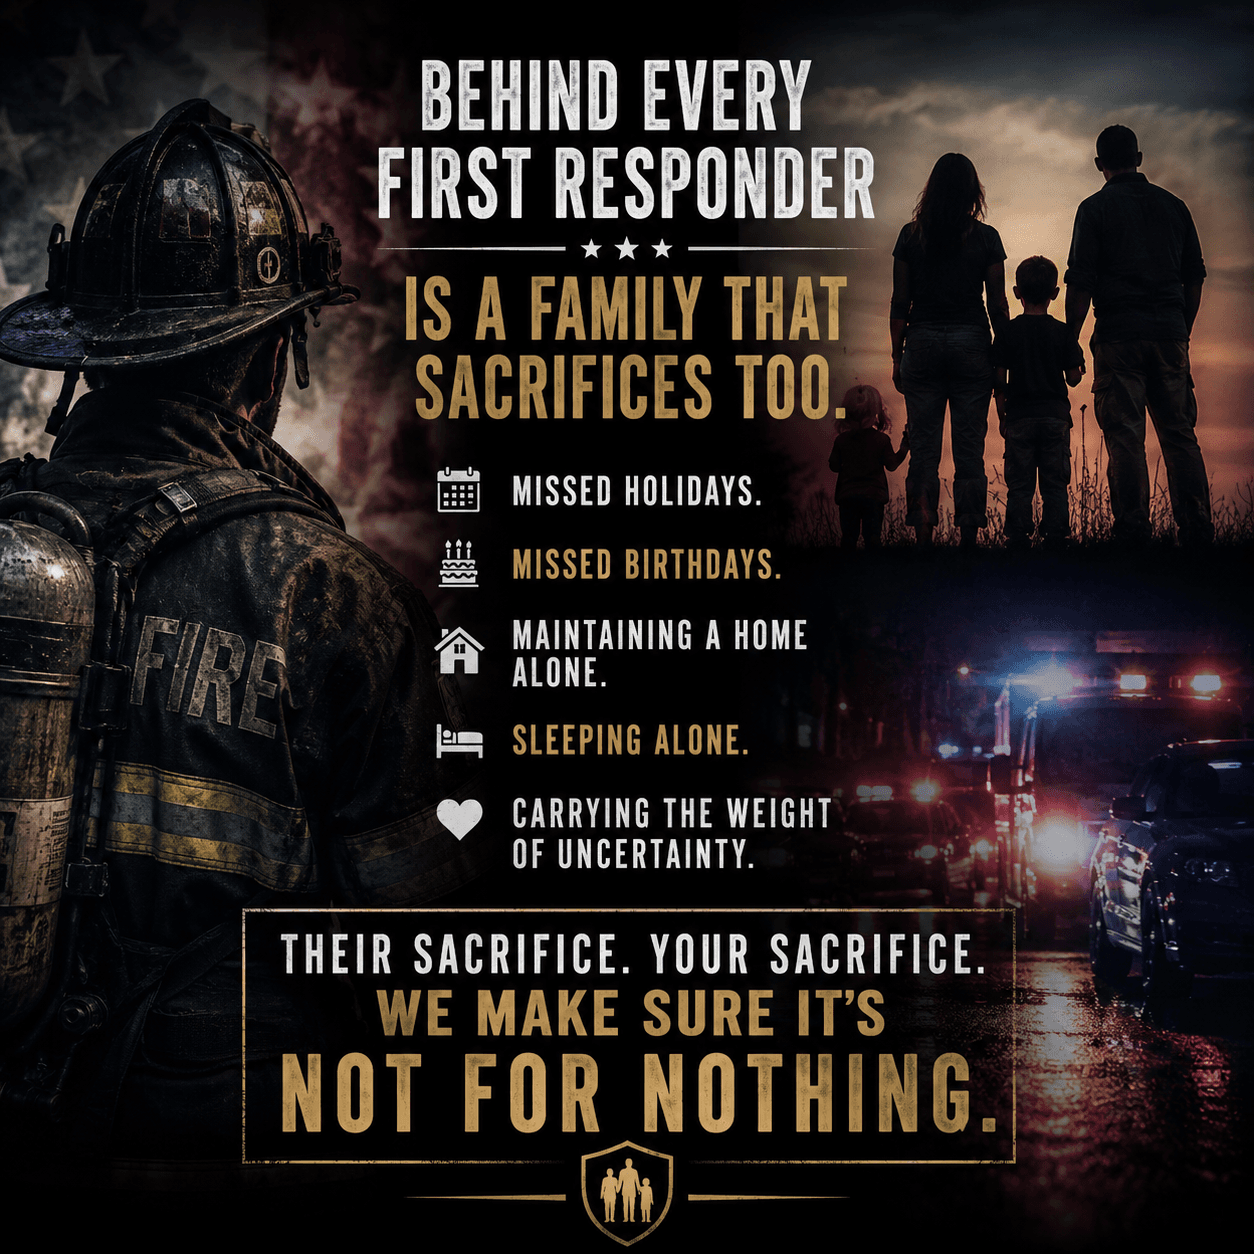
The Sacrifice We Don’t Talk About Enough
When we talk about first responders, the conversation almost always centers around their sacrifice.
And rightfully so.
But there’s another sacrifice that often goes unrecognized…
The family.
The spouse who holds everything together during long shifts, overnight calls, and unexpected overtime.
The kids who grow up understanding that mom or dad might miss birthdays, holidays, or big moments.
The quiet reality of sleeping alone, managing a household solo, and carrying the weight of uncertainty.
This isn’t a one-time sacrifice.
It’s a lifestyle—sustained over an entire career.
That’s why Paul and I are so passionate about working with first responder families—not just the individual.
Because financial planning isn’t just about numbers.
It’s about honoring every sacrifice that was made along the way.
Helping ensure that:
The missed moments meant something
The long nights had purpose
And the family’s commitment was not overlooked
If a career was built on sacrifice, the outcome should reflect it—for everyone involved.
See thrivent.com/social for important disclosures.
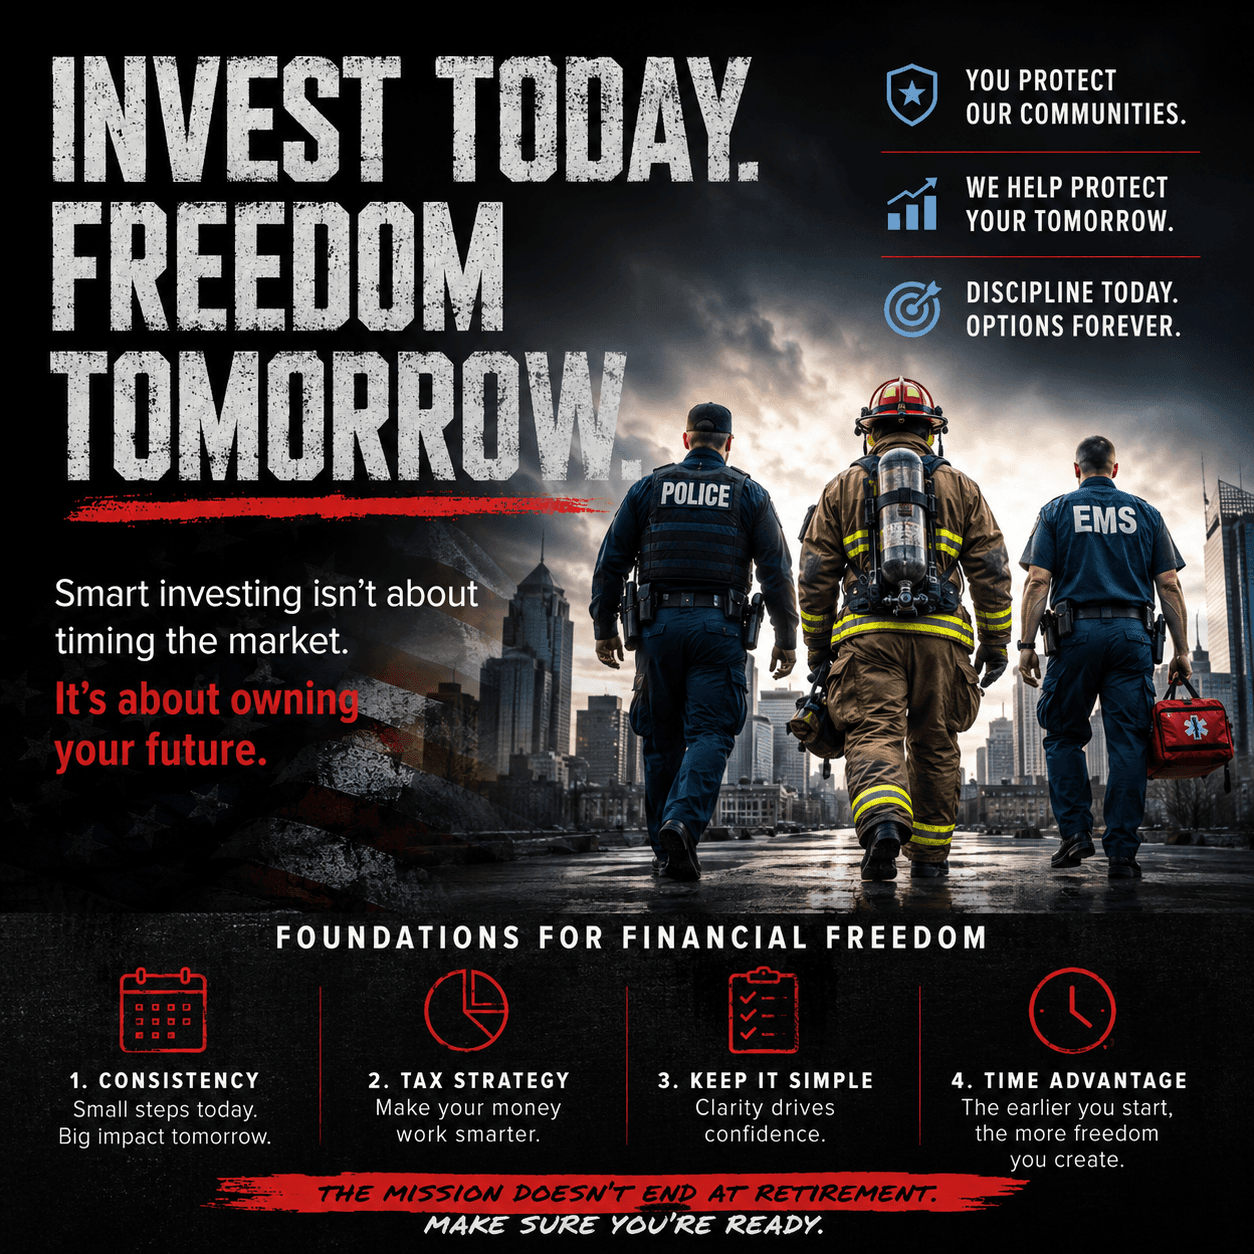
Most First Responders Don’t Have an Investing Problem… They Have a Starting Problem.
After years of working with police officers, firefighters, and EMS professionals, I’ve noticed a consistent pattern:
It’s not a lack of discipline.
It’s not a lack of income.
It’s not even a lack of awareness.
It’s hesitation around where to begin.
Many first responders are doing the right things operationally—contributing to pensions, maybe setting aside money in a 457(b), keeping cash reserves. But when it comes to investing beyond that, there’s often uncertainty:
“Am I taking too much risk… or not enough?”
“Should I be using a Roth or traditional account?”
“What happens if I make the wrong move?”
Here’s the reality:
You don’t need a perfect strategy to get started—you need a disciplined one.
From what we see in the field, the strongest long-term outcomes tend to come from a few foundational behaviors:
• Consistency over timing – Regular contributions matter more than trying to outguess the market.
• Tax awareness – Understanding how pensions, 457(b)s, and Roth strategies work together can significantly impact retirement income.
• Simplicity – Overcomplication is one of the biggest barriers to execution.
• Time in the market – The earlier you start, the more flexibility and options you create later.
For first responders especially, investing shouldn’t exist in a vacuum. It should align with:
Pension timelines
Early retirement goals
Survivor benefits and family protection
The physical realities of the job
The goal isn’t just to build wealth. It’s to build optionality.
Because in this profession, having the ability to retire on your terms—not your body’s terms—is everything.
See thrivent.com/social for important disclosures.
#FirstResponders #LawEnforcement #PublicSafety #FinancialPlanning #RetirementPlanning #WealthManagement #DeferredComp #PensionPlanning #TaxDiversification #RetirementStrategy #FinancialWellness #PlanAhead
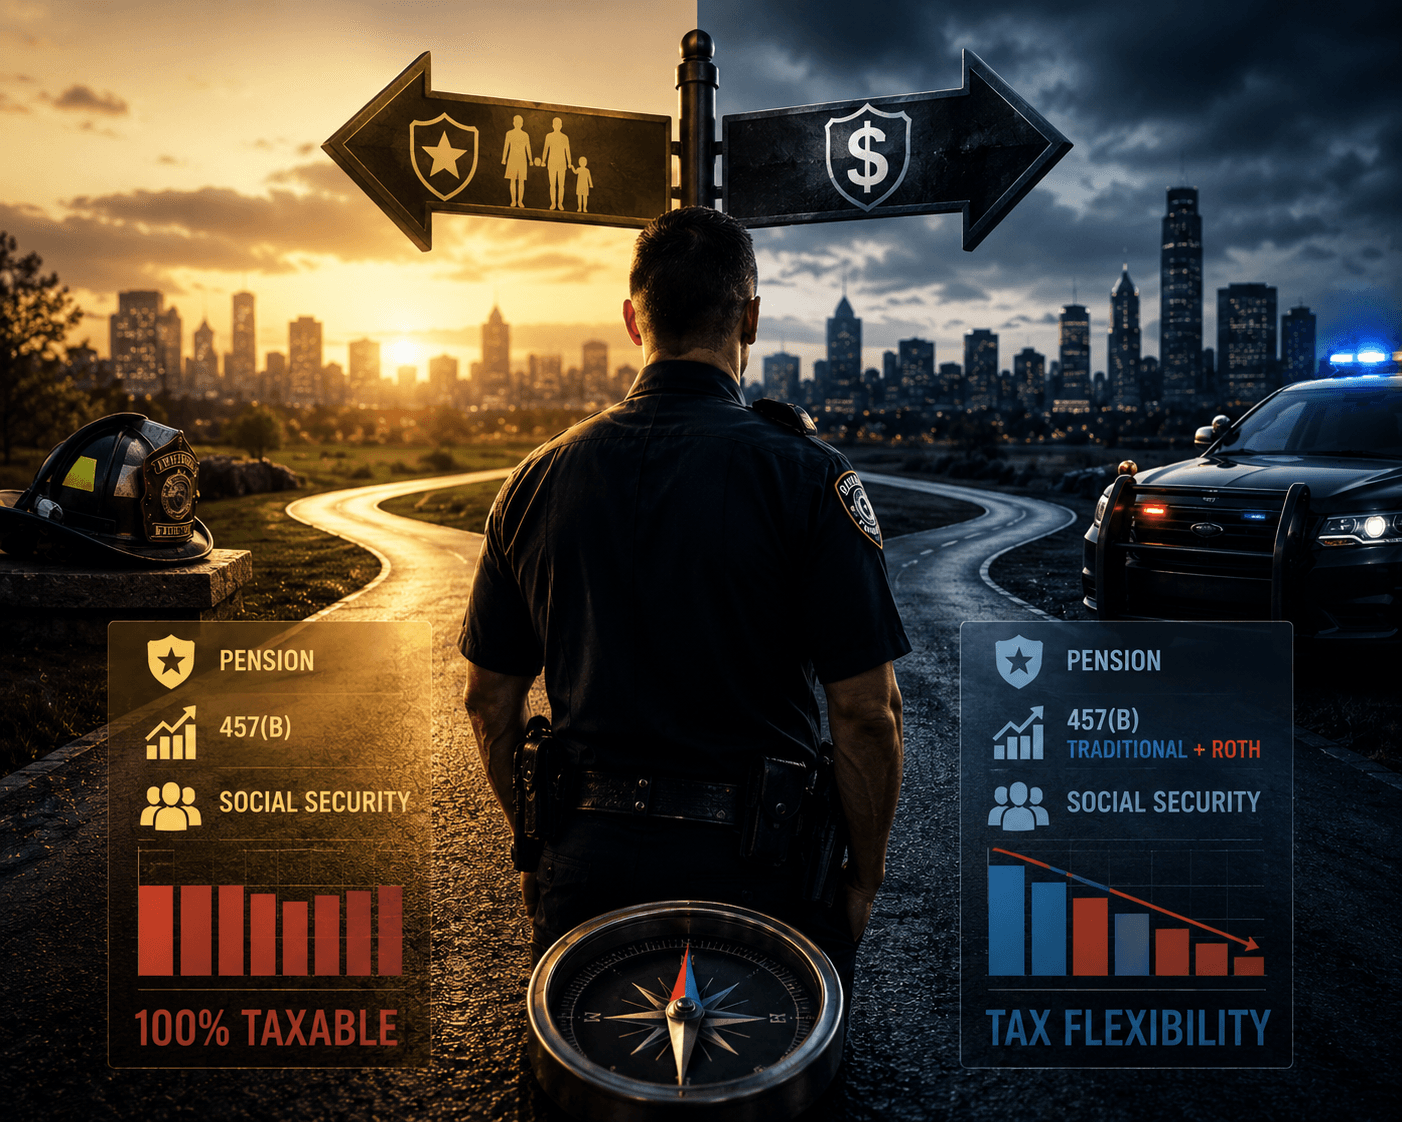
One Decision We See First Responders Miss More Often Than They Should:
A mid-career officer we recently spoke with had accumulated a solid 457(b) balance over the years.
Consistent contributions. Strong growth. Good discipline.
But one thing stood out immediately:
- Every dollar was going into traditional (pre-tax) contributions.
- No Roth exposure. No tax diversification.
And with a pension expected in retirement, that creates a very specific outcome:
➡️ Future income stacked almost entirely in taxable buckets⬅️
👉🏻Pension
👉🏻457(b) withdrawals
👉🏻Social Security
All hitting the same tax environment.
This is something we see more often than most would expect.
It’s not because of poor decisions—it’s because:
- Default elections stay in place
- Contribution types aren’t revisited
- And no one steps in to connect how today’s decisions impact future income
For first responders, retirement income tends to look different than most:
- Guaranteed pension income
- Earlier retirement timelines
- Deferred comp plans with flexible access
Which means the tax structure matters just as much as the amount saved.
These are the types of details Paul and I spend time on with first responders—because small decisions in the accumulation phase can shape outcomes years down the road.
See thrivent.com/social for important disclosures.
#FirstResponders #LawEnforcement #PublicSafety #FinancialPlanning #RetirementPlanning #WealthManagement #DeferredComp #PensionPlanning #TaxDiversification #RetirementStrategy #FinancialWellness #PlanAhead
The Middle Years Are Where Decisions Start to Matter More
Consider this scenario:
A 42-year-old police officer is about halfway through a career. The pension is building, a 457(b) is getting regular contributions, and there’s a Roth IRA on the side.
Everything feels like it’s on track. But over time, many of these accounts have quietly become “set it and forget it.” Contributions go in, allocations stay the same, and little changes year to year.
And the reality is—the city isn’t going to call to make sure everything still lines up with your goals.
As income grows and balances increase, this stage introduces new considerations:
- Are allocations still appropriate given time horizon and risk exposure?
- Is the mix between pension, 457(b), and personal investments working together efficiently?
- Are contributions positioned in a way that supports future tax flexibility?
- What adjustments today could impact options 10–15 years down the road?
Mid-career isn’t just about continuing what’s already in place—it’s where small adjustments can start to have a larger impact over time.
For many first responders, these accounts exist in separate buckets. The value comes from stepping back and making sure they’re working together as part of a broader strategy.
See thrivent.com/social for important disclosures.
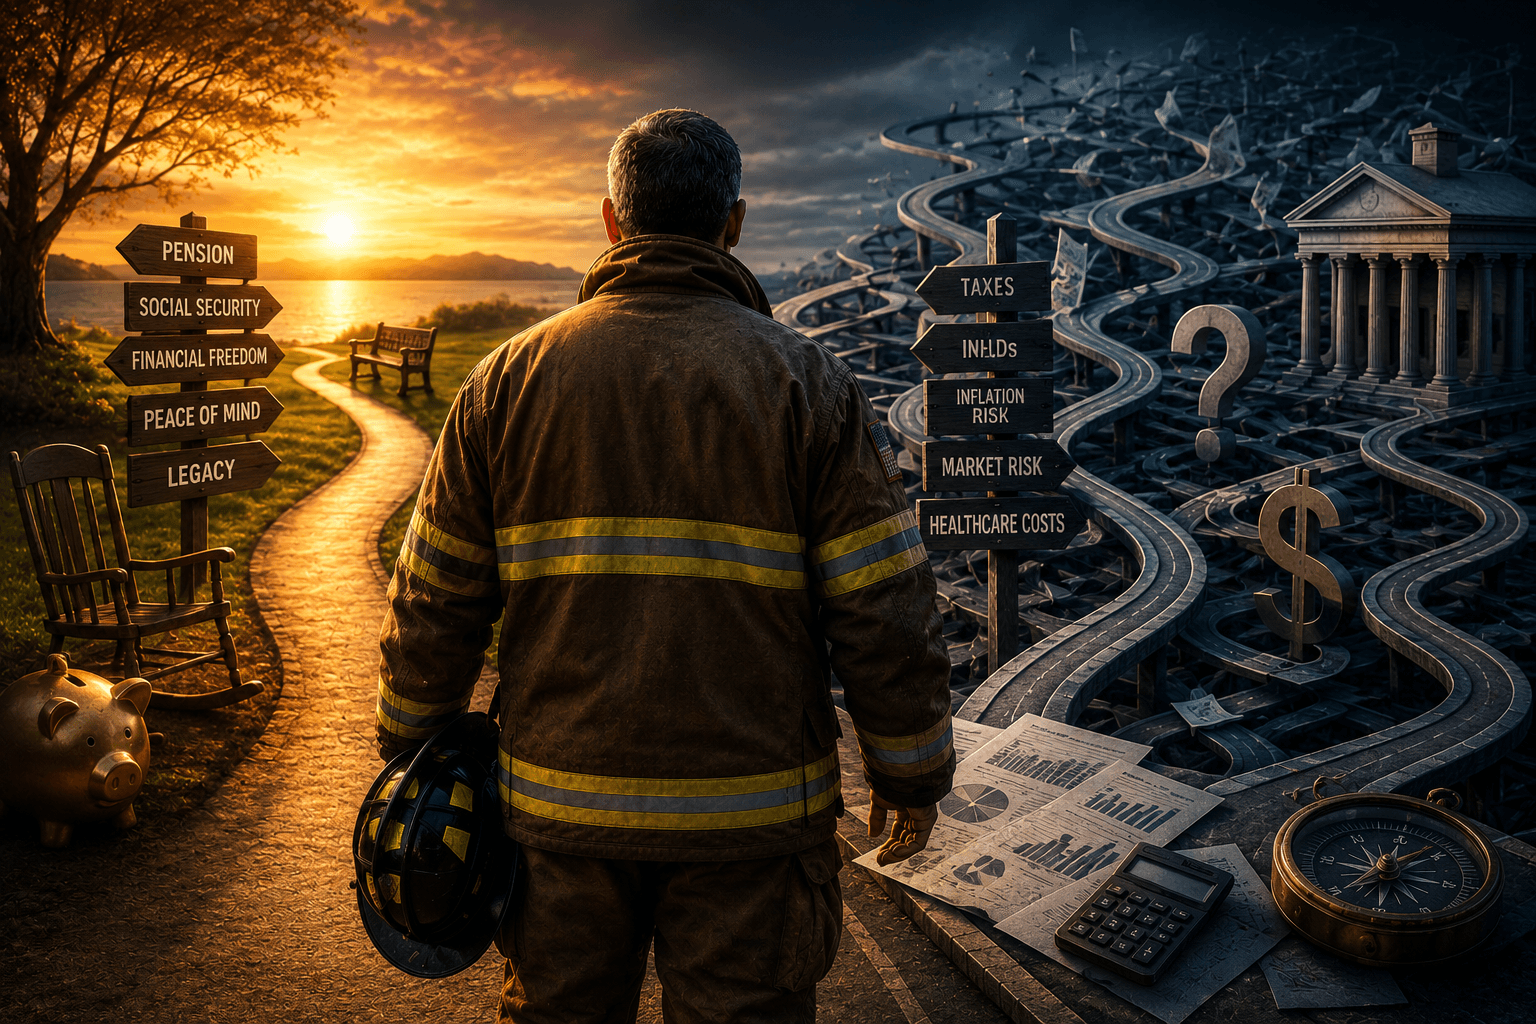
When the Paychecks Stop, the Complexity Begins
Consider this scenario:
A 55-year-old firefighter is planning to retire next year. He’ll receive a pension covering roughly 60% of his final average salary. He also has a deferred compensation (457(b)) plan he’s been contributing to for years, along with a Roth IRA and some non-qualified investments.
On the surface, he feels “set.” But as we walk through the details, several questions come up:
- When should he begin drawing from his 457(b) versus other accounts?
- How will pension income impact his tax bracket long-term?
- Should he consider Roth conversions before Social Security and additional pension income begin?
- How does he bridge the gap between retirement and Medicare eligibility?
- How do all of these income streams coordinate efficiently over time?
For many first responders, retirement isn’t just about having income sources—it’s about coordinating them effectively.
Pensions, deferred compensation plans, Social Security, and personal investments all behave differently from a tax and distribution standpoint. Without a clear strategy, it’s easy to unintentionally create higher tax burdens or reduce overall efficiency.
A structured approach can help align these moving pieces and support more informed financial decisions over time.
If you’re a first responder approaching retirement, it may be worth taking a step back to ensure everything is working together—not just existing in separate buckets.
See thrivent.com/social for important disclosures.
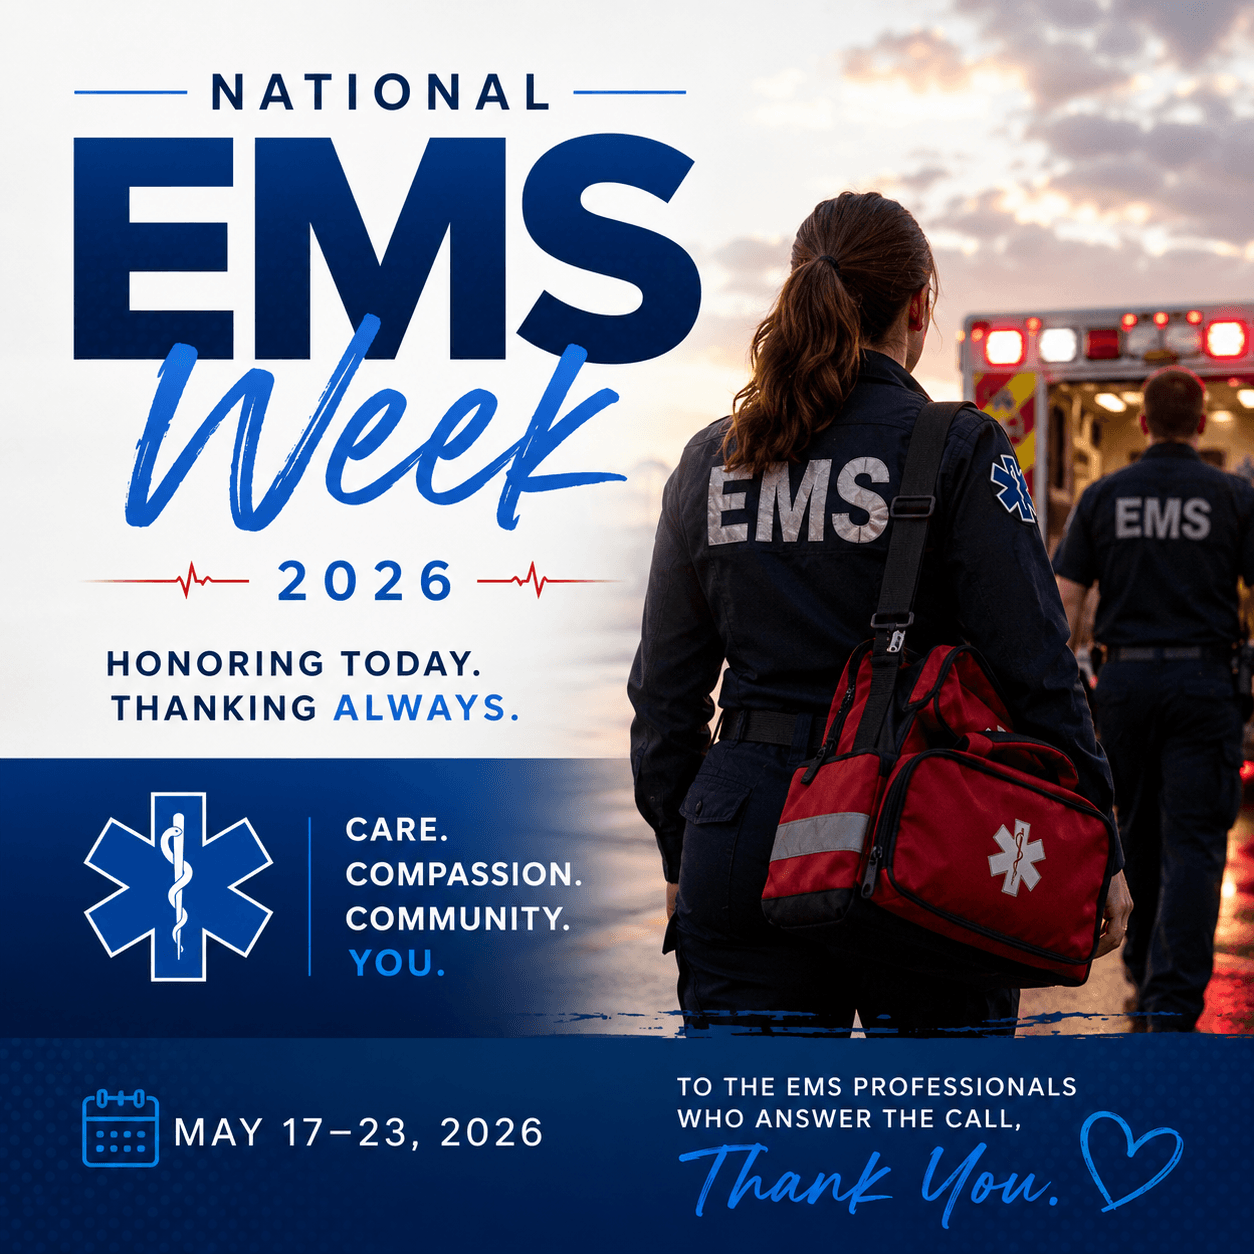
🚑 Honoring National EMS Week 2026 🚑
This week, we recognize and thank the dedicated Emergency Medical Services professionals who serve on the front lines of our communities every day.
From rapid response in critical moments to compassionate care under pressure, EMS teams play a vital role in protecting the health and safety of others—often under extraordinary circumstances. Their commitment, skill, and resilience make a meaningful difference in countless lives.
As we observe National EMS Week, I want to express sincere appreciation for all EMTs, paramedics, dispatchers, and support personnel who continue to serve with professionalism and care.
Thank you for everything you do—for your communities, your patients, and your colleagues.
See thrivent.com/social for important disclosures.
#EMSWeek #ThankYouFirstResponders #Community #Gratitude
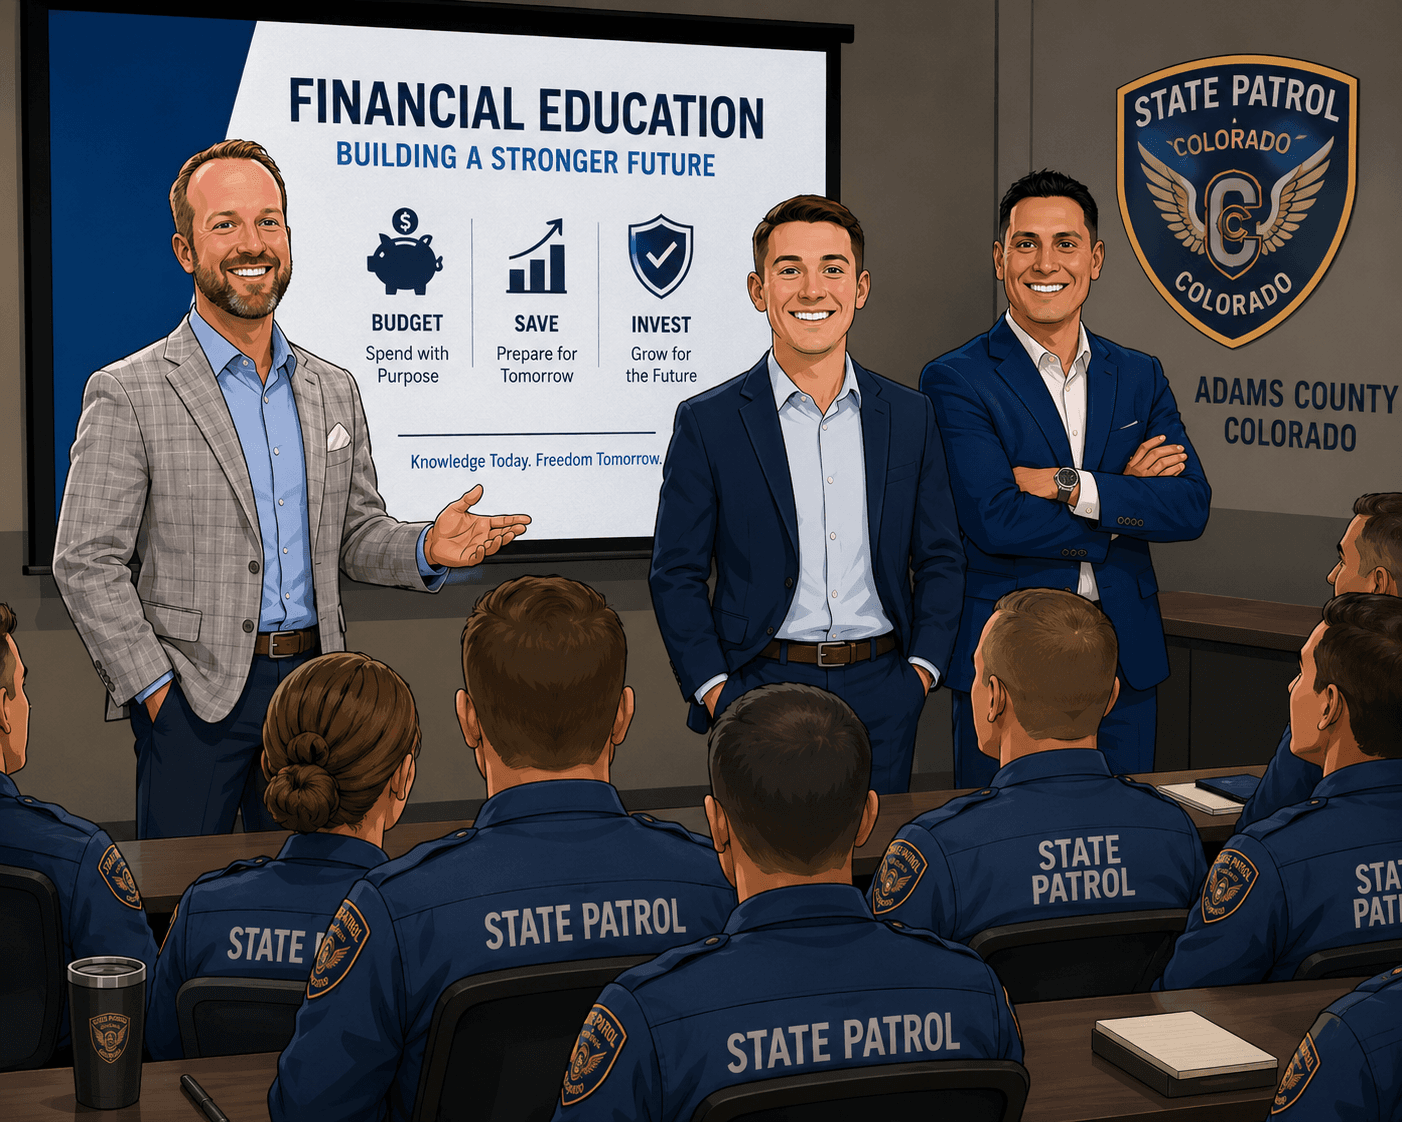
Grateful for the opportunity to spend time with Adams County Colorado State Patrol last week alongside Nathan Hardy and Paul Osckel to lead a financial wellness workshop.
We truly appreciated the conversation, engagement, and the chance to support such a dedicated group of professionals.
When law enforcement leaders prioritize the financial well-being of their officers, the impact extends beyond the workplace—supporting not only the officers themselves, but also their families and the communities they serve.
Thank you again for having us out.
See thrivent.com/social for important disclosures.
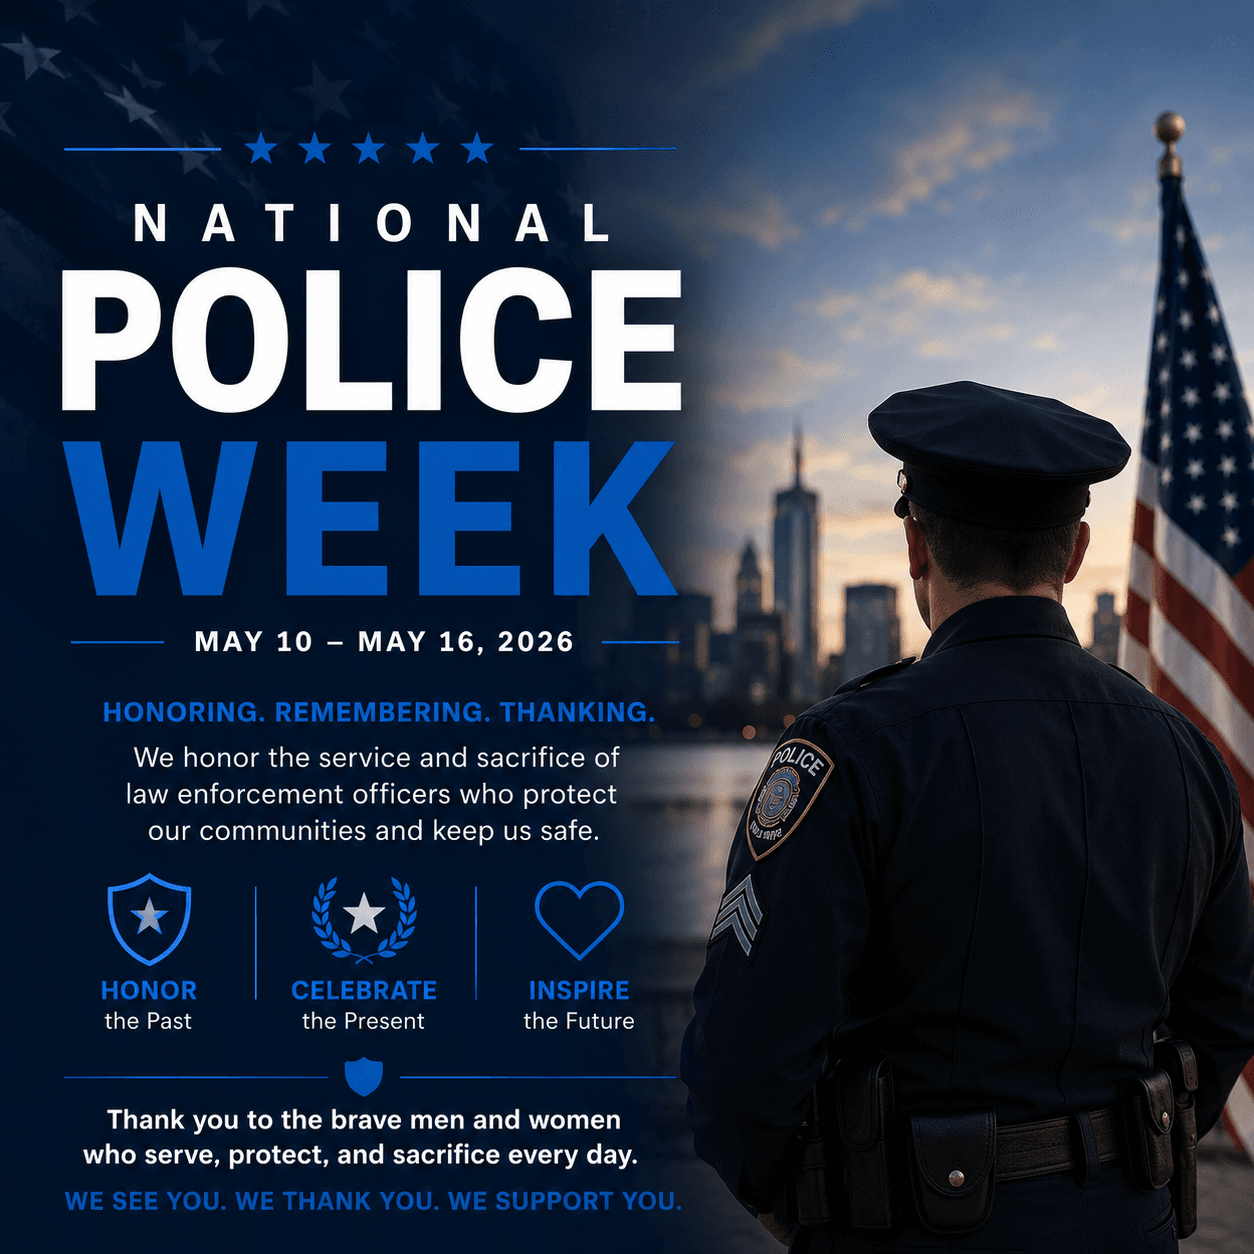
National Police Week (May 10–16, 2026) is a time to pause and recognize the men and women who serve, protect, and sacrifice for our communities every single day. This is a week that doesn’t get nearly the attention it deserves, yet it represents courage, commitment, and selflessness at the highest level. To all those who wear the badge—and to their families who stand behind them—thank you. Your service does not go unnoticed, and it never will.
First responders don’t struggle with discipline—they often benefit from additional clarity when it comes to long-term retirement planning.
In working with public safety professionals, I’ve consistently observed that retirement preparedness is less about any single financial product and more about planning structure, consistency, and long-term decision-making.
A few educational themes that frequently come up in this space include:
• Retirement readiness begins with understanding estimated income needs rather than assumptions
• Pension benefits may serve as a foundational component, but are typically one part of a broader retirement strategy
• Tax diversification across account types may provide additional flexibility in retirement income planning
• Deferred compensation and supplemental retirement accounts may serve as planning tools depending on individual circumstances
• Risk management, including insurance considerations, can be an important part of overall financial planning
• Retirement timing should remain flexible and based on evolving personal goals and financial conditions
• Financial stress is one factor that may impact overall well-being, particularly in high-stress professions
• A written financial plan can help organize assumptions, goals, and long-term planning decisions
The goal isn’t just to “retire someday”—it’s to create a plan today so you have options tomorrow.
See thrivent.com/social for important disclosures.
#FirstResponders #RetirementPlanning #FinancialWellness #PublicSafety #WealthStrategy
First responders spend their careers protecting others—your financial future deserves the same level of discipline and strategy.
Strong retirement outcomes are built through consistent, intentional actions over time:
• Maximize contributions to available retirement plans
• Be thoughtful about tax strategies today and in the future
• Use tools like HSAs to prepare for potential healthcare costs
• Allocate overtime or additional income toward long-term savings
• Regularly review benefits, insurance, and overall risk exposure
• Maintain a balance between liquidity and long-term investments
The reality: retirement planning for first responders can be complex. Pensions, deferred compensation plans, and earlier retirement timelines often require coordination.
No single strategy fits everyone, and outcomes will vary based on individual circumstances, time horizon, and market conditions. A well-structured approach can help create greater understanding and flexibility over time.
#FirstResponders #RetirementPlanning #FinancialWellness #PublicSafety #WealthStrategy
See thrivent.com/social for important disclosures.