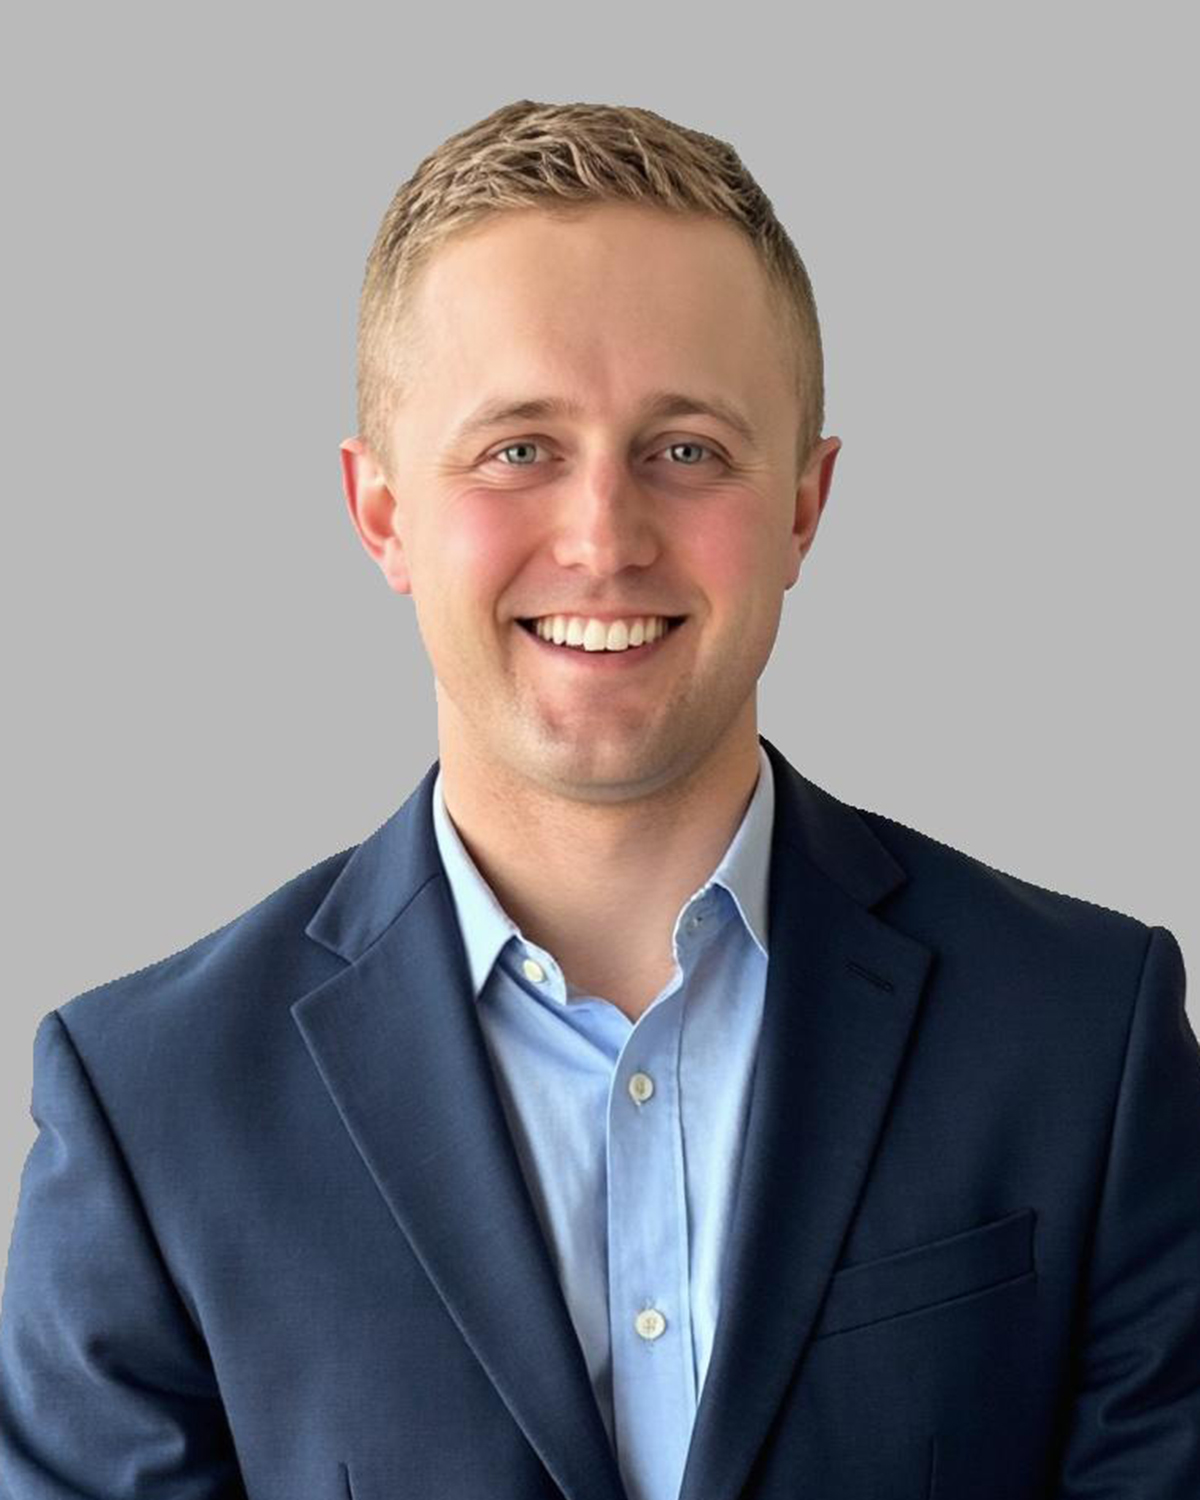
Financial Advisor
.Tax Efficient Planning
Retirement Planning
I am a lifelong resident of MT. I was born and raised in Billings and graduated from Montana State University. After earning my degree in math, God led me to the start of my financial career with a local bank as a loan officer before joining the Thrivent team. As a financial advisor I am so thankful that I get to work in an industry that allows me to use my experience and knowledge to serve clients in such a meaningful way. I love helping people maneuver and understand the often, complex financial world and ensure that they are being intentional and wise with the gifts they have been given.
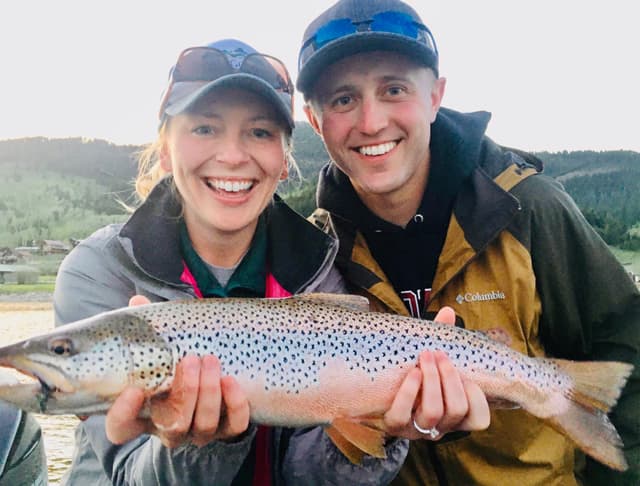
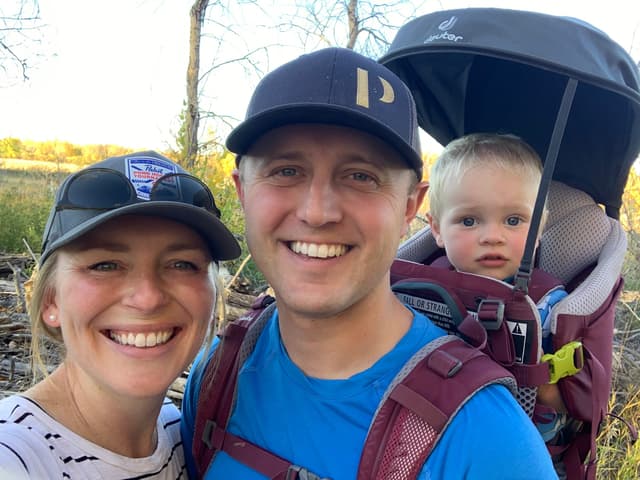
By far my favorite title is that of husband and dad. I am happily married to my beautiful wife Holly. We are blessed with a little boy (Elijah) who keeps us on our toes but at the same time brings us so much joy. He often has too much energy to keep contained in the house so we love getting out for Bobcat football games, hiking with our dog Maggie, skiing, fishing or any of the other activities the Montana outdoors have to offer.
- Bachelors of Mathematics, Montana State University
- Series 7 - General Securities Representative
- Series 66 - Investment Adviser Representative
- Securities Industry Essentials
- Montana
Insights
Have you ever wondered whether paying taxes now could potentially help reduce taxes later? It's a conversation worth having as part of a broader retirement income strategy.
Tax planning can involve paying taxes when it may be most advantageous to do so, whether that's because you expect to be in a higher tax bracket later in life or because of other factors such as Required Minimum Distributions (RMDs), IRMAA surcharges, or changes to your income sources.
Whether a Roth conversion makes sense is highly dependent on your individual situation. Factors that may come into play include your age, current and future income, living expenses, retirement goals, available assets, and how much tax you're willing to pay today in exchange for potential benefits in the future.
If you're nearing retirement or have recently experienced a significant change in income, it may be a good time to sit down with a financial professional and discuss whether a Roth conversion strategy aligns with your overall financial plan.
See thrivent.com/social for important disclosure information
Office location
Billings Location
19 36th Street West, ste 2
Billings, MT 59102
Phone406-294-6400HoursBillings, MT 59102
M – F: 9 a.m. – 5 p.m.
Licensing is available through your State Insurance Department’s website, which can be located through the National Association of Insurance Commissioners website.
Thrivent and its financial advisors and professionals do not provide legal, accounting or tax advice. Consult your attorney or tax professional.
Thrivent financial advisors and professionals have general knowledge of the Social Security tenets. For complete details on your situation, contact the Social Security Administration.
Thrivent provides advice and guidance through its Financial Planning Framework that generally includes a review and analysis of a client’s financial situation. A client may choose to further their planning engagement with Thrivent through its Dedicated Planning Services (an investment advisory service) that results in written recommendations for a fee.
Designations
For additional information on professional designations and the requirements to earn them, visit https://www.thrivent.com/designations
Thrivent and its financial advisors and professionals do not provide legal, accounting or tax advice. Consult your attorney or tax professional.
Thrivent financial advisors and professionals have general knowledge of the Social Security tenets. For complete details on your situation, contact the Social Security Administration.
Thrivent provides advice and guidance through its Financial Planning Framework that generally includes a review and analysis of a client’s financial situation. A client may choose to further their planning engagement with Thrivent through its Dedicated Planning Services (an investment advisory service) that results in written recommendations for a fee.
Designations
For additional information on professional designations and the requirements to earn them, visit https://www.thrivent.com/designations