Are you wrestling with the decision of when to start your Social Security benefit?
You can claim your Social Security benefit as early as age 62, but for many people retiring today, full retirement age is 67. If you choose to delay beyond full retirement age, your benefit may increase by approximately 8% per year until age 70.
So should you file as soon as you're eligible, or wait to maximize your monthly benefit?
Before letting Social Security put you in a headlock, it's important to remember that claiming benefits shouldn't be a stand-alone decision.
We often tell clients to think of Social Security as just one leg of their retirement stool. While maximizing your benefit may sound appealing, the best claiming strategy depends on how Social Security fits into your overall retirement income plan. Your other income sources, tax considerations, health and longevity expectations, and the implications for a spouse should all be part of the conversation. Looking at the bigger picture is often more important than focusing solely on maximizing your Social Security benefit.
Before making a claiming decision, consider speaking with a financial advisor who can help you evaluate your complete financial picture.
See thrivent.com/social for important disclosure information
When your children inherit your IRA, they may inherit a tax bill too.
For many families, retirement accounts are among the largest assets they'll leave behind. Yet many people don't realize that traditional IRAs and pre-tax retirement accounts can create taxable income for beneficiaries.
Under current rules, many non-spouse beneficiaries are required to fully distribute inherited retirement accounts within 10 years of the original owner's death. Depending on their circumstances, that can result in significant taxable income during what may be their peak earning years.
For example, if an individual inherits a traditional IRA worth $1,000,000 and withdraws the funds evenly over 10 years, that's roughly $100,000 of additional taxable income each year. Depending on their financial situation, those distributions could push them into higher tax brackets and result in a larger share of the inheritance being paid in taxes.
Many people focus on the amount they'll leave behind. Just as important is understanding how much of those assets may ultimately be available to their heirs after taxes.
Taxes can never be eliminated entirely, but thoughtful planning today may help reduce the tax burden beneficiaries face in the future.
The question isn't just how much you'll leave behind. It's how much your heirs may get to keep.
See thrivent.com/social for important disclosure information
Have you ever wondered whether paying taxes now could potentially help reduce taxes later? It's a conversation worth having as part of a broader retirement income strategy.
Tax planning can involve paying taxes when it may be most advantageous to do so, whether that's because you expect to be in a higher tax bracket later in life or because of other factors such as Required Minimum Distributions (RMDs), IRMAA surcharges, or changes to your income sources.
Whether a Roth conversion makes sense is highly dependent on your individual situation. Factors that may come into play include your age, current and future income, living expenses, retirement goals, available assets, and how much tax you're willing to pay today in exchange for potential benefits in the future.
If you're nearing retirement or have recently experienced a significant change in income, it may be a good time to sit down with a financial professional and discuss whether a Roth conversion strategy aligns with your overall financial plan.
See thrivent.com/social for important disclosure information
Did you know that some retirement plans may allow you to access your 401(k) savings before age 59½ without the 10% early withdrawal penalty?
Normally, withdrawals from qualified retirement plans before age 59½ may be subject to a 10% early withdrawal penalty in addition to any applicable taxes.
However, some employer-sponsored retirement plans may allow penalty-free withdrawals beginning at age 55 under a provision commonly referred to as the Rule of 55.
The Rule of 55 generally applies to individuals who separate from service during or after the year they turn age 55, and eligibility depends on the specific provisions of the retirement plan.
Many people accumulate a significant portion of their retirement savings in workplace retirement plans and may not be aware of the options available to them.
Understanding how your retirement plan works can be an important part of evaluating your overall retirement strategy.
If you're curious whether your plan allows Rule of 55 distributions, consider contacting your retirement plan provider for details and discussing with an advisor how it may fit into your broader financial picture.
See thrivent.com/social for important disclosure information.
“How much do I actually need to retire?”
Most people expect a number… but that’s not really how retirement works.
Two people can both have $1,000,000 saved— and have completely different retirement outcomes.
Why?
It comes down to things like taxes, income strategy, and when you take Social Security.
Retirement isn’t just about how much you have… it’s about how your plan works.
If you’re getting close to retirement, now is the time to make sure everything is aligned.
See thrivent.com/social for important disclosure information.
Thrivent Social Media Privacy Policy, Guidelines, Disclosures & DisclaimersAs people get closer to retirement, one question tends to come up:
What do I actually do with my 401(k)?
Leave it where it is?
Roll it over?
Start taking income?
What many people don’t realize is that each option comes with different considerations depending on things like timing, goals, and overall situation.
It’s not always as simple as just picking one path and moving forward.
If you're approaching retirement, it’s a conversation worth having—and one I’d be glad to have with you as you think through your next steps.
See thrivent.com/social for important disclosure information.
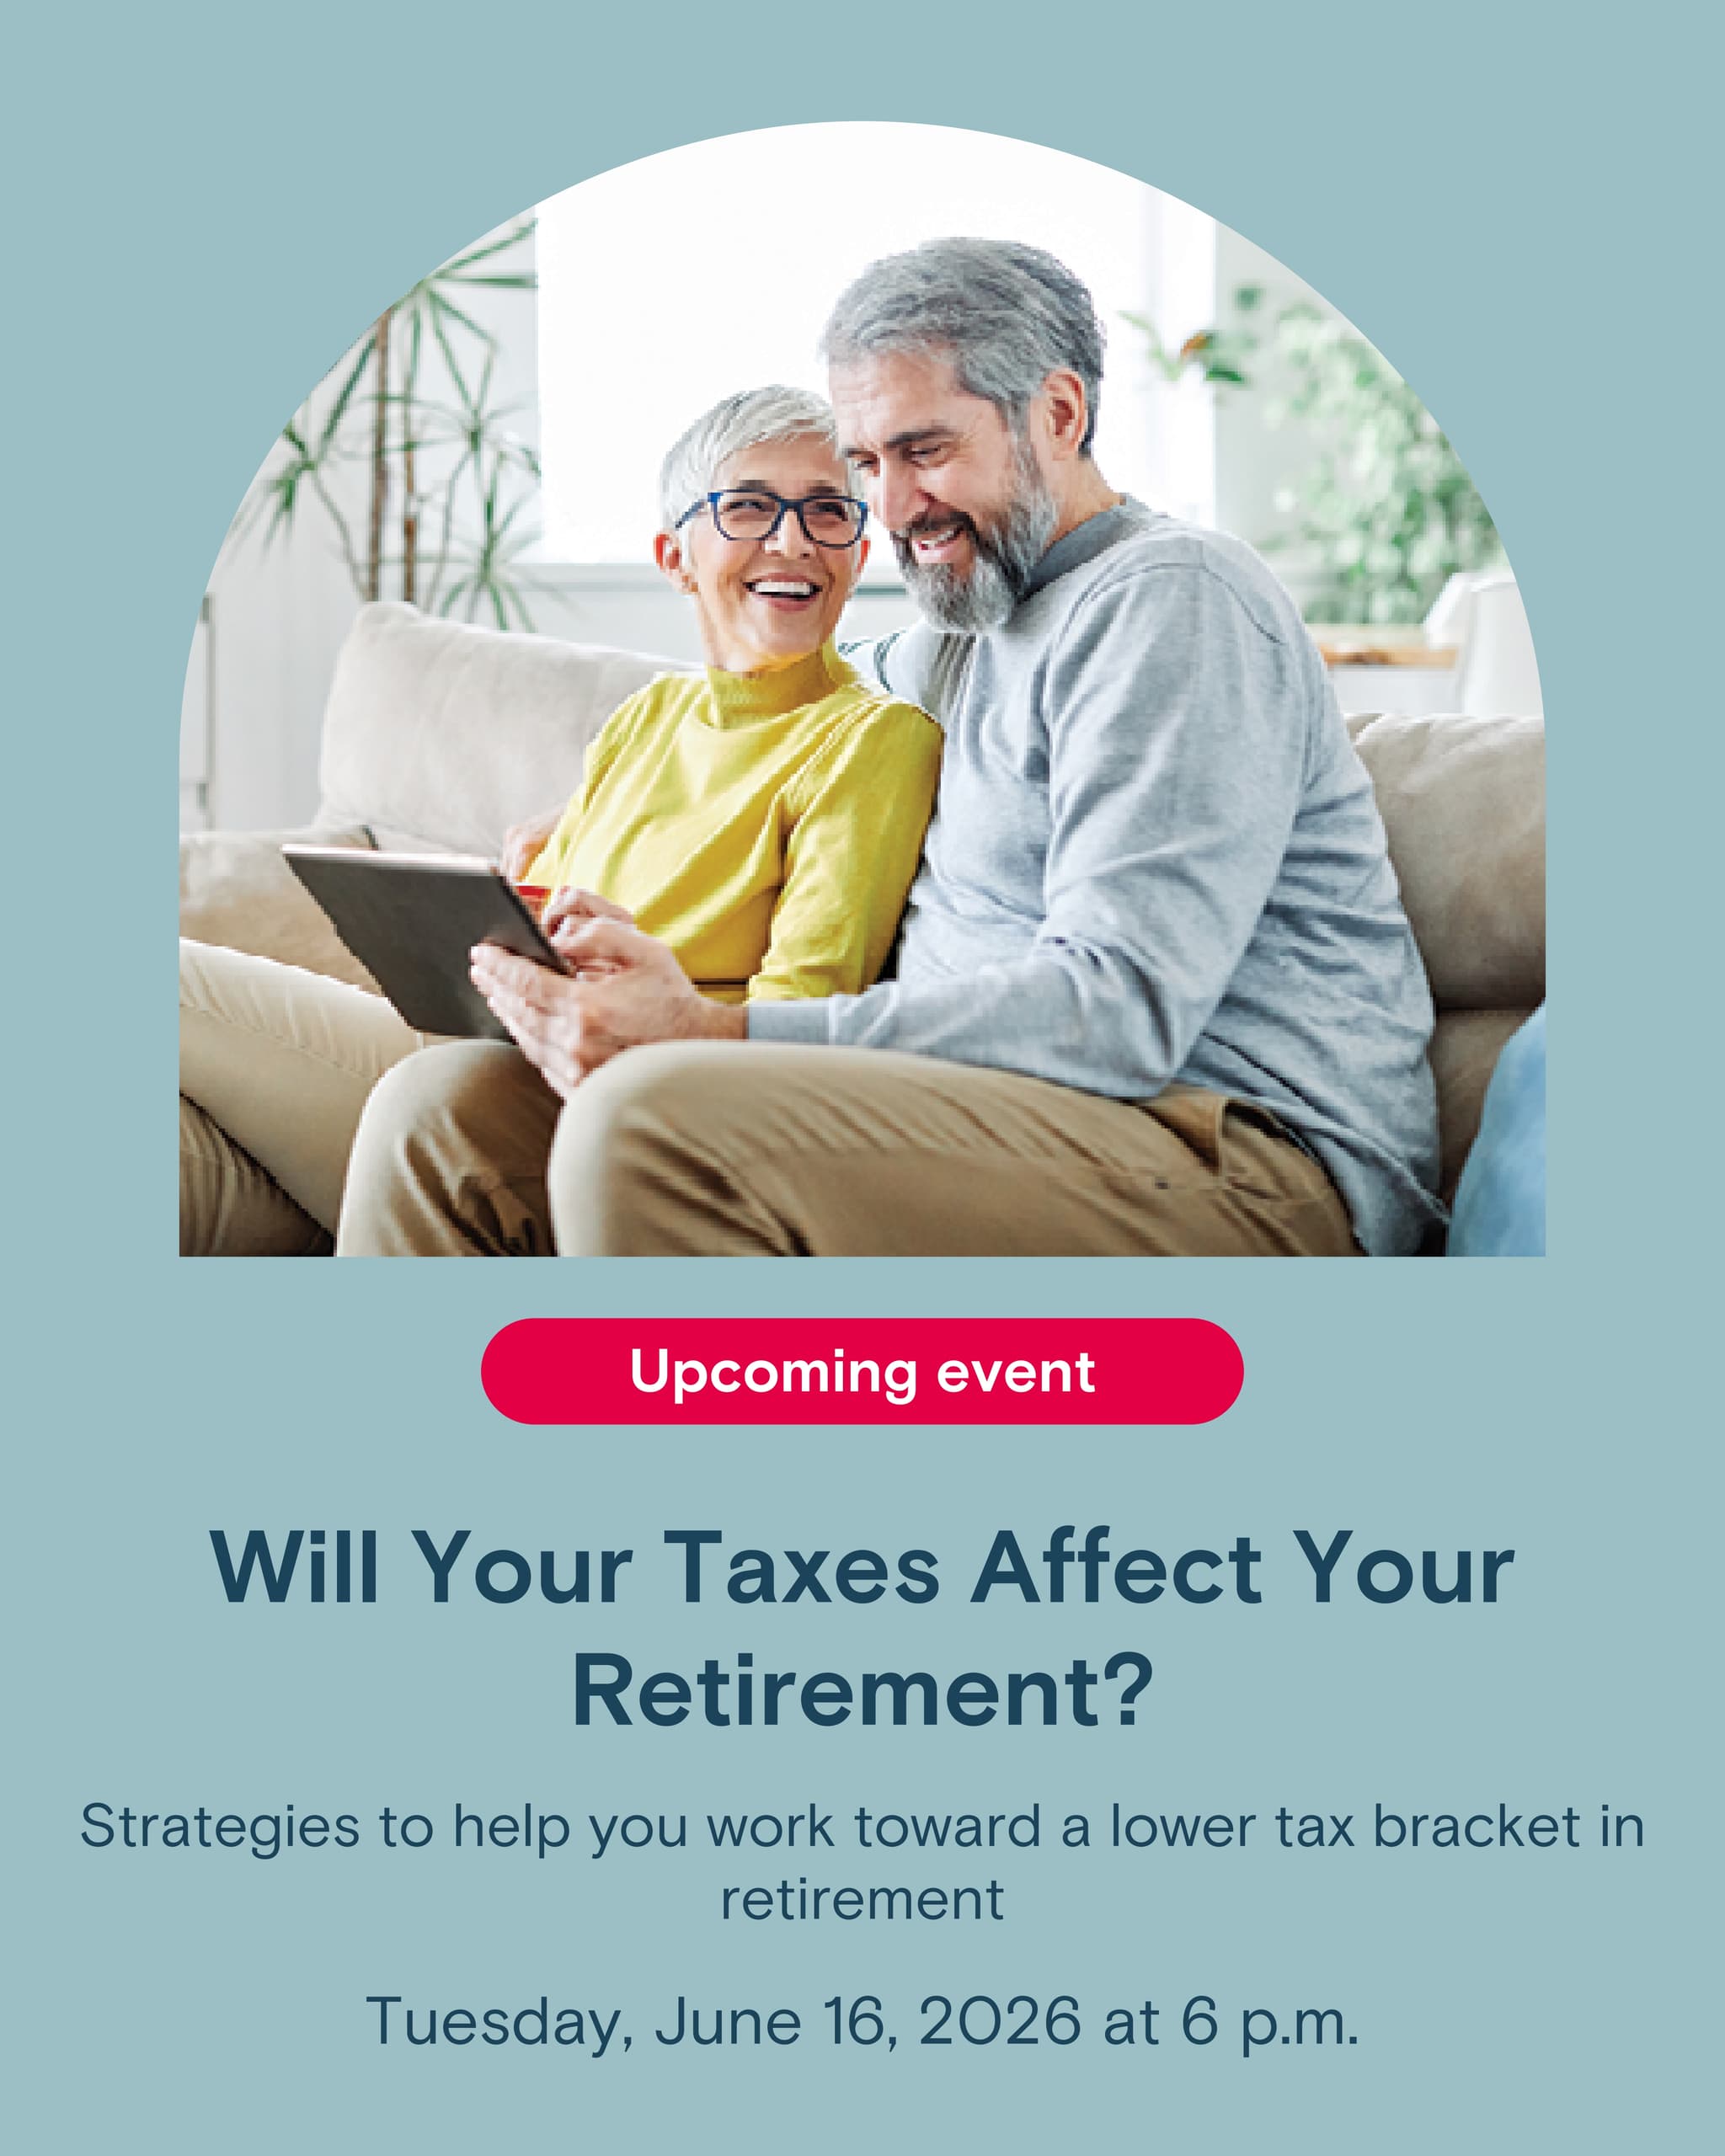
When you retire, you leave behind many things—the daily grind, the commute to work, and maybe even your previous home. However, one thing that will always remain is your tax bill. When you understand how investments are taxed and set strategies accordingly, you can make the right decisions that help keep income taxes in check.
Location: Fairfield Inn & Suites Laurel, MT (301 S Washington Ave Laurel, MT 59044)
Date: Tuesday June 16th
Time: 6:00 PM
Seating is limited. Reserve your spot today: https://forms.office.com/Pages/ResponsePage.aspx?id=uUYFAv3dm0WJ0RKlPyel4nSJVlR4MLxAt_nhuyBJlv1UQUdXOE84Q1YwREEwWVJFM0tDVlJIVkg1OC4u
No products will be sold.
Thrivent financial advisors and professionals have general knowledge of the Social Security tenets. For complete details on your situation, contact the Social Security Administration.
Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional.
See thrivent.com/social for important disclosures.
27878-15M R11-20
Gain insight into the potential ripple effects of energy sector disruption with John Groton, Thrivent’s Sector Lead for Materials, Energy and Utilities: https://bit.ly/4myuzf0
Location: Billings Public Library 2nd Floor Conference Room
There's still space available at my free April 8th workshop, Social Security: Timing Is Everything. Learn more about how you can optimize Social Security. Register now:
https://forms.office.com/Pages/ResponsePage.aspx?id=uUYFAv3dm0WJ0RKlPyel4nSJVlR4MLxAt_nhuyBJlv1UNjkwNjZSWDk1RElSOTM5WjFETUpRUzhTQS4u
No products will be sold. 27878-9M R3-24
How to know if you're saving enough for retirementRoadblocks happen, but they don't have to stop your progress. Discover how to stay on track with your retirement goals. 👇
Have you wondered how you can optimize Social Security or how much you can expect to receive from other income sources? Join me for my free Social Security: Timing Is Everything workshop on April 8th. Register now:
https://forms.office.com/Pages/ResponsePage.aspx?id=uUYFAv3dm0WJ0RKlPyel4nSJVlR4MLxAt_nhuyBJlv1UNjkwNjZSWDk1RElSOTM5WjFETUpRUzhTQS4u
No products will be sold. 27878-9M R3-24
Estate planning for blended familiesHave you thought about how you’d like to leave behind your money and assets? Creating an estate plan in a blended family can be more complex, but in the end it may help your loved ones avoid probate, confusion and conflict.
Here are things to consider if you are creating an estate plan for the first time or need to update an existing one. ⬇️
7 ways to help reduce your taxable incomeSeeing your hard-earned money go towards taxes can be frustrating. However, there are ways you can help reduce your tax burdens and become more tax efficient. ⬇️
8 ways to get serious about paying off student loan debtIs paying off your student loans high up on your priority list? Here are ways to pay off your loans faster, while managing your other financial priorities. ⬇️
The importance of estate planning: Protecting your people, property & privacyEstate planning isn’t just for the wealthy, it’s for everyone. It’s about making sure your assets, no matter their value, go to the people, causes and organizations you care about. Take control of your legacy.
S&P Global Ratings Affirms Thrivent’s AA+ (Very Strong) Rating with Stable OutlookProud to be part of a financially strong and stable organization committed to serving clients for the long-term! S&P, an independent rating agency, recently affirmed Thrivent’s AA+ (Very Strong) rating along with a stable outlook. Learn more. ⬇️
May 2025 Market Update: Volatility goes up and downMixed economic data in April presents a lot of uncertainty in the economic markets. Read Thrivent Asset Management's analysis on what this means for investors in the May Market Update.
Taking Social Security early? Reasons to consider (with pros & cons)Should you take Social Security early? It depends on your unique needs. Before deciding, make sure to take the pros and cons into consideration.
Together, we can talk about your Social Security income and retirement savings to help determine whether claiming benefits early makes sense.
Retirement savings by age: How much should you have?Planning for retirement can seem like a long and complex journey. Knowing how much to save is a foundational piece of achieving your retirement goals—check out these planning milestones based on your age.