Business owners: you're likely overpaying taxes on money you already give away.
You’re giving to charity…but getting little to no tax benefit in return.
I’m seeing this more and more in 2026.
Because of recent tax changes, a lot of personal giving:
• Doesn’t move the needle on taxes
• Is done with fully taxed dollars
Here’s what most people miss:
There may be a more efficient way to structure that same giving.
Which can mean:
• Lower taxable income
• Reduced self-employment exposure
• Better overall tax positioning
Not because of a loophole…but because of how it’s structured.
Examples I’m reviewing with clients right now:
• Event sponsorships that double as marketing
• Revenue-based giving strategies
• Community partnerships that drive visibility
Same dollars. Different structure. Different outcome.
If you’re already giving or planning to this year, this is worth getting right.
If you want to see if this could apply to your situation, feel free to message me and we can walk through it.
Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional. Disclosures: thrivent.com/social
Here’s a tax change most business owners haven’t noticed yet...
Starting in 2026, many employer-paid meals, coffee, and breakroom snacks are no longer deductible.
You can still offer them.
But you don’t get the tax break anymore.
Not a huge cost on its own, but over time it adds up and can influence decisions around employee perks, culture, and office experience.
This is a good reminder that sometimes the biggest financial impacts come from the smallest line items.
If you want to discuss, please call me on my direct line at 360-777-6911 or email me at joe.davis@thrivent.com.
Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional. Disclosures: thrivent.com/social
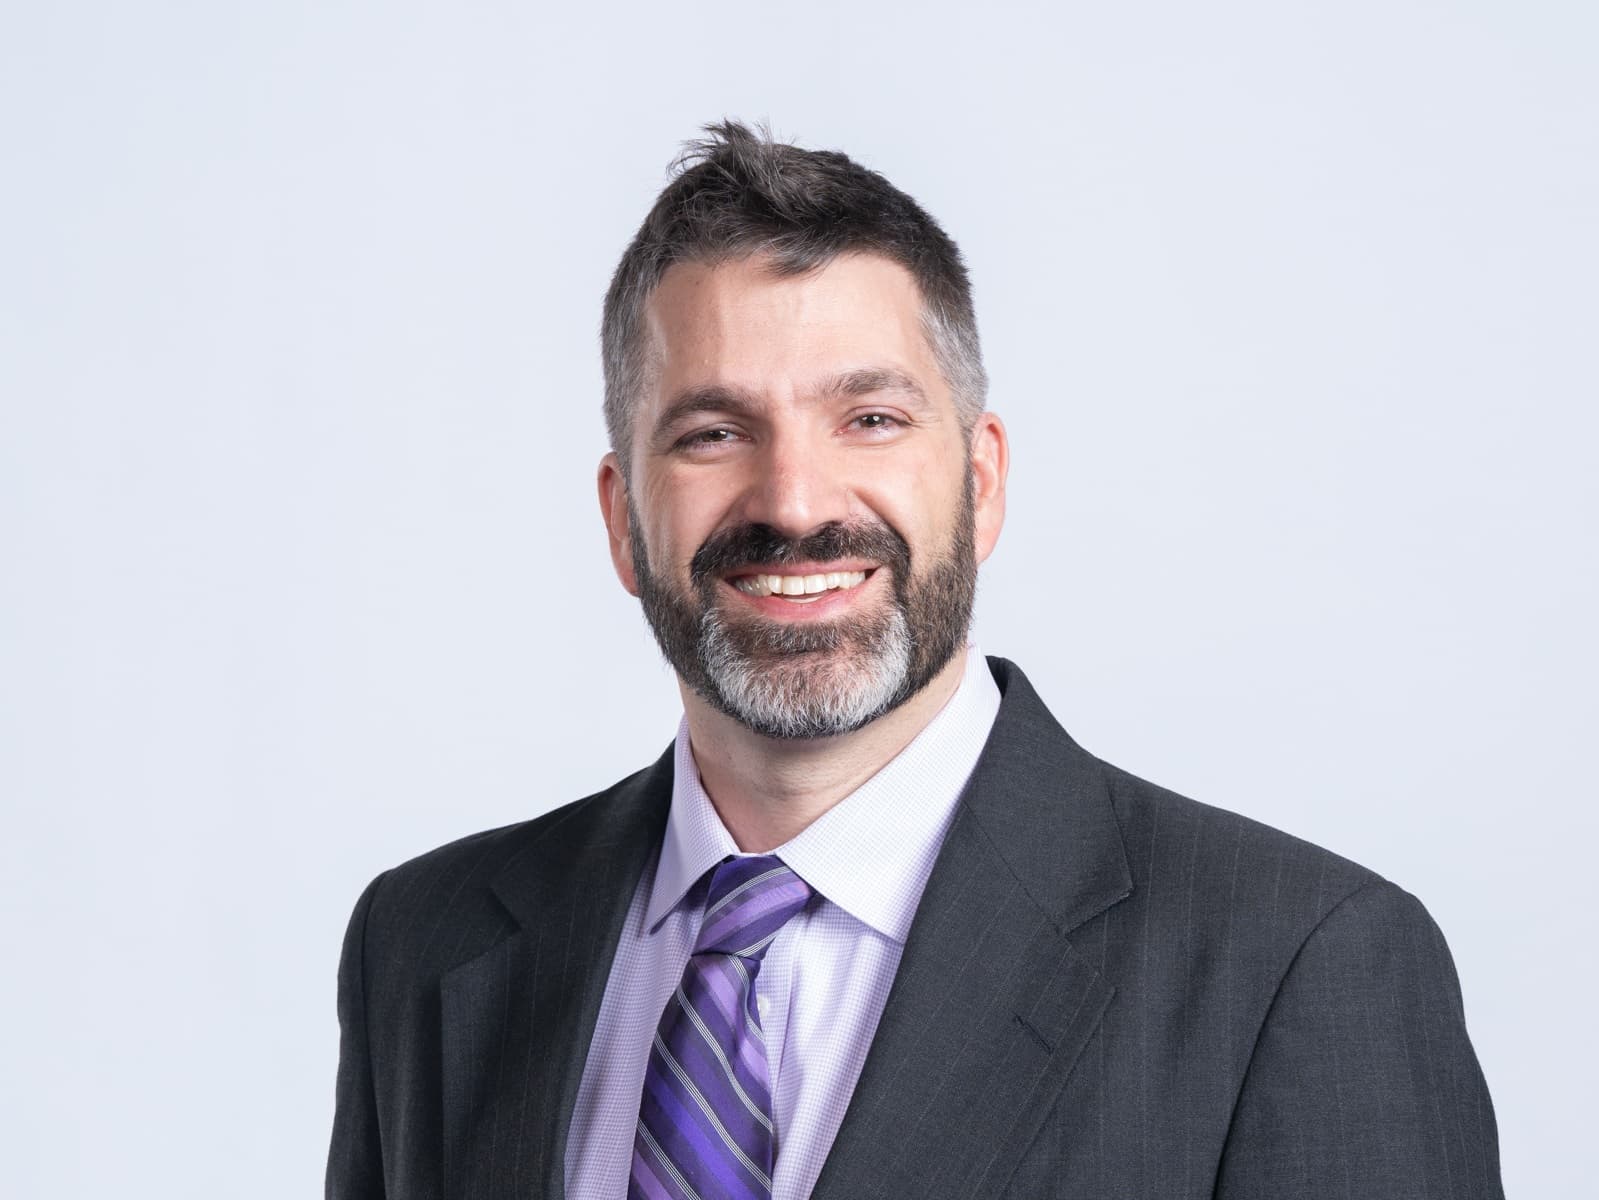
Gig Harbor Library is hosting Joe Davis who works at Thrivent for a Financial Literacy program titled “5 Keys to Retiring Fearlessly” workshop and discover practical strategies to secure your financial future. Build guaranteed income? Protect your savings from market volatility? Safeguard your retirement from life’s “what ifs?”
Workshop is 530pm-630pm at the Gig Harbor Library main conference room on 29 April and refreshments will be available.
Find out more about Joe Davis at https://connect.thrivent.com › joe-davis.
No products will be sold. 27878-8M R9-25
Gig Harbor Library is hosting Joe Davis who works at Thrivent for a Financial Literacy Program titled Five Keys to Retiring Fearless on 29 April from 5:30PM-6:30PM. https://calendar.piercecountylibrary.org/event/15866258
Wondering if you’ll have enough for retirement? Get answers and expert guidance at our upcoming “5 Keys to Retiring Fearlessly” workshop. Learn how to create reliable income, protect your savings, and plan for the unexpected. Don’t miss out—sign up now and start planning for a fearless future! https://connect.thrivent.com/joe-davis
RSVP here or contact Joe Davis at 360-777-6911 or joe.davis@thrivent.com.
There will be light refreshments!
No products will be sold.
27878-8M R9-25
Gig Harbor Library is hosting Joe Davis who works at Thrivent for a Financial Literacy Program titled Five Keys to Retiring Fearless on 29 April from 5:30PM-6:30PM. https://calendar.piercecountylibrary.org/event/15866258
Wondering if you'll have enough saved for your retirement? Join this dynamic workshop packed with strategies to help secure your financial future. Learn how you can retire with confidence by addressing your biggest financial concerns and sharing practical strategies for a secure future. • Build guaranteed income and protect your savings from market volatility. • Optimize your retirement plan for tax efficiency and long-term growth. • Safeguard your finances and loved ones from life’s “what ifs.”
RSVP here or contact Joe Davis at 360-777-6911 or joe.davis@thrivent.com.
There will be light refreshments!
No products will be sold.
27878-8M R9-25
Late Filing Costs Estate $1.5M—Will Yours Be Next?
The Tax Cuts and Jobs Act established a very favorable federal estate and gift tax regime, and the One Big Beautiful Bill Act made it permanent.
For 2026, the unified federal estate and gift tax exemption is a whopping $15 million, or effectively $30 million for a married couple because each spouse is entitled to a separate exemption.
For 2027 and beyond, the unified exemption amount will be adjusted for inflation.
The portion of your taxable estate that exceeds the federal exemption is subject to federal estate tax at graduated rates up to a top rate of 40 percent. You reach the 40 percent rate quickly, once the value of your estate exceeds the exemption by more than $1 million.
With today’s generous exemption, you may have concluded that you have no federal estate tax worries. It’s possible, in fact, that the whole subject of the federal estate tax may have fallen off your radar.
Not so fast! If you’re married, you need to keep one important thing front of mind to optimize your federal estate and gift tax position: the so-called portable exemption privilege.
If you want to discuss, please call me directly at 360-777-6911 or email joe.davis@thrivent.com.
disclosures:thrivent.com/social
Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional.
If your donating clothes or household goods to charity, there's an IRS trap you need to know about!
In a recent Tax Court case, a taxpayer lost a $6,760 charitable deduction—not because the donations were improper, but because his documentation failed to meet strict technical requirements. The court didn’t question his generosity. It denied the deduction because the receipts and Form 8283 were incomplete.
Here’s the key issue: For non-cash donations over $250, you must obtain a contemporaneous written acknowledgment from the charity. For donations over $500, you must also maintain detailed records showing what you donated, when you acquired the items, and their cost or basis. Form 8283 must be completed accurately, including donation dates and fair market values.
Generic receipts that say “miscellaneous household items” are not enough. And once an audit begins, you cannot fix missing documentation afterward. The deduction is simply lost.
The safest approach is proactive. Before donating, prepare a detailed list of items, including descriptions and estimated values; take photographs; and provide the list to the charity so it can reference the list in its acknowledgment. Keep all supporting records with your tax files.
The bottom line: Good intentions are not sufficient. With charitable deductions, documentation is everything.
If you want to discuss donations of clothing and household goods, please call me directly at 360-777-6911 or email joe.davis@thrivent.com.
disclosures:thrivent.com/social
Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional.
When you retire, you leave behind many things—the daily grind, the commute to work, and maybe even your previous home. However, one thing that will always remain is your tax bill. When you understand how investments are taxed and set strategies accordingly, you can make the right decisions that help keep income taxes in check.
Will Your Taxes Affect Your Retirement? Join me for this event on Friday 6 March at 5pm at the Gig Harbor Library at 4424 Point Fosdick Dr, Gig Harbor, WA 98335, where you will learn strategies to work toward a lower tax bracket in retirement!
There will be light refreshments.
No products will be sold.
Thrivent financial advisors and professionals have general knowledge of the Social Security tenets. For complete details on your situation, contact the Social Security Administration.
Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional.
See thrivent.com/social for important disclosures.
27878-15M R11-20
Plan your finances for the people, causes and community you love | ThriventThis One Mistake Can Make Your QCD Fully Taxable!
After age 70 1/2, you may direct up to $111,000 in 2026 from your traditional IRA to a qualified charity; for married couples, each spouse may give that amount from their own IRA.
The QCD can count toward your RMD once you reach age 73, and the QCD stays out of your adjusted gross income. Lower adjusted gross income can help you avoid higher tax brackets, higher Medicare premiums, and taxation of Social Security benefits.
The trouble arises under the strict no-benefit rule.
You must send a QCD directly to a Section 501(c)(3) charity, not to a donor-advised fund. More important, you must not receive anything of value in return. If you do, the IRS treats the entire distribution as taxable. Even a small benefit can spoil the result. For example, a $250 ticket to a charity dinner will cause a $5,000 QCD to become fully taxable.
Charities must provide written acknowledgements for QCDs of $250 or more. If that acknowledgement lists goods or services received, the tax-free treatment disappears.
The IRS allows limited exceptions. You may receive insubstantial benefits without harming a QCD, such as low-value items or token merchandise, generally capped at $139 in 2026 ($136 in 2025) and subject to percentage limits. Intangible religious benefits from churches also remain acceptable.
Before you authorize a QCD, confirm that you will receive nothing of value beyond these exceptions. Careful planning protects the tax advantages QCDs can provide.
If you want to discuss QCDs, call me directly at 360-777-6911 or email joe.davis@thrivent.com.
disclosures:thrivent.com/social
Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional.
Exciting news! Thrivent has been named to Fortune’s World’s Most Admired Companies list for the first time. Honored to be part of an organization recognized for its innovation, quality of management, financial soundness and commitment to long-term value.
Learn more about this recognition here: https://bit.ly/466lt23
Plan your finances for the people, causes and community you love | ThriventWhen Tax Preparer Fraud Keeps the IRS Audit Door Open Forever!!!!!
You filed your return. You paid what you owed. And after three years passed, you assumed that chapter of your tax life was closed for good. But what if it never really closed at all?
Under a little-known interpretation of the fraud exception to the statute of limitations, misconduct by your tax preparer—not you—can keep an IRS audit window open indefinitely.
In some courts, it doesn’t matter that you never intended to cheat, never knew anything was wrong, and relied entirely on a licensed professional to get it right.
This article walks through a recent case in which the IRS audited a tax return filed in the 1990s (27 years ago), asserting massive tax, penalties, and interest based solely on a preparer’s fraud. It explains why “I didn’t know” failed in Tax Court and before the U.S. Court of Appeals for the Third Circuit; how tax preparer fraud can be imputed to you, the taxpayer; and what you should be doing now to keep decades-old tax
returns from coming back to life.
Contact me at 360-777-6911 or email joe.davis@thrivent.com or schedule a meeting for the article and learn how to potentially avoid or minimize this pitfall.
Takeaways
You are legally responsible for every number on your return, even if a preparer enters the data. Under Allen and Murrin, “I didn’t know” is not a defense to the unlimited statute of limitations for fraud in Tax Court and the Third Circuit. The three‑year statute of limitations is effectively a privilege that can be lost when a return is deemed fraudulent. BASR draws a different line, limiting the fraud exception when only the preparer—not the taxpayer—intended to evade tax. This is why forum and appellate circuit selection are now central strategic decisions in fraud‑related
disputes involving the statute of limitations. Until the Supreme Court resolves this conflict, taxpayers and advisors must assume that in some courts, “forever”
in Section 6501(c)(1) really does mean forever.
disclosures:thrivent.com/social
Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional.
When you retire, you leave behind many things—the daily grind, the commute to work, and maybe even your previous home. However, one thing that will always remain is your tax bill. When you understand how investments are taxed and set strategies accordingly, you can make the right decisions that help keep income taxes in check.
Will Your Taxes Affect Your Retirement? Join me for this event on Friday 30 Jan at 415pm at the Gig Harbor Library at 4424 Point Fosdick Dr, Gig Harbor, WA 98335, where you will learn strategies to work toward a lower tax bracket in retirement!
There will be light refreshments.
No products will be sold.
Thrivent financial advisors and professionals have general knowledge of the Social Security tenets. For complete details on your situation, contact the Social Security Administration.
Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional.
See thrivent.com/social for important disclosures.
27878-15M R11-20
Thrivent Social Media Privacy Policy, Guidelines, Disclosures & DisclaimersWhy Serious Landlords Rely on the 1031 Exchange.
If you own rental property and want to become a big-time landlord, use the Section 1031 exchange to
-sell appreciated properties, pay no federal income taxes, and reinvest all proceeds;
-trade up into larger or better‑performing properties, such as moving from one‑door rentals into multifamily rentals;
-avoid taxes during your lifetime; and
-bequeath the property at death to your heirs, who receive a step-up in basis to fair market value.
Critical Step 1
To get your Section 1031 exchange on track, engage a qualified 1031 real estate exchange intermediary.
You need to do this first, before starting down the sale or purchase path with your property, even though the intermediary will not start working on your case until you buy or sell. But no worries here: your intermediary will communicate what you need to do.
Choose your intermediary firm with the same care you would for investing significant funds. Your tax and financial advisors likely can give you guidance
Contact me at 360-777-6911 or email joe.davis@thrivent.com for additional steps.
disclosures:thrivent.com/social
Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional.
Thrivent Social Media Privacy Policy, Guidelines, Disclosures & DisclaimersYour 2025 Year-End Tax Planning Guide for Tax-Saving Tips!
As we approach the end of 2025, there’s still time to take action and make a real difference in your tax outcome for the year. With thoughtful planning and a few strategic steps, you can reduce your tax bill, strengthen your retirement savings, and position your finances for a better 2026. Below are some year-end moves to consider before December 31. Each one is practical, IRS-approved, and designed to help you keep more of what you’ve earned.
Strengthen Your Business Deductions before December 31
1. Prepay Expenses Under the IRS Safe Harbor
If you’re on the cash basis, you can prepay qualifying expenses up to 12 months in advance and deduct them this year. That includes office rent, equipment leases, and insurance premiums. For example, if your monthly office rent is $3,000, prepaying $36,000 on December 31 to cover your 2026 rent gives you a $36,000 deduction in 2025—and it provides the landlord with the income when he wants it, in 2026. Be sure to mail the funds on December 31 so they arrive in January 2026, and keep documentation, such as the USPS tracking number.
2. Hold Off on Year-End Billing
A simple yet effective move for cash-basis businesses: delay billing clients until January. Since you don’t recognize income until payment is received, postponing invoices can shift taxable income into 2026.
3. Purchase Needed Equipment
If you’ve been planning to buy office furniture, computers, or machinery, doing it now can provide a full deduction through 100 percent bonus depreciation or Section 179 expensing—as long as you place the equipment in service before December 31.
4. Use Business Credit Cards Wisely
For Schedule C filers, the deduction occurs on the date of the charge, not when you pay the bill. That means charges made in December are deductible this year. Corporations can do the same when employees are using a corporate card.
5. Document and Claim Every Legitimate Deduction
Don’t avoid deductions because you think they might raise red flags. If they’re legitimate and supported by records, you’re entitled to them. If deductions exceed your income, that loss may create a net operating loss (NOL) that carries forward to offset future profits.
6. Review Qualified Improvement Property
If you improved the interior of your business or one of your commercial rental properties this year, those costs may qualify for immediate expensing rather than 39-year depreciation. To take the deduction for 2025, you must place the improvement in service by December 31.
disclosures:thrivent.com/social
Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional.
Thrivent Social Media Privacy Policy, Guidelines, Disclosures & DisclaimersLearn How to Beat 2025 Estimated Tax Penalties Instantly, Today!
Here’s an important tax planning strategy that can save you thousands in penalties if you’ve missed estimated tax payments for 2025.
The Penalty Problem
When you don’t make your 2025 estimated tax payments on time, the IRS charges a non-deductible 7 percent penalty that compounds daily. Because penalties are not deductible, they are considerably more costly than deductible interest.
Simply writing a check today won’t erase the penalties. It only prevents them from growing further. But there is a powerful way to make them disappear entirely.
The One Perfect Solution
By using a retirement account with 60-day rollover provisions, you can eliminate estimated tax penalties instantly. Here’s how:
• Withdraw funds from your IRA, 401(k), or other eligible plan, and direct the custodian to withhold federal income tax.
• Repay the full amount into the retirement account within 60 days using other funds.
The IRS treats the withheld taxes as if they were made evenly across all four estimated tax deadlines. And because you repaid the account within 60 days, the withdrawal is not taxable, and no penalty applies.
Other Options and Pitfalls
If you are age 73 or over, you can use withholding taxes from required minimum distributions (RMDs) to cover both your RMD and your estimated tax needs.
Don’t use a W-2 bonus. It triggers payroll taxes and can reduce your Section 199A deduction—likely more costly (and perhaps far more costly) than the penalty itself.
disclosures:thrivent.com/social
Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional.
Thrivent Social Media Privacy Policy, Guidelines, Disclosures & DisclaimersTAX SAVINGS TIPS!
OBBBA Restores and Creates New 100 Percent Deductions for You Now.
If you plan to buy equipment, furniture, computers, or other personal property for your business, the recently enacted One Big Beautiful Bill Act (OBBBA) delivers great news. You can now deduct the full cost of such property in a single year—without limit.
For manufacturers, the OBBBA goes even further by creating a new 100 percent deduction for factories and other production-related real estate.
disclosures:thrivent.com/social
Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional.
Thrivent Social Media Privacy Policy, Guidelines, Disclosures & DisclaimersDo you have a personal vehicle?
Thanks to the One Big Beautiful Bill Act (OBBBA), you may be eligible for a valuable “no new cash outlay” tax deduction beginning in 2025.
Here’s how it works: If you convert a personal-use vehicle to business use, the law treats it as placed in service on the conversion date. Thanks to OBBBA’s reinstatement of 100 percent bonus depreciation, you may deduct up to 100 percent of the vehicle’s fair market value—as long as you don’t opt out of bonus depreciation.
For example, if your converted vehicle is worth $31,000 and you use it 70 percent for business, you could deduct $21,700 on your 2025 return.
Heavy SUVs, pickups, and vans with a gross vehicle weight rating (GVWR) over 6,000 pounds qualify for full bonus depreciation. Smaller vehicles are subject to “luxury auto” limits—but even those can allow up to $20,200 in first-year deductions.
A few rules to know:
• You must use the lower of your vehicle’s fair market value or adjusted basis at the time of conversion to business use.
• Section 179 expensing is not allowed for converted assets, but bonus depreciation is automatically applied unless you actively opt out.
• All assets in the same depreciation class are treated the same for bonus depreciation—you’re in or out for the entire group.
If you later sell the vehicle, your basis for calculating gains or losses changes depending on whether it’s a gain or loss.
This is a powerful way to deduct the cost of an existing asset without spending new money.
If you want to discuss the conversion of a personal vehicle to business use, please call me on my direct line at 360-777-6911.
disclosures:thrivent.com/social
Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional.
Plan your finances for the people, causes and community you love | ThriventHave you ever heard of the Mega backdoor Roth!
If you are a business owner with no employees and prefer Roth-style retirement savings, you may want to consider the mega backdoor Roth strategy. This powerful tool allows you to contribute significantly more to a Roth account than the standard Roth IRA or even the regular backdoor Roth route—up to $70,000, or $77,500 if you’re age 50 or older.
Compare that to the regular backdoor Roth limit of $7,000 ($8,000 with the age 50-plus catch-up), and you’ll see why the “mega” title fits.
If you are self-employed, own a corporation, or are a partner in a partnership with no full-time employees, the mega backdoor Roth could be a high-impact retirement strategy.
If you want to discuss the mega backdoor Roth strategy, please call me on my direct line at 360-777-6911.
disclosures:thrivent.com/social
Wondering if you should add a fixed annuity to your retirement strategy? Consider these possibilities:
👉 You don’t pay taxes on your earnings until you withdraw your money, which helps your money accumulate even faster.
👉 It could supplement other sources of guaranteed income, like Social Security or a pension
👉 It could provide a stable and predictable income source to cover your essential expenses in retirement.
To learn more about fixed annuities: https://bit.ly/4kBW6tN
June 2025 Market Update: Confidence reboundsThe mixed economic data of May highlighted our economy is still slowing. Read Thrivent Asset Management's thoughts on how our outlook has changed in the June market update.