Solo-Biz Deep Dive | The Hardest $40,000 He Ever MadeI am very excited to have been featured on a recent issue of The Solo Operator, a weekly newsletter for business owners and hopefuls ran by my friend Lucas Wollschlager.
We went into some of the nitty-gritty of building a (now) six-figure business in under two years, including:
-The $2M near-miss prospect who never became a client, but totally reshaped my marketing approach.
-The single boundary that freed up hundreds of hours of time for deeper planning and better client wins.
-Real-world impact of values-aligned investing and how advocacy beats boycott.
Check the article out here: https://thesolooperator.substack.com/p/solo-biz-deep-dive-the-hardest-40000
If you're a Christian business owner or solopreneur making $150k+/year and want help navigating your financial decisions and taxes, shoot me a connection request or message.
--------
See thrivent.com/social for disclosures.
This month, while the rest of the world celebrates pride, choose instead to celebrate the month of the Sacred Heart of Jesus.
Christians everywhere have been honoring Jesus' Sacred Heart in the month of June for over 150 years, when Pope Pius IX formally established the feast in 1856.
Instead of putting one of the 7 Deadly Sins front and center, let's be grateful for the humility of Christ, who humbled himself to share in our humanity.
"Behold this Heart which has so loved men that it has spared nothing, even to exhausting and consuming itself, in order to testify its love."
There are two major pharmacies you need to know about, that are making huge profits off the mail-order abortion industry right now. Medication abortions now account for 60% of all abortions in the US.
A lot of people hold stock in CVS and Walgreens in their 401ks at work or in their standard S&P500 investment accounts.
Many people don't understand that your money can be your voice, and that you are actually a part-owner of the companies you're invested in, which makes you invested in their success AND in the products they sell (for good or evil).
Some people automatically assume that if a company is big enough for everyone to recognize their name, they must operate pretty ethically.
But that is just not the case.
Leave a comment or DM me if you want to know more about how our screeners work and how we're investing in ethical, pro-life, pro-family companies and funds.
----------
sources: https://www.reuters.com/business/healthcare-pharmaceuticals/mail-order-dominates-us-abortion-pill-dispensing-2026-04-13/
https://www.npr.org/2024/03/01/1235265078/abortion-pill-cvs-walgreens-mifepristone
Book here: https://connect.thrivent.com/jacob-andersen
See thrivent.com/social for disclosures.
28-year old real estate agent making $500k/year
Here's how we're saving him and his wife $18k in taxes for 2026. You are going to want to save this post if you have any 1099 income or contracting work.
Last year they made good money but didn't have tax saving measures in place and ended up owing close to $100k.
Switching to an S-Corp provided some savings on self-employment tax but they needed something more.
They had most basic financial needs taken care of already (emergency fund, maxing backdoor Roths, no debt other than the mortgage, etc).
First step was opening and maxing an HSA. This is such an underrated account with triple tax savings and they spend a lot on maintaining their health. Now they can put in $8750/year and use it for medical bills they were already paying for from checking. 2026 tax savings on this is about $3,300.
Also thinking about opening a solo 401k to defer some income out of the 32% tax bracket. We can convert to Roth in future years when income drops or he has more deductions. ~$7,000 off this year's taxes.
Opened an Idaho 529 plan and contributed $12,000 for future kids' college. Most people know it can be used for college but don't know that it can also be used for K-12 costs or trade school. In the state of Idaho you can deduct up to $12,000 which will save them close to $700 in state taxes this year.
Augusta Rule. This rule is heavily audited so you just have to do it correctly. Your S-Corp can rent your primary residence from you, the S-Corp can deduct the expense and the personal income is tax-free. Tax savings on this could be $7k+ for them depending on what comparable properties/rentals are in the area.
$18k in savings/deferrals, the tax savings will continue to compound over time and feel like this is just the tip of the iceberg for them.
Reach out if you want to connect or book here: https://book.apps.thrivent.com/client/jacob.andersen
-----
see thrivent.com/social for important disclosures.
Hypothetical example is for illustrative purposes. May not be representative of actual results. Thrivent and its financial advisors do not provide legal, accounting or tax advice. Consult your attorney or tax professional.
If you are
Pro-Life
Pro-Family
Pro-God
But you don't know what companies your IRA is invested in...
There's probably a lot more good your money could be doing.
We are helping bring positive change to our culture through Biblically-Responsible Investing.
This is the most important thing I do for people 🙂
DM me for resources.
See thrivent.com/social for disclosures.
53-year old prospect with $250k walks into my office dejected.
He had just attended a retirement seminar at work.
They told him if he didn't have $1-2MM he'd never be able to retire.
Honestly, I couldn't care less what his 401k balance was.
I asked him, "What kind of life do you want to live in retirement?"
He was fine living on $60k/year.
Great, we can work with that.
We were able to utilize our faith based investments, project out Social Security, and make an ongoing plan for taxes and Roth conversions, all within the first two meetings.
If he wanted $150k/year it would've been a different conversation.
I kid you not- when this client walked out of my office after we set everything up, it was like a weight from all the fear-mongering had been lifted.
Your desired retirement income is a much more important metric than your 401k balance or some arbitrary "retirement number."
--------
Important disclosures: thrivent.com/social
Hypothetical example is for illustrative purposes. May not be representative of actual results.
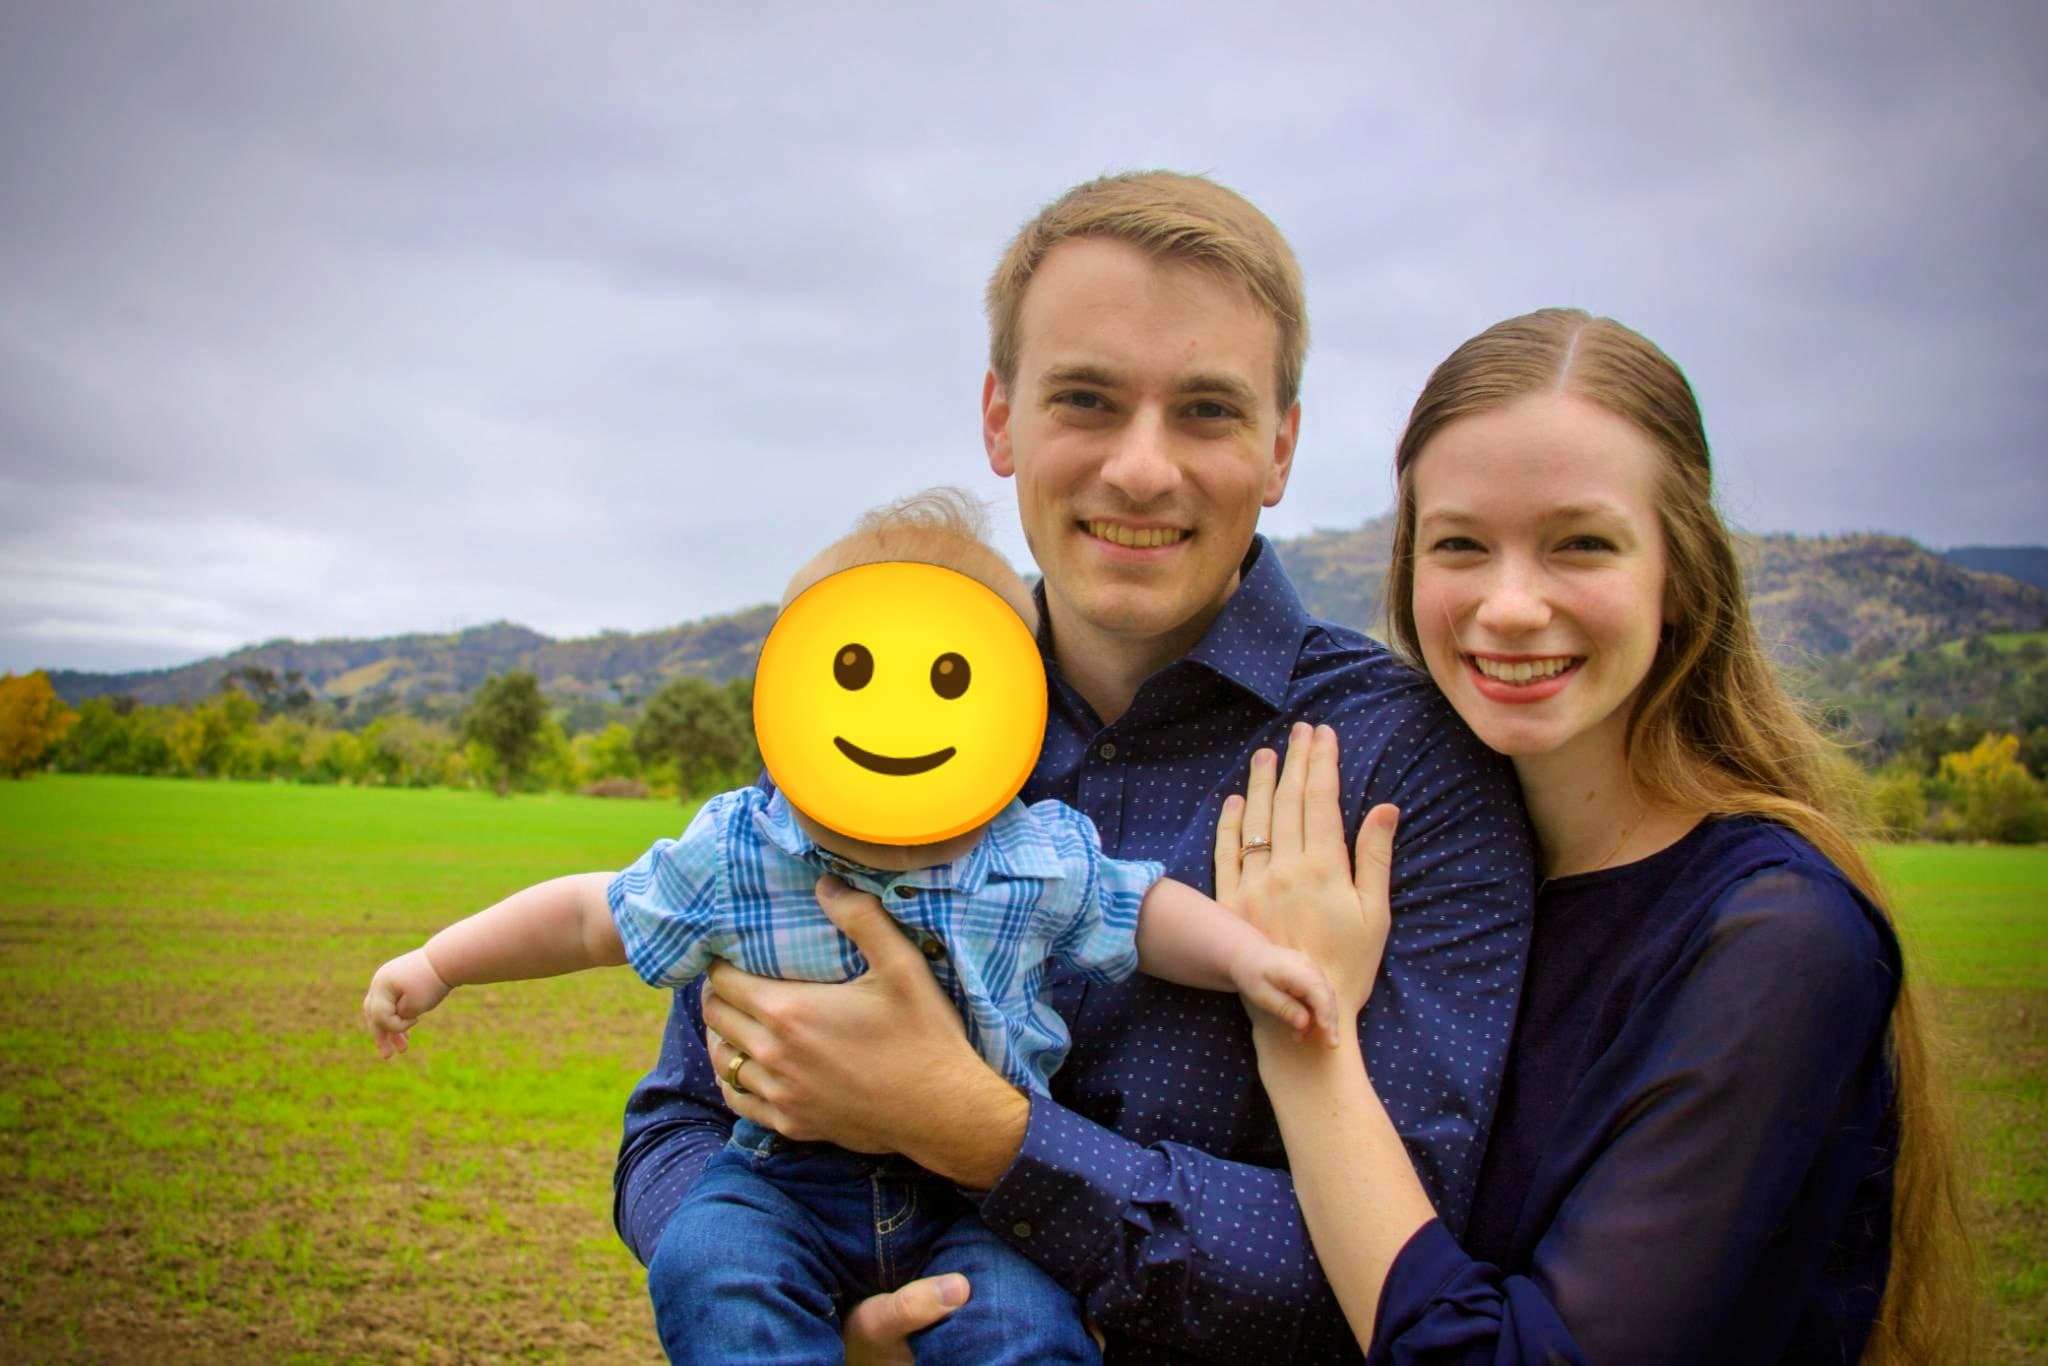
We've been married for 664 days and have only spent one night apart.
When I travel for business, I do it in a day trip or we all go.
My dad used to leave for weeks at a time to the Middle East. Sometimes he'd bring back gifts. I remember just wishing I could've spent more time with HIM. Wishing that he was present.
Not everyone has the flexibility to bring their families along. It can be impractical.
It's just an area we've been intentional in because I want to be as present as possible to Dominic and Elise.
We want to work together, travel together, pray together. We're a FAMILY.
I received multiple texts last week from people who just did their taxes, asking what they signed up for when they checked the little box saying they wanted Trump Accounts for their kids.
Best resource is here and it's actually very digestible for laypeople: https://trumpaccounts.gov/
If you want the short version:
-There are two ways to open the account- on your tax return or IRS form 4547 which I can link in the comments
-The most unique thing about the program is that the government contributes $1,000 to your child's account if they were born between 2025 and 2028.
-Investment options are VERY limited. It is sounding like the accounts will just be invested in an S&P 500 index fund.
-When they turn 18, the ownership of the account changes from you to the child, and they can use the funds to pay for a first home, a new business, or college.
Overall, I love that it is a pro-family policy. It incentivizes people to have more kids which is great.
BUT don't ask me how I feel about what this does to our federal deficit ;)
Hit me with any questions you have and feel free to save this post if you want to come back to it for info later.
PS, I don't use AI for any of my writing- but Chat makes pretty darn-good animations ;)
See thrivent.com/social for disclosures.
21 yrs old: Met Elise, working as a bank teller. Cafeteria food in college.
22 yrs old: Got engaged, business lending department, paid off all debt, living with 5 other dudes makes for cheap rent 😎 PB&Js
23 yrs old: Married at 23 and 20. Moved to Boise, took 4 exams, opened up shop with 0 clients and $0 guaranteed revenue. Chicken and rice
24 yrs old: Onboarded 30 clients, 13% raise from my last W-2 job. Homemade dinners and Chick Fil-A
25 yrs old: On pace to onboard 65 clients, 200% raise from 2025, already hit all 2026 bonuses, last 12M revenue crossed six figures. Homemade dinners, Chick Fil-A and occasional tri tip on the smoker.
I'm really excited to see how 2026 shapes out.
My goal in business is to show Jesus and deliver massive value to every single person I work with.
These numbers mean I can take Elise out for nice dinners every weekend like she deserves, spend more time with my 8-month old, spend more time at church and give more radically.
Just now starting to see the grind from 2022-2024 really pay off 🔥
Thrivent.com/social for disclosures.
Client's mom died last week.
She had been on hospice for the last two months. They knew it was coming. They're in their 60s. It hurts no matter what age you are.
We sent them a grief care package. I let them know I was praying for them. We're helping them figure out immediate needs and the inheritance.
When I was a kid, I wanted to be a priest- a big part of that was because I wanted to be close to people in life's greatest and lowest moments. Births, deaths, graduations, marriages, baptisms.
Now, I get to do that in a totally different way than how I originally envisioned. God had such a good, different plan.
People think we're crazy
Got married at 24 and 21
Paid off all debt except the mortgage
Got rid of the TV
Sometimes God calls us to jump before we've tested the parachute 🤷♂️
Distraction Culture:
Ignoring others around you
8 hours of screen time
Constant comparison
Christian Culture:
Eating dinner as a family
Listening intently when others speak
Putting devices away to show we care
You can only pick one.
Call us old school
We don't own a TV
We haven't exchanged our brains for AI
We still read physical books
People think we're living in the past
I think we're living the DREAM
They told us to wait to have kids.
They told us to move in together before marriage.
They told us we needed dual income.
The world will always prioritize convenience over doing difficult things.
But we don't belong to the world. We belong to Christ.
Doing hard things for Jesus will always be worth it.
Plan your finances for the people, causes and community you love | ThriventWhat Is Biblically Responsible Investing, and Why Is It Important?
When I first became a financial advisor, I had no idea that there were intentional ways for Christians to invest. I knew that some companies profited from pretty shady practices, but didn't think investing in them was "that bad."
It wasn't until I met with the CEO of one of the largest providers of faith-based investments in the world that my mind began to change. He directed me to a 2021 document titled "Socially Responsible Investing Guidelines" that flipped my world on its head.
In that document, from the United States Conference of Catholic Bishops, there is guidance on how a Christian can approach their investment portfolio, with three main pillars illuminating the way.
The first pillar is to Avoid Doing Harm.
This means avoiding investments in companies that are supporting anti-Christian agendas, or are not respecting human dignity or the sanctity of life. However, many people are unknowingly invested in many such companies.
The second pillar is Actively Working For Change.
Investors are in a unique position to advocate for positive change. Publicly-traded companies care greatly about their shareholders and want them to be happy. So when a Christian is invested in a company, they can use that ownership to vote for good board members and good company policies.
Just this past summer, two major Fortune-500 companies reversed their decisions to sell abortion pills on their store shelves, due to advocation from faith-based investing groups. That is just one example of how shareholders can impact the companies they're invested in.
The third pillar is to Promote The Common Good.
This pillar is all about doing what is best for the common good, and society as a whole, rather than just thinking about what is best for our wallets. For example, investing in community housing or low-income real estate might not have the best returns on investment, but they may be a way to brighten and improve the lives of many people.
By living according to this pillar, we can keep the right perspective and ensure that God and our fellow man comes first, not returns. No amount of money you could earn would be worth taking advantage of another person.
------
It can be difficult to begin implementing these pillars into our daily lives and into our portfolios. But it is absolutely worth looking into. After my wife and I read this document, we began to re-evaluate our financial and investment decisions through the lens of our faith, rather than through the perspective of what returns we could get.
I am so grateful to have a faith where we have guidance like this, and an ability to invest our money in a way that glorifies God.
If you would like to talk more about what values-first financial planning looks like, reach out to me at jacob.andersen@thrivent.com
I'd love to hear from you.
God bless!
Biblically Responsible Investment model portfolios may forgo certain investment opportunities to achieve their philosophies and, as a result, these model portfolios could underperform the broader investment market and other investment opportunities. Further, Biblically Responsible Investment models have limited performance history. See thrivent.com/social for important disclosures.
I work with Christian families in Idaho who want to steward their money well - without compromising their beliefs or overpaying taxes.
If you want to talk through what that looks like — no pitch, just real answers — shoot me a message.
5 Efficient Ways You Could Save On Your Taxes
We’ve all been there. April rolls around, and your CPA sends you a bill higher than you ever would’ve thought possible. The IRS got you again. And that thought goes through your mind, like it does every April… isn’t there anything I can do? Do I really have to pay this much in taxes?
Well, my friend, I have some ideas for you- five of them in fact. These ideas and strategies have the potential to save you boatloads of money in taxes over the years, keeping more money in your pocket… where it belongs! If you’d like to know what kinds of powerful ideas I'm talking about, keep reading… but first, I’d like to introduce myself!
My name is Jacob Andersen, and I’m a financial advisor here in Nampa, ID. My wife, Elise, and I moved here about a year ago, after spending one too many snowy winters in blustery North Dakota. I have a little over three years of experience in financial services- which means I might be the same age as one of your grandchildren ;). However, I have several licenses, certificates, and degrees to prove that I know my stuff when it comes to finance. In my time working at a Christian Fortune 500 organization, I have helped many people just like you make more informed decisions with their money. Namely, I help people prepare for retirement, pay less taxes, and take precautions to ensure that they don’t outlive their money.
That’s why I’d love it if you: finished reading this post to find out where you can save on taxes, and then: call my number at the bottom of the last page to schedule your own personal consultation, which is free. Some would say the advice is worth what you pay for, but others have found immense amounts of value from even just a 30-45 minute introductory meeting.
So, without further ado, here are five efficient (and legal) ways you could save on your taxes.
1. Municipal Bonds
Most people have heard of municipal bonds, but in case you haven’t, here’s what they are: Imagine that the mayor of the town you live in wanted to build a new bridge or hospital. They can ask investors (like you!) to help fund it, and in return, they’d make interest payments (usually 4 or 5%) to you every month. Sounds like a decent deal, right? Well here’s the real kicker: the interest payments come to you, tax-free! Sometimes they are tax-free at the federal and the state levels. Pretty sweet!
2. Roth Conversions
The second great way you could save is by implementing Roth conversions. A Roth conversion is simply taking money from an IRA or 401k, and putting it into a Roth account. While this strategy may not save on taxes immediately, it can make a huge difference in the long run. That’s because money in a Roth account grows completely tax-free and is never taxed again.
3. Fixed Annuities
The third way to potentially save on your taxes is one you can implement immediately- a fixed annuity. While these accounts do “tie up” a portion of your money for a set amount of time, Thrivent’s fixed annuities have no upfront costs whatsoever and can be a great tool to save on taxes. The benefit of a fixed annuity is that it is tax-deferred, meaning the account can grow over time without you having to pay any taxes on it! That makes fixed annuities different from savings accounts and CD’s, where you pay taxes every year on the interest. Fixed annuities can also be a great tool for guaranteed income in retirement at no cost to you.
4. Charitable Giving
The fourth way you could save on taxes is through charitable giving. As mentioned above, the company I work for is Christian, and generosity is a very important part of what we do for our clients. Giving your money to qualified causes (like your church or favorite non-profit) could save you a lot on taxes. When you’re 70, you could implement a strategy like Qualified Charitable Distributions (QCD’s) out of an IRA. Before then, you could open a Donor-Advised Fund or donate highly appreciated assets and receive tax benefits in return.
5. Timing Withdrawals Correctly
This is possibly the most important of the five strategies, because it not only affects your taxes, it could affect your Medicare premiums as well! Timing your withdrawals from Roth accounts, IRAs, and 401ks is no simple feat. It takes planning, not only for today, but for the years to come. The longer a person waits, the less options they typically have for controlling their income. That's why it’s usually better to start earlier when you have more choices.
---------------------------------------------------------------------------------------------------------------------
So that’s the list! There are five ways you could legally save on your taxes. Not all of them will be for everyone, and that’s okay. Each person has individual needs! That’s why I’m here to help. Our team has a combined 35 years of experience helping people just like you, and we’d love it if we were able to help you next :)
To discuss these strategies more in depth, and hear about what other strategies we’d recommend, schedule your free meeting with me at 208-504-2969, or shoot me an email at Jacob.Andersen@Thrivent.com. I’d love to tell you about the additional ideas we have and hear more about your particular needs.
Again, my number is 208-504-2969, and our team is located in downtown Nampa. You can call or email me to set up a time together.
Here are some Frequently Asked Questions people ask me:
Q. How long will the meeting be?
A. I like to keep meetings to about 45 minutes. It gives us enough time to get to know each other without taking up too much of each other’s time.
Q. What should I bring?
A. Feel free to bring any relevant statements or documents. Or just bring yourself! The meeting will be very laid back and I will walk you through everything.
Q. What if I already have a financial advisor?
A. That’s perfectly okay! Many of my current clients had financial advisors previously. It never hurts to have a second look at your current accounts.
God bless and take care!
Jacob Andersen
----------
For important disclosures, see thrivent.com/social. Thrivent and its financial advisors and professionals do not provide legal, accounting, or tax advice. Consult your attorney or tax professional.