Insights
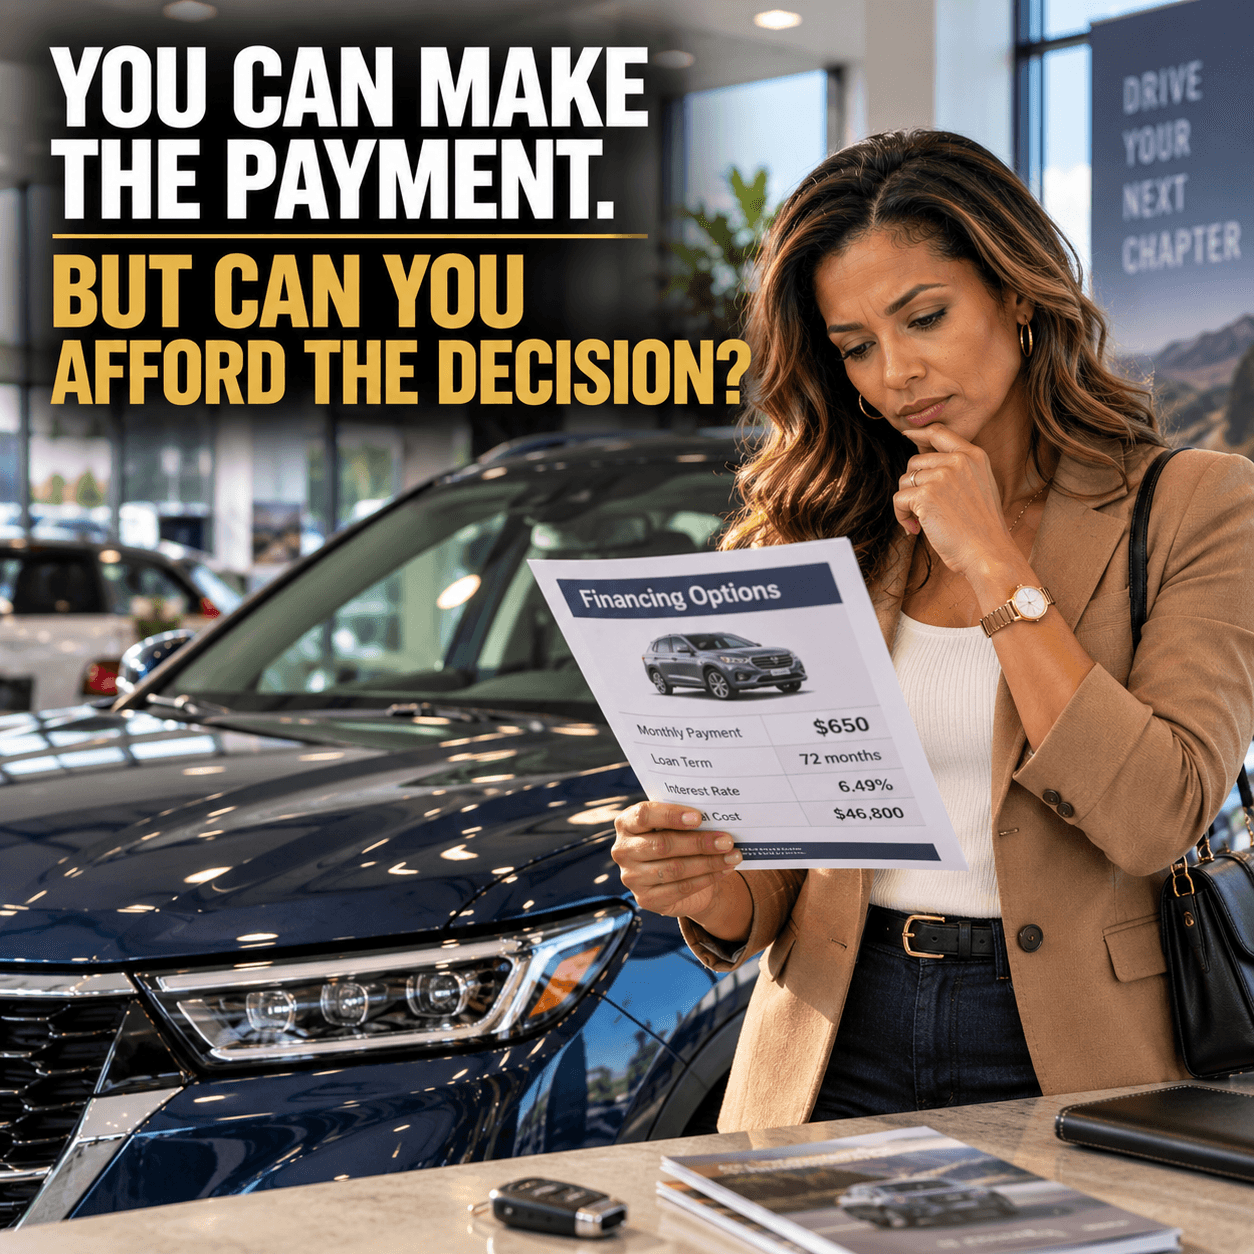
#FinancialFreedomFriday
JUST BECAUSE YOU CAN MAKE THE PAYMENT DOESN'T MEAN YOU CAN AFFORD IT.
Read that again.
Somewhere along the way, we stopped asking, "How much does it cost?" and started asking, "How much is the monthly payment?"
That new car? Only $650 a month.
That furniture? Just $150 a month.
That vacation? Four easy payments.
That new phone? Add another $40 to the bill.
Individually, none of those payments may seem overwhelming.
But here's what we often overlook:
Every payment you commit to today is money you've already spoken for tomorrow.
And tomorrow has its own responsibilities.
Retirement contributions.
Emergency savings.
Helping your children.
Protecting your family.
Building the legacy you want to leave.
I'm not suggesting you shouldn't enjoy the things you've worked hard to afford.
I'm asking a different question:
Are your purchases supporting the life you want, or are your payments limiting the choices you'll have?
Because there's a significant difference between having enough income to qualify for financing and having enough room in your financial plan to take on the obligation.
Financial planning isn't about telling you what you can't have.
It's about helping you understand the trade-offs so you can make informed decisions about what matters most.
📌 Don't confuse purchasing power with financial capacity.
The lender may tell you what you qualify to borrow.
Your financial plan should help you determine what makes sense to borrow.
📩 Before you take on another financial obligation, let's talk about how that decision fits into your bigger picture.
DM me. Let's build a strategy that considers both the life you're living today and the future you're preparing for.
#FinancialFreedomFriday #FinancialPlanning #FinancialClarity #SmartMoneyDecisions #FaithAndFinance
📌 See thrivent.com/social for important disclosures.

#ThriveThursday | Your Life Changed. Did Your Beneficiaries?
You got married.
You got divorced.
You welcomed a new child or grandchild.
You lost someone you love.
Or maybe it's simply been years since you last reviewed your benefits.
Here's a question: Who gets your money if something happens to you?
During open enrollment, we spend time reviewing health insurance, retirement contributions, and other benefits.
But there's one important detail that deserves just as much attention.
Your beneficiaries.
The person you named five, ten, or even twenty years ago may no longer be the person you would choose today.
And here's something many people don't realize:
A beneficiary designation can determine who receives certain financial assets, even when your will says something different.
Think about that.
You can spend your entire working life saving, investing, and preparing for the future.
But if you haven't reviewed your beneficiary designations, those assets may not pass to the people you currently intend.
That's why financial planning isn't just about how much you accumulate.
It's also about making sure your intentions are reflected in your financial arrangements.
This open enrollment season, take a few extra minutes.
Review your beneficiaries.
Confirm the information is accurate.
Understand how your designations fit into your overall estate plan.
Because the financial decisions you make today can affect the people you love long after you're gone.
If you're unsure whether your beneficiary designations align with your financial goals, let's review them together.
📌 See thrivent.com/social for important disclosures.
#ThriveThursday #OpenEnrollment #BeneficiaryReview #FinancialPlanning

#WisdomWednesday
Your life may have changed. But did your beneficiaries?
It's open enrollment season, and you're reviewing your benefits.
Health insurance? Check.
Dental and vision? Check.
Retirement contributions? Check.
Life insurance? Check.
But here's a question that deserves just as much attention:
"When was the last time I checked who gets the money?"
Think about how much life can change in just a few years.
You get married.
You have a child.
You get divorced.
You lose a loved one.
Your family circumstances change.
But the beneficiary designation you completed years ago may still be sitting there, unchanged.
And here's something many people don't realize:
Your will doesn't necessarily determine who receives the money from accounts with valid beneficiary designations.
Depending on the account, plan rules, and applicable law, those designations can determine where the assets go.
That means someone you named 10 or 15 years ago could still be listed today.
Open enrollment is a great reminder to review your life insurance and retirement account beneficiaries, including any contingent beneficiaries.
Make sure your designations reflect your current intentions and understand any spousal-consent requirements.
Because after you're gone, it may be too late to correct an outdated designation.
Wisdom isn't just deciding what happens to your money while you're here. It's taking the time to review who you've designated to receive it when you're not.
#WisdomWednesday #OpenEnrollment #BeneficiaryReview #FinancialPlanning #LegacyPlanning #FinancialWisdom
📌 See thrivent.com/social for important disclosures.

#TruthfulTuesday — Is Your Money Working as Hard as You Are?
You work hard.
You put in the hours.
You make sacrifices.
You earn your paycheck.
But here's a question worth asking:
Is the money you're earning actually working toward the things that matter most to you?
Think about it.
You can work 40, 50, or even 60 hours a week, earn a good income, and still find yourself wondering where all the money went.
Not necessarily because you aren't making enough.
But because you haven't given every dollar a purpose.
Are you building savings?
Are you preparing for retirement?
Are you protecting what you've worked to build?
Are you making financial decisions that reflect your values?
Or are you simply earning, spending, and repeating the cycle?
Sometimes, when we begin examining those questions, I hear:
"I didn't think about that."
And that's why financial planning matters.
Truth: Working hard for your money is important. Having a plan for what your money should accomplish is just as important.
Your income tells you what you've earned.
Your financial plan helps you determine what you're working toward.
Because at the end of the day, the goal isn't simply to make more money. It's to make more intentional decisions with the money you make.
You've worked hard to earn it.
Let's make sure you have a plan for it.
#TruthfulTuesday #IDidntThinkAboutThat #FinancialPlanning #MoneyWithPurpose #FinancialWisdom
📌 See thrivent.com/social for important disclosures.

#MoneyMovesMonday
Your retirement date is NOT your retirement income strategy.
“I want to retire at 62.”
“I'm counting down to 65.”
“Just five more years, and I'm done!”
Those are dates.
But knowing when you want to retire doesn't necessarily mean you've determined how you'll financially support the lifestyle you envision.
Here's a question worth asking:
When your employment income stops, what sources of income will you rely on?
Social Security?
A pension?
Withdrawals from retirement accounts?
Other sources of income?
And perhaps more importantly:
How will those sources work together to help cover your living expenses, taxes, healthcare costs, and unexpected needs?
You may know exactly WHEN you want to retire.
But have you considered HOW your retirement income will support your financial needs and goals?
There's a difference between accumulating money for retirement and developing a strategy for using those resources during retirement.
This week's money move:
Stop focusing exclusively on your retirement date.
Start examining your retirement income strategy.
Consider where your income may come from, how much you may need, and how your different financial resources can work together throughout retirement.
Because retirement planning isn't just about how much you've accumulated.
It's also about understanding how you'll turn those resources into income to support the life you envision.
📩 If retirement is on your horizon, let's talk about developing a retirement income strategy aligned with your goals.
#MoneyMovesMonday #RetirementPlanning #RetirementIncome #FinancialPlanning #PurposeDrivenPlanning #Thrivent
📌 See thrivent.com/social for important disclosures.

#FinancialFreedomFriday
THE CHEAPEST OPTION ISN'T ALWAYS THE LEAST EXPENSIVE.
It's open enrollment season, and millions of employees are reviewing their benefits.
And let's be clear about something.
The first number most people look at is how much will come out of their paycheck.
I get it. Nobody wants to see more money deducted from their earnings.
But here's the question:
Are you making a financial decision based on what costs less today, or what makes sense for your overall financial situation?
That health insurance plan with the lower premium may come with a higher deductible.
That coverage you declined because you thought you didn't need it may become important when life takes an unexpected turn.
That disability insurance you overlooked may be worth evaluating when you consider how much your family depends on your income.
And that HSA option? Have you considered how it might fit into your broader financial strategy?
Here's what I want you to understand:
Saving money on your paycheck doesn't automatically mean you're making the best financial decision.
Sometimes the lowest immediate cost can expose you to expenses you haven't considered.
And sometimes paying more doesn't necessarily mean you're getting something better.
That's why we PLAN instead of GUESS.
Financial planning is about understanding the trade-offs, evaluating your options, and making informed decisions that reflect your circumstances.
📌 Don't just ask, "What will this cost me today?"
Ask, "What could this decision mean for my financial future?"
Open enrollment is an opportunity to review more than your benefits. It's an opportunity to examine how those benefits fit into your overall financial plan.
📩 DM me before you finalize your elections. Let's discuss how your workplace benefits fit into the bigger financial picture.
#FinancialFreedomFriday #OpenEnrollment #FinancialPlanning #FinancialClarity #FaithAndFinance
📌 See thrivent.com/social for important disclosures.

#ThriveThursday | Your Benefits Are Only Part of the Picture
It's open enrollment season!
You've reviewed your health insurance.
You've selected your dental and vision coverage.
You've decided how much to contribute to your 401(k).
You clicked SUBMIT.
You're done, right?
Maybe with open enrollment. But what about your financial planning?
Here's something worth considering:
Your employer provides benefits.
But who's making sure those benefits work with everything else you're trying to accomplish?
Does your life insurance coverage reflect your family's actual needs?
Are your retirement contributions aligned with your goals?
Are you taking advantage of benefits you're already paying for?
Could an HSA play a role in your longer-term financial strategy?
And what happens to your financial strategy if you change employers?
These are questions that go beyond simply checking boxes.
Your employer's benefits package was designed for employees. Your financial plan should be designed for YOU.
Open enrollment is an opportunity to review more than what your employer offers.
It's an opportunity to ask whether everything is working together.
Because having benefits and having a coordinated financial strategy are not necessarily the same thing.
Don't just enroll. Evaluate.
If you'd like to take a closer look at how your workplace benefits fit into your financial goals, let's talk.
📌 See thrivent.com/social for important disclosures.
#ThriveThursday #OpenEnrollment #EmployeeBenefits #FinancialPlanning

#WisdomWednesday
Your health benefits might be doing less than they're capable of doing.
It's open enrollment season, and most people are asking familiar questions.
What's my deductible?
How much is my monthly premium?
What's my copay?
Are my doctors still in the network?
All important questions.
But here's one that might deserve a little more attention:
"Am I taking full advantage of my Health Savings Account?"
If you're eligible for an HSA, you may have access to a benefit that does more than help pay today's medical bills.
Consider this:
✅ Eligible contributions can offer tax advantages.
✅ Funds can carry over from year to year. There's generally no annual use-it-or-lose-it requirement.
✅ Depending on your HSA provider, you may have investment options.
✅ Qualified medical expenses can be paid with tax-free distributions.
And here's something else worth considering.
Your healthcare expenses don't necessarily stop when your paycheck does.
An HSA can be one component of a broader strategy for preparing for healthcare costs in retirement.
Of course, HSAs aren't available with every health plan, and eligibility requirements, contribution limits, and tax rules apply.
But that's exactly why open enrollment deserves more than simply checking the same boxes you checked last year.
Wisdom is not just knowing what your benefits cost. It's understanding what your benefits can do.
#WisdomWednesday #OpenEnrollment #HSA #FinancialPlanning #EmployeeBenefits #FinancialWisdom
📌 See thrivent.com/social for important disclosures.
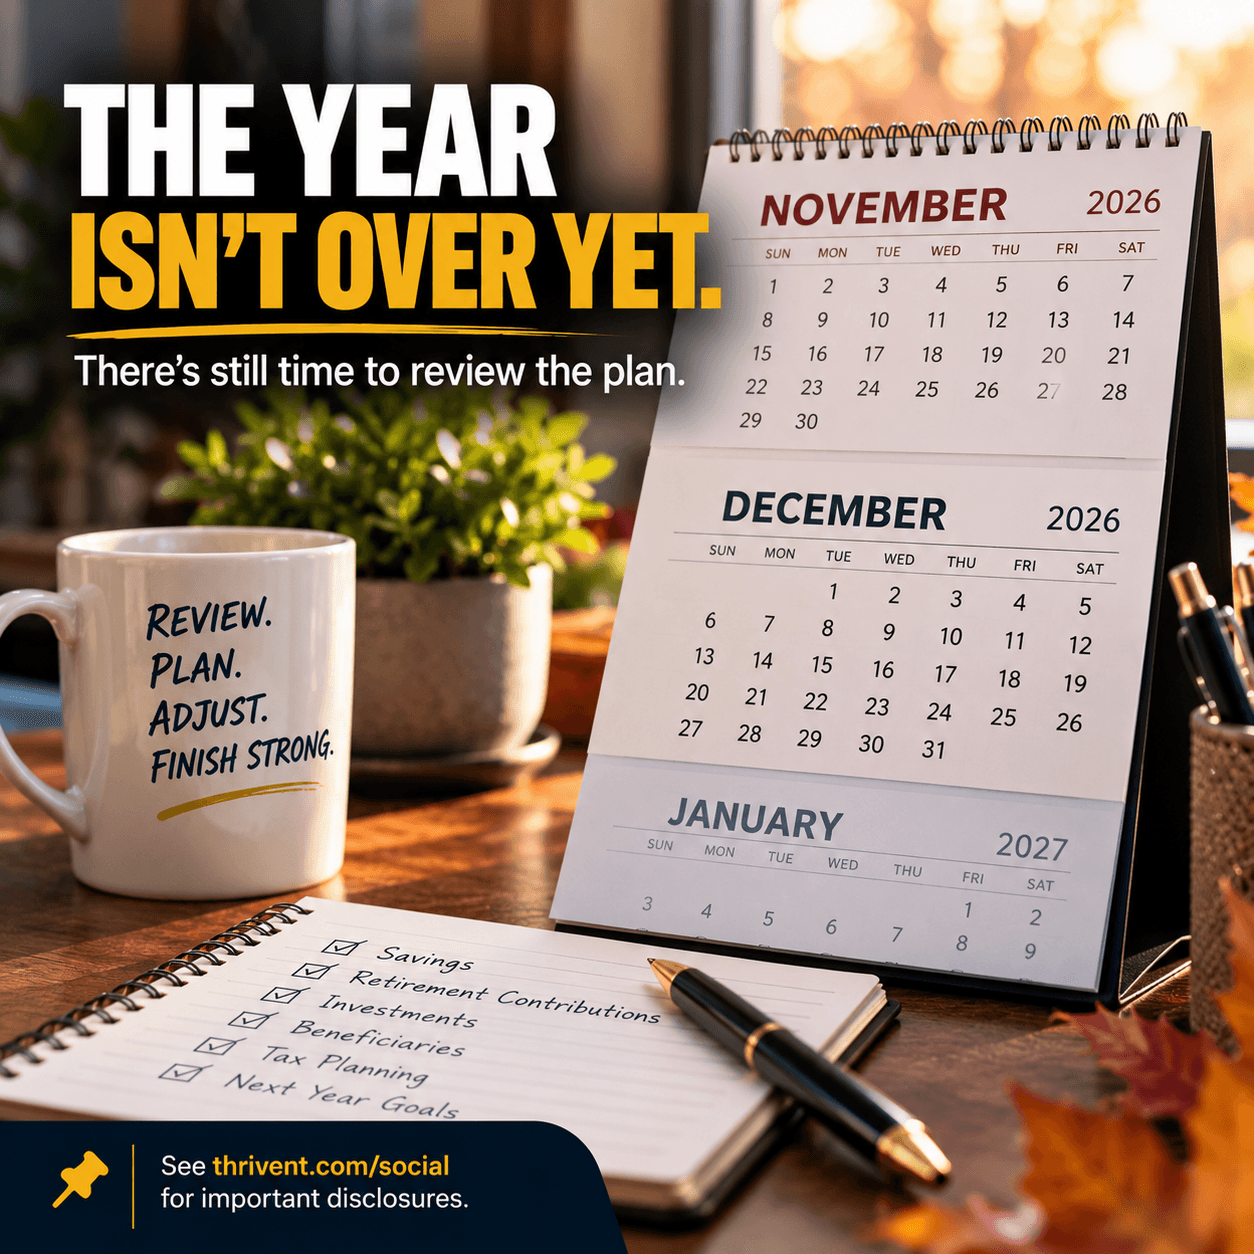
#TruthfulTuesday — The Year Isn’t Over Yet
November is here.
And for a lot of people, financially, the year is already over.
They’ve shifted their attention to Thanksgiving, Christmas, travel, shopping and everything that comes with the holidays.
But there are still two months left on the calendar.
Before you mentally close the books on this year, ask yourself:
Did I save what I intended to save?
Am I contributing what I intended toward retirement?
Have I reviewed my investments?
Did my income change this year?
Are my beneficiaries still correct?
Are there financial or tax decisions I should discuss with the appropriate professionals before December 31?
And most importantly:
Am I ending the year closer to my goals than where I started?
Sometimes the answer leads to:
“I didn’t think about that.”
Here’s the truth:
January is a great time to set goals.
November is a great time to find out whether you’re actually reaching them.
There may still be time to make thoughtful adjustments before the calendar turns.
Don't wait until January to discover what you could have addressed in November.
The year isn't over yet.
Use what's left of it intentionally.
#TruthfulTuesday #IDidntThinkAboutThat #YearEndPlanning #FinancialPlanning #PlanWithPurpose
📌 See thrivent.com/social for important disclosures.

#FinancialFreedomFriday
We spend a lot of time planning for what we want to happen.
Retirement.
Travel.
Helping our children.
Leaving a legacy.
But a complete financial plan should also consider something most of us would rather not think about:
What happens if you can't make the decisions?
If illness, an accident, or incapacity suddenly prevented you from managing your financial life tomorrow...
Who knows what you have?
Who knows where everything is?
Who understands what you wanted?
Who has the legal authority to act?
And would your family know what to do—or would they be left trying to figure it out during an already difficult moment?
That's part of financial planning too.
Because financial freedom isn't only about the choices you can make today.
It's also about intentionally preparing for how decisions will be handled when you cannot make them yourself.
Accounts matter.
Investments matter.
Insurance matters.
But so do beneficiaries, powers of attorney, estate documents, organized records, and conversations with the people who may someday need to step in.
📌 A plan shouldn't only answer, “What happens to my money?”
It should also answer, “Who makes the decisions if I can't?”
That isn't being pessimistic.
That's being prepared.
📩 DM me. Let's talk about whether your financial strategy has considered the decisions that may need to be made—not just the dollars you've accumulated.
#FinancialFreedomFriday #FinancialPlanning #LegacyPlanning #StewardshipMatters
📌 See thrivent.com/social for important disclosures.

#FinancialFreedomFriday
We spend a lot of time planning for what we want to happen.
Retirement.
Travel.
Helping our children.
Leaving a legacy.
But a complete financial plan should also consider something most of us would rather not think about:
What happens if you can't make the decisions?
If illness, an accident, or incapacity suddenly prevented you from managing your financial life tomorrow...
Who knows what you have?
Who knows where everything is?
Who understands what you wanted?
Who has the legal authority to act?
And would your family know what to do—or would they be left trying to figure it out during an already difficult moment?
That's part of financial planning too.
Because financial freedom isn't only about the choices you can make today.
It's also about intentionally preparing for how decisions will be handled when you cannot make them yourself.
Accounts matter.
Investments matter.
Insurance matters.
But so do beneficiaries, powers of attorney, estate documents, organized records, and conversations with the people who may someday need to step in.
📌 A plan shouldn't only answer, “What happens to my money?”
It should also answer, “Who makes the decisions if I can't?”
That isn't being pessimistic.
That's being prepared.
📩 DM me. Let's talk about whether your financial strategy has considered the decisions that may need to be made—not just the dollars you've accumulated.
#FinancialFreedomFriday #FinancialPlanning #LegacyPlanning #StewardshipMatters
📌 See thrivent.com/social for important disclosures.
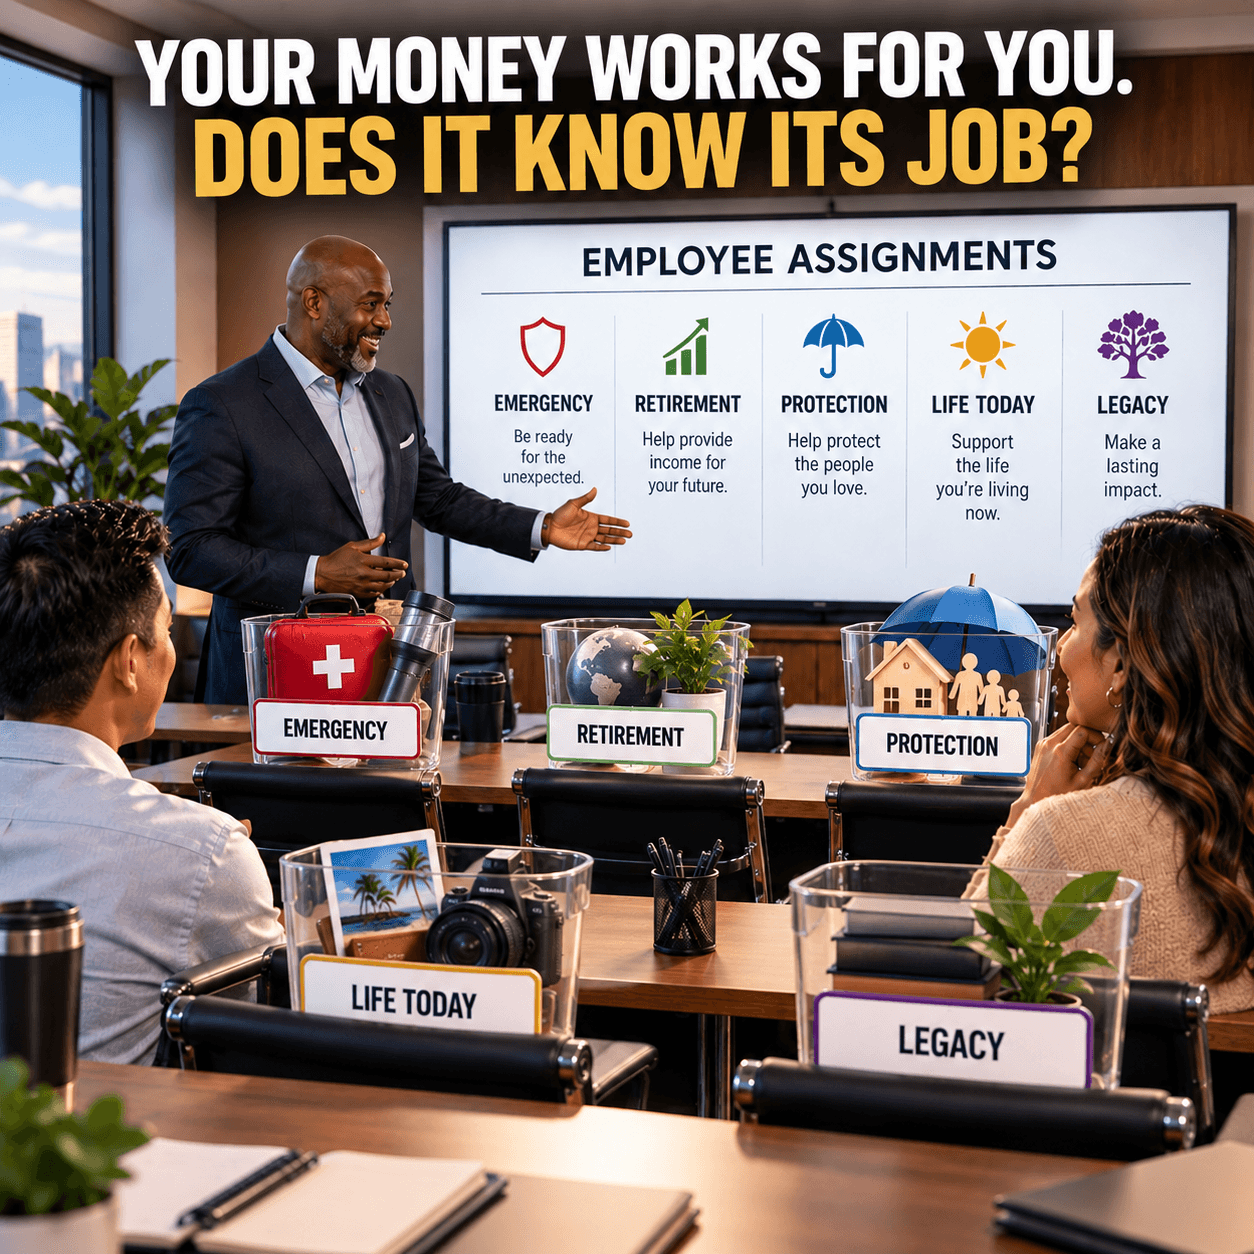
#ThriveThursday | Your Money Needs a Job Description
We spend years working for our money.
But at some point, we should ask:
What is our money working for?
Not every dollar should have the same job.
Some money may need to be available for emergencies.
Some may be intended for retirement.
Some may be invested for long-term goals.
Some may help protect the people you love.
Some may be there to enjoy life today.
And some may eventually become part of the legacy you leave behind.
The problem comes when we accumulate money without knowing what we're asking it to accomplish.
Having $100,000 in an account tells you what you have.
It doesn't necessarily tell you what that $100,000 needs to do.
That's where planning matters.
We begin with the goal—and then determine what role your money needs to play in pursuing it.
Because your money shouldn't just sit in different accounts without direction.
You worked hard for your money.
Now make sure your money knows its assignment.
If you have accounts but aren't sure how they all connect to what you're trying to accomplish, let's talk.
📌 See thrivent.com/social for important disclosures.
#ThriveThursday #FinancialPlanning #FinancialClarity #PurposeDrivenWealth
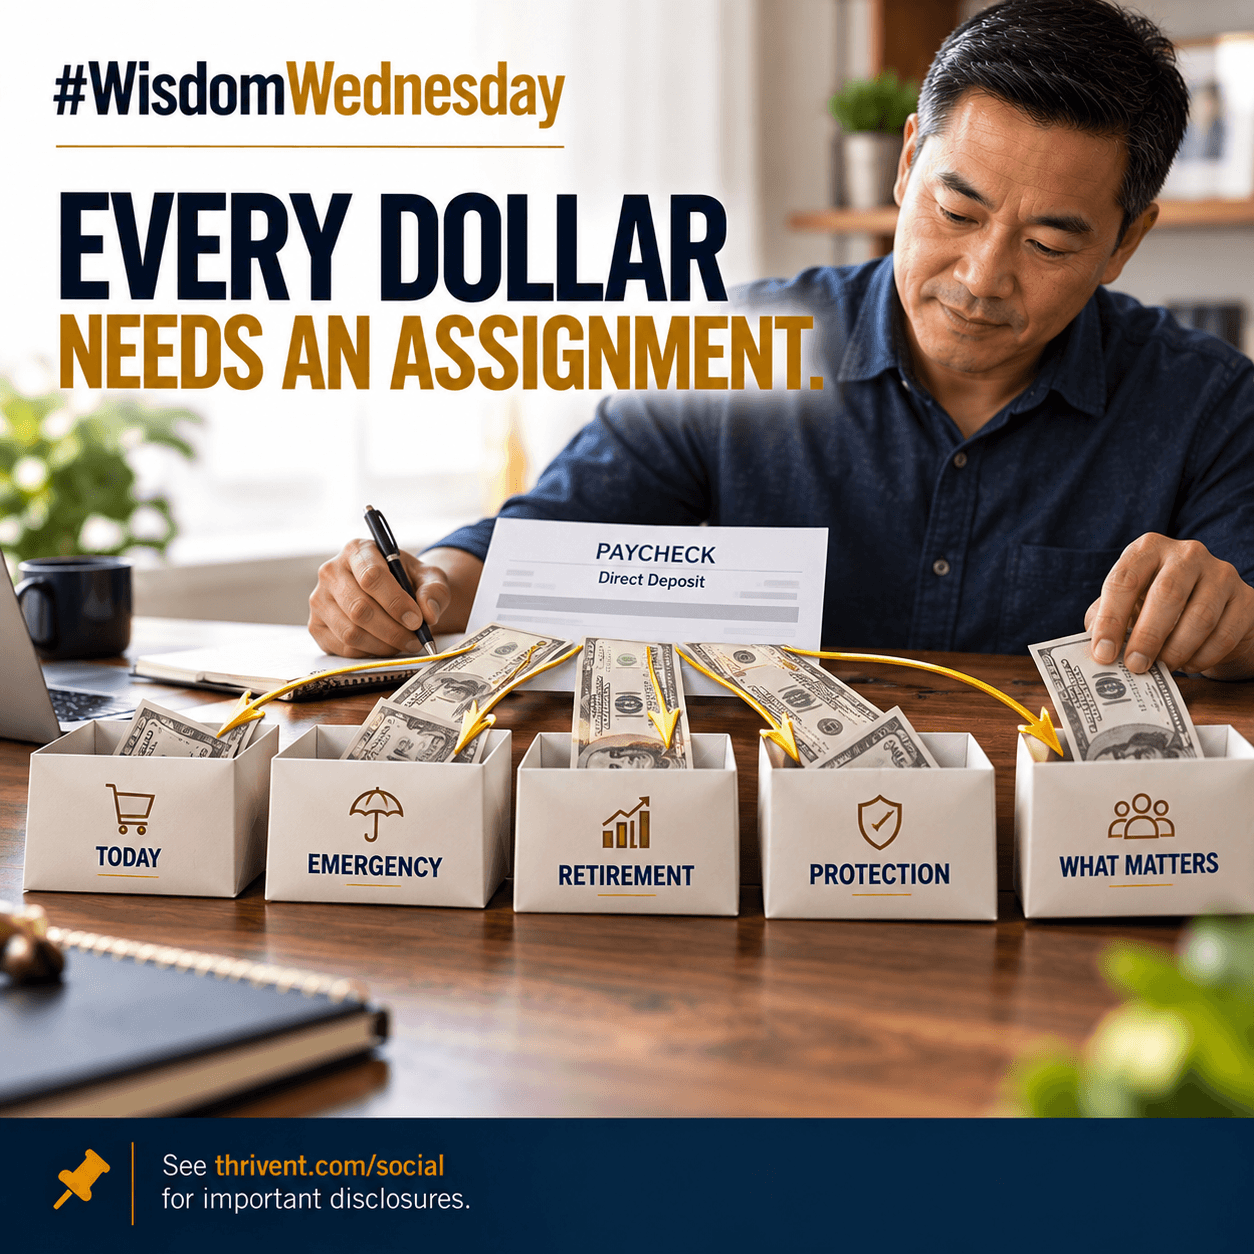
#WisdomWednesday
Your paycheck has a job description. Does every dollar know its assignment?
Most of us would never run a business where money came in and nobody knew where it was supposed to go.
Payroll.
Rent.
Inventory.
Taxes.
Future growth.
Each dollar has a purpose.
But with our personal finances, it can be easy to let money arrive, pay whatever is due, spend what’s left—and hope we’re moving in the right direction.
What if instead, your money had assignments?
Some for today.
Some for emergencies.
Some for retirement.
Some for protection.
Some for the people and causes that matter to you.
It’s not necessarily about earning more.
Sometimes it’s about being more intentional with what you already earn.
Wisdom is making sure your money isn't just coming in and going out—it’s working toward the things that matter to you.
#WisdomWednesday #FinancialPlanning #FinancialWisdom #MoneyManagement #PlanWithPurpose
📌 See thrivent.com/social for important disclosures.

#TruthfulTuesday — The Payment Isn't the Price
“How much is the payment?”
It’s one of the first questions we ask when buying a car, a home, furniture—or almost anything we finance.
But sometimes that’s the wrong question.
Because being able to make the payment doesn't necessarily mean you can afford the purchase.
What else does that payment affect?
Does it reduce what you can save?
Does it keep you from increasing your retirement contributions?
Does it make an unexpected expense harder to absorb?
Does it require you to use credit for things you previously paid for with cash?
And most importantly…
What are you giving up to make that payment?
That's when I sometimes hear:
“I didn't think about that.”
Truth: Affordability isn't just about whether the payment fits your monthly budget. It's about whether the purchase fits your financial plan.
A payment can fit.
And still compete with everything else you're trying to accomplish.
Before asking:
“Can I make the payment?”
Try asking:
“Can I make this payment AND continue doing the other things that matter to me?”
That second question can change the decision.
#TruthfulTuesday #IDidntThinkAboutThat #FinancialPlanning #FinancialWisdom #PlanWithPurpose
📌 See thrivent.com/social for important disclosures.

#MoneyMovesMonday
You don't need more money to start making better money decisions.
It's easy to think:
“When I make more, I'll start investing.”
“When I get the promotion, I'll make a plan.”
“When I pay this off, I'll talk to an advisor.”
“When things settle down, I'll get serious about my finances.”
But here's the thing:
More money doesn't automatically create better financial habits.
The habits you build with what you have today can help shape what you do when you have more tomorrow.
Planning can start right where you are.
Maybe it's $25 more toward savings.
Maybe it's finally understanding your workplace benefits.
Maybe it's reviewing your insurance.
Maybe it's simply sitting down and figuring out where your money is going.
You don't have to wait until your financial life looks perfect.
Start with what you have.
Start where you are.
That's a money move you can make today.
📩 If you've been waiting until you have “enough” to talk with a financial advisor, let's have a conversation.
#MoneyMovesMonday #FinancialPlanning #MoneyHabits #StartToday #PurposeDrivenPlanning #Thrivent
📌 See thrivent.com/social for important disclosures.
#FinancialFreedomFriday | Open Enrollment Edition
Open enrollment can become one of those things we put on autopilot.
Email arrives.
Benefits portal opens.
Click. Click. Click.
“Same as last year.”
Done.
But before you hit submit, ask yourself:
Is your life the same as last year?
Maybe your income changed.
Maybe you got married or divorced.
Maybe you welcomed a child or grandchild.
Maybe retirement is one year closer.
Maybe your health expenses changed.
Maybe you're helping aging parents.
Maybe your financial priorities simply aren't what they were 12 months ago.
Your employer benefits are part of your overall financial picture. Your health coverage, retirement contributions, HSA or FSA elections, life and disability coverage, beneficiaries, and other available benefits can all deserve another look.
Open enrollment isn't just a time to renew benefits.
It's an opportunity to ask whether the choices you're making at work still coordinate with the financial strategy you're building outside of work.
📌 Don't renew last year's decisions without reviewing this year's life.
Take the extra few minutes.
Ask the questions.
Understand your options.
Then make an informed decision.
📩 If you're looking at your benefits package and wondering how those choices fit into your bigger financial picture, DM me. Let's look at the whole plan—not just the enrollment screen.
#FinancialFreedomFriday #OpenEnrollment #FinancialPlanning #FinancialClarity
📌 See thrivent.com/social for important disclosures.

#ThriveThursday | Don’t Let One Tax Bucket Become Your Whole Strategy
Open enrollment is a good time to look at more than just your benefits.
It’s also an opportunity to look at where your retirement dollars are going.
For many people, most—or even all—of their retirement savings may be accumulating in a tax-deferred bucket.
That can provide valuable tax advantages today.
But remember what “tax-deferred” means:
The taxes are deferred. They aren’t necessarily eliminated.
When retirement comes, withdrawals from tax-deferred accounts are generally taxable as ordinary income.
So instead of only asking:
“How much should I contribute?”
Consider another question:
“Am I building different tax buckets for my future?”
Depending on your circumstances and the options available to you, that could mean considering a mix of:
Tax-deferred money — taxes generally paid when withdrawn.
Tax-free money — when applicable requirements are met.
Taxable money — which may provide another source of assets and flexibility.
The goal isn't to predict what tax rates will be decades from now.
It’s to recognize that having money with different tax treatments may give you more options when deciding where retirement income comes from.
So during open enrollment, don't automatically check the same boxes you checked last year.
Review. Ask questions. Understand your options. Then make an informed decision.
Because diversification shouldn't necessarily stop with your investments.
It can also include how your money may be taxed.
📌 See thrivent.com/social for important disclosures.
#ThriveThursday #OpenEnrollment #TaxDiversification #RetirementPlanning
#TruthfulTuesday — Open Enrollment: Don’t Just Click “Same as Last Year”
Open enrollment arrives, and it’s tempting to do the easiest thing:
Keep everything the same.
But before you click that button, ask yourself:
Is everything actually the same?
Did you get married?
Have a child?
Get divorced?
Lose someone you love?
Buy a home?
Experience a significant change in income?
Has your health or your family’s healthcare needs changed?
Are the beneficiaries listed on your benefits still the people you want them to be?
Open enrollment isn't just about comparing health plans and deductibles. It can be an opportunity to review your benefits and make sure your elections still reflect the life you're living today.
Because there's one detail we don't like talking about:
Some mistakes aren't discovered until it's too late to correct them.
If beneficiary information or other important elections no longer reflect your intentions, your family may be the ones dealing with the consequences.
That's when families can be left saying:
“We didn't think about that.”
Truth: Your life can change faster than your paperwork does.
Don't assume last year's decisions still fit this year's life.
Use open enrollment as your reminder to review your coverage, beneficiaries, protection needs, and other available benefits.
And don't just ask, “What did I choose last year?”
Ask:
“What has changed since then?”
Because planning isn't only about preparing for tomorrow.
It's also about making sure your decisions accurately reflect today.
#TruthfulTuesday #OpenEnrollment #IDidntThinkAboutThat #FinancialPlanning #BeneficiaryReview
📌 See thrivent.com/social for important disclosures.

#MoneyMovesMonday
Open enrollment is here. Don't just click “same as last year.”
For many employees, open enrollment becomes an annual routine:
Log in.
Keep the same choices.
Click submit.
Done.
But a lot can change in a year.
Your income may have changed.
Your family may have changed.
Your health care needs may have changed.
Your financial goals may have changed.
And your employer's benefits may have changed, too.
This is a good time to review more than just your health insurance.
Take another look at your:
✔️ Health plan options
✔️ HSA or FSA elections
✔️ Life insurance benefits
✔️ Disability coverage
✔️ Retirement contributions
✔️ Beneficiary designations
✔️ Other benefits available through your employer
The question isn't simply:
“What did I choose last year?”
Ask:
“Do these choices still fit my life and my financial strategy today?”
Your workplace benefits can be an important part of your overall financial picture.
This week's money move: Don't automatically renew. Review.
📩 If you'd like help understanding how your workplace benefits fit with the rest of your financial strategy, let's talk.
#MoneyMovesMonday #OpenEnrollment #EmployeeBenefits #FinancialPlanning #WorkplaceBenefits #Thrivent
📌 See thrivent.com/social for important disclosures.

#WisdomWednesday
Open enrollment isn't only about choosing benefits. It may also be an opportunity to make sure you're not leaving part of your compensation on the table.
If your employer offers a retirement plan with a company match, that match is part of your benefits package.
But depending on how the plan works, you may have to contribute enough to receive the full available match.
Think about that for a moment.
You negotiated your salary.
You show up for work.
You earn your benefits.
But if you haven't reviewed your retirement contribution lately, you could be missing an opportunity your employer already provides.
Open enrollment season is a good reminder to look beyond health insurance and ask:
“Am I taking full advantage of the benefits available to me?”
Review the match formula.
Know how much you're contributing.
Understand any eligibility or vesting requirements.
And determine what contribution level makes sense for your overall financial situation.
You don't have to blindly select the same options you chose last year.
Wisdom is understanding what your employer offers—and making an informed decision about how those benefits fit into your financial plan.
#WisdomWednesday #OpenEnrollment #RetirementPlanning #401k #EmployeeBenefits #FinancialWisdom
📌 See thrivent.com/social for important disclosures.