Associate
.Tax Efficient Planning
Young Families
Healthcare Professionals
Retirement Planning
Business Owners
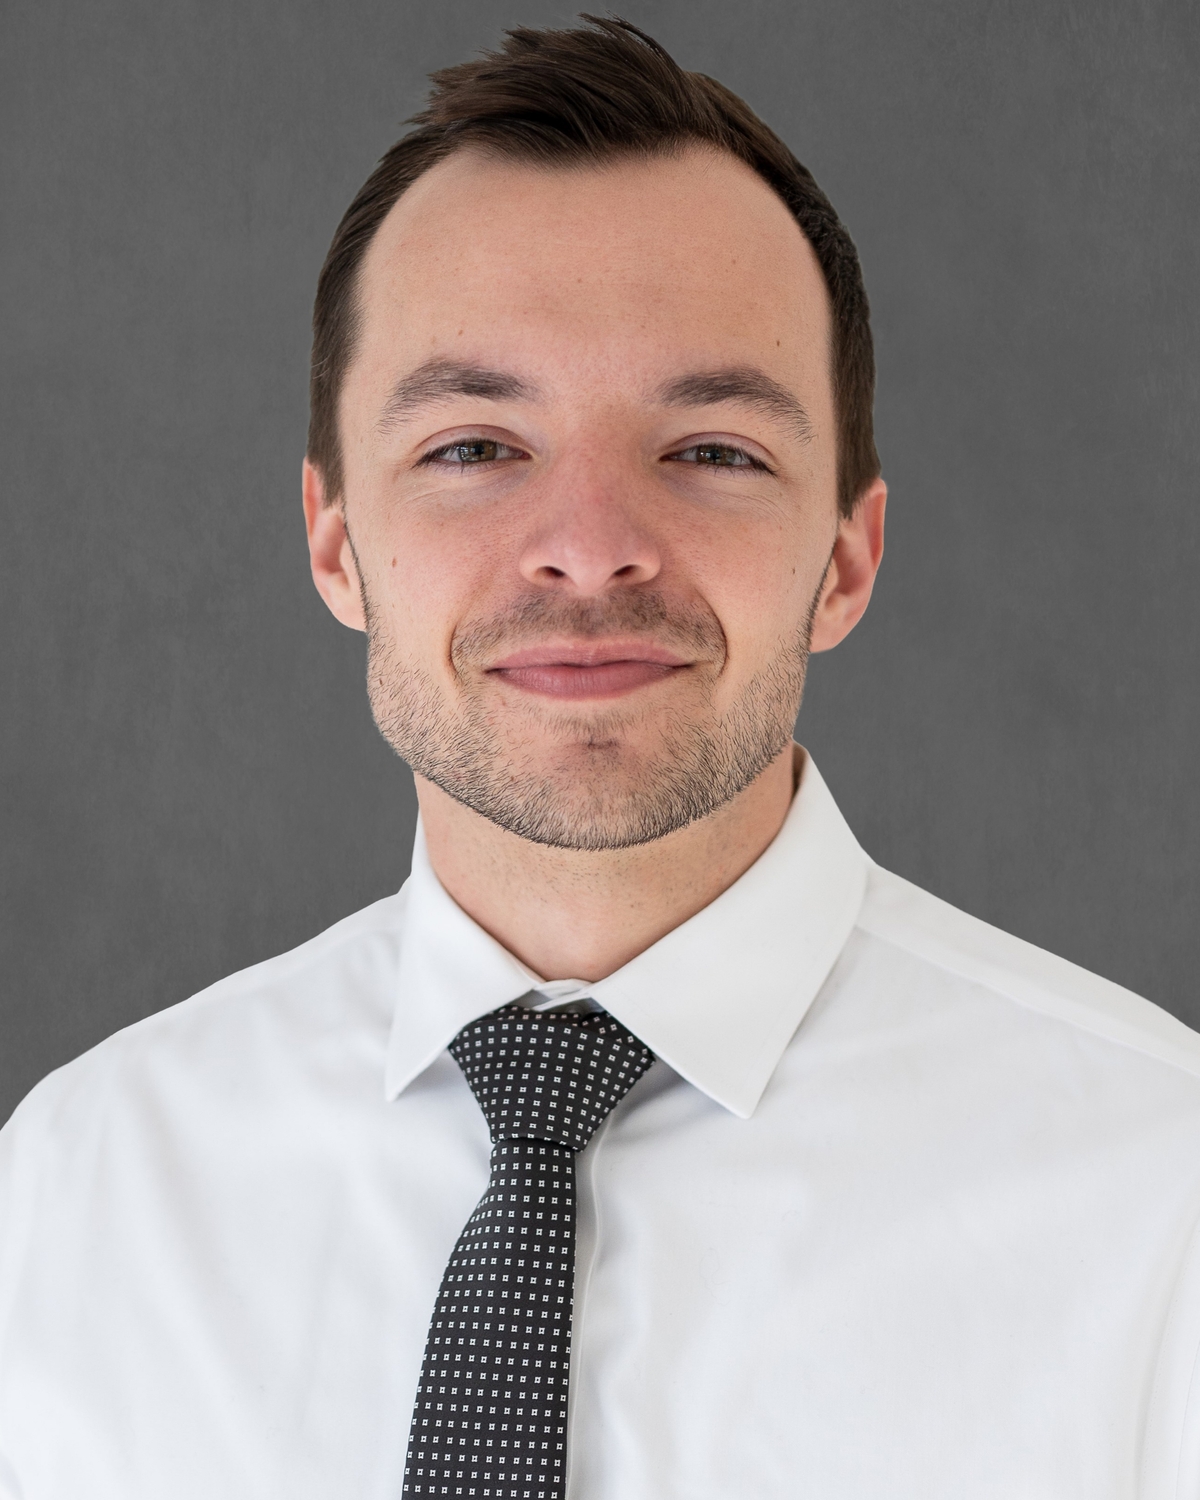
Eric Christopherson is a CERTIFIED FINANCIAL PLANNER® professional with The Grove Financial Group in Wheaton, Illinois. Raised just next door in Batavia, Eric graduated from Olivet Nazarene University in Bourbonnais, Illinois. He began his career at Thrivent, serving families in the Chicago suburbs, before he and his wife, Grace, a fourth-year medical student, relocated to West Virginia for several years while she pursued her medical training. Now working with clients in over 15 states, Eric focuses on bringing simplicity and clarity to complex decisions, building practical plans that align money with what matters most.
Eric is most passionate about helping pre-retirees with tax-efficient planning, guiding graduate students in managing significant debt, and partnering with small business owners. Outside of work, Eric values his faith, family, and serving his community. You’ll often find him and his wife out golfing or exploring with their golden retriever, Blue.
Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the United States to Certified Financial Planner Board of Standards, Inc., which authorizes individuals who successfully complete the organization's initial and ongoing certification requirements to use the certification marks.
- CERTIFIED FINANCIAL PLANNER®
- FINRA Series 7 General Securities Representative
- FINRA Series 66 Licensed
- Life & Health Insurances Licenses
Are you a fiduciary?
Yes. As a CFP® Practitioner, I am required to be a fiduciary and act in the best interest of my clients at all times. Here are the Code of Ethics for me as a CFP® professional.
- Act with honesty, integrity, competence, and diligence.
- Act in the client’s best interests.
- Exercise due care.
- Avoid or disclose and manage conflicts of interest.
- Maintain the confidentiality and protect the privacy of client information.
- Act in a manner that reflects positively on the financial planning profession and CFP® certification.
What makes your financial planning approach different?
At The Grove Financial Group, we take a truly holistic approach to financial planning. While many advisors focus solely on managing investments or selling insurance products, we believe your financial life deserves more than a one-size-fits-all solution.
We look at the full picture of your goals, values, income, taxes, risk tolerance, estate planning, and more to craft personalized strategies that evolve with you over time. As a CERTIFIED FINANCIAL PLANNER™, I am held to a fiduciary standard, meaning we’re committed to putting your best interests first in every recommendation we make.
Our goal is to be your long-term partner in building a confident financial future.
Why should I hire you instead of doing this myself?
Because even small mistakes can have big consequences. I help you avoid costly errors, spot opportunities you might miss, and create a plan you can trust. Managing finances well also takes time and focus. Many of my clients are fully capable but choose to delegate so they can spend their time on what matters most- while I handle the financial details.
Can I work with you if I live in another state? Do you offer virtual meetings?
Yes! I work with clients in over 15 states, and most of my meetings are virtual via video call. No matter where you live, you’ll receive the same personalized service.
How are you compensated?
We offer a variety of compensation models to fit the unique needs of our clients. Depending on the services provided, we may be compensated through:
- Flat-fee financial planning- a transparent, set fee for developing and implementing a customized financial plan.
- Assets under management (AUM)- an ongoing fee based on the value of the investments we manage on your behalf.
- Commission-based compensation- for certain investment or insurance products, where appropriate.
Can you help my company set up workplace benefits?
Yes! We help small to medium sized businesses/ organizations set up and manage workplace benefits like retirement plans, group insurance, and other employee benefits. We find ourselves working with churches and private schools often. We can also assist with ongoing education and support to ensure your team gets the most out of their benefits package.
I'd like to learn more, what is the next step?
Click here to schedule an intro call. Book a meeting with Eric Christopherson
Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the United States to Certified Financial Planner Board of Standards, Inc., which authorizes individuals who successfully complete the organization's initial and ongoing certification requirements to use the certification marks.
- Bachelors of Finance, Olivet Nazarene University
- CERTIFIED FINANCIAL PLANNER®
- Series 7 - General Securities Representative
- Securities Industry Essentials
- Arizona
- California(Insurance Lic. #4192945)
- Colorado
- Connecticut
- Florida
- Georgia
- Illinois
- Indiana
- Iowa
- Kansas
- Michigan
- Minnesota
- New York
- North Carolina
- Ohio
- Pennsylvania
- South Carolina
- Texas
- Virginia
- West Virginia
- Wisconsin
Insights
Just because you’re in the 22% tax bracket doesn’t mean all of your income is taxed at 22%.
Only the income above that bracket’s threshold is taxed at that rate. The dollars below it are still taxed at the lower brackets.
This is how a marginal tax system works, and it’s one of the most misunderstood parts of taxes. It also changes how you should think about raises, bonuses, and tax planning in general.
See thrivent.com/social for more information. Thrivent and its financial advisors and professionals do not provide legal, accounting or tax advice. Consult your attorney or tax professional.
Small business owners in the thick of growth often assume saving for retirement just isn’t doable.
Many I speak with ask about a 401(k), only to get discouraged when they learn it can cost thousands of dollars per year in administrative fees. What many don’t realize is that there are other retirement plan options that allow you to:
- Offer an employer match
- Reduce your taxable income
- Get a plan up and running with minimal complexity
One of my favorites for growing businesses is the SIMPLE IRA.
A SIMPLE IRA can be a great stepping stone for business owners who want to start diverting some earnings toward retirement but aren’t quite ready for the cost and complexity of a full 401(k).
Here are a few key benefits:
• No cost to establish the plan
• Employer contributions are tax‑deductible
• Employees can start saving right away
If you’re a business owner who’s been putting retirement planning on the back burner, this might be a great place to start.
Learn more here:
https://www.thrivent.com/insights/retirement-planning/how-a-simple-ira-works see thrivent.com/social for more information
Short term disability is helpful, but its importance may fade when you have a strong financial plan in place. Why? Short-term disability is intended to replace your income for the first few months of a disability. However, if you have a fully implemented financial plan, your plan's emergency fund may be able to fulfill this income gap rather than rely on your short-term disability coverage.
But what if that disability lasts longer than 6 months?
That’s where long-term disability insurance becomes essential. It ensures your income continues so you can pay medical expenses, keep saving for the future, and avoid the financial devastation that often leads to bankruptcy.
With 1 in 4 individuals experiencing a long-term disability event (per the Social Security Administration), this is one of the most overlooked areas in financial planning.
https://www.ssa.gov/pubs/EN-05-10029.pdf
See thrivent.com/social for more information.
Office locations
Licensing is available through your State Insurance Department’s website, which can be located through the National Association of Insurance Commissioners website.
Thrivent and its financial advisors and professionals do not provide legal, accounting or tax advice. Consult your attorney or tax professional.
Thrivent financial advisors and professionals have general knowledge of the Social Security tenets. For complete details on your situation, contact the Social Security Administration.
Thrivent provides advice and guidance through its Financial Planning Framework that generally includes a review and analysis of a client’s financial situation. A client may choose to further their planning engagement with Thrivent through its Dedicated Planning Services (an investment advisory service) that results in written recommendations for a fee.
Designations
For additional information on professional designations and the requirements to earn them, visit https://www.thrivent.com/designations
Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the United States to Certified Financial Planner Board of Standards, Inc., which authorizes individuals who successfully complete the organization's initial and ongoing certification requirements to use the certification marks.
Thrivent and its financial advisors and professionals do not provide legal, accounting or tax advice. Consult your attorney or tax professional.
Thrivent financial advisors and professionals have general knowledge of the Social Security tenets. For complete details on your situation, contact the Social Security Administration.
Thrivent provides advice and guidance through its Financial Planning Framework that generally includes a review and analysis of a client’s financial situation. A client may choose to further their planning engagement with Thrivent through its Dedicated Planning Services (an investment advisory service) that results in written recommendations for a fee.
Designations
For additional information on professional designations and the requirements to earn them, visit https://www.thrivent.com/designations
Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the United States to Certified Financial Planner Board of Standards, Inc., which authorizes individuals who successfully complete the organization's initial and ongoing certification requirements to use the certification marks.