Financial Advisor
.Tax Efficient Planning
Retirement Planning
One coordinated plan covering investments, taxes, Social Security, and risk, built for people in Longview and Kelso within 10 years of retirement.
🗺️ How do all my accounts work together?
Old 401(k)s, IRAs, and savings, coordinated into one income picture instead of managed separately.
💵 How do savings become a stream of income?
There's a specific order to draw from accounts that can help improve the longevity of your retirement assets.
🧾 Am I positioned to be tax-efficient?
We look at the three tax buckets: tax now, tax later, and tax never and plan your income accordingly.
🏠 Is my family protected either way?
A plan should hold up if something bad happens, not just if everything goes right.
To explore working together we'll go through my 3 meeting process:
- Connect. We'll get to know your situation, no numbers required yet.
- Discover. We build your financial plan and your probability of success.
- Deliver. You get your printed financial plan summary and clear next steps.
A printed financial plan summary at your third meeting, covering:
- Net worth summary
- Income projection
- Probability of success
- Risk review
- Tax-efficiency snapshot
- Your action steps
From there, the next step is up to you. If we both feel like it's a good fit, I'll lay out what working together looks like. I won't ask you to decide on the spot. I'd rather you take it home, talk it over, and sleep on it.
✅ You live in or near Longview or Kelso
✅ You're within 10 years of retiring
✅ You'd rather hand this off than manage it yourself
✅ You want your accounts working together, not scattered
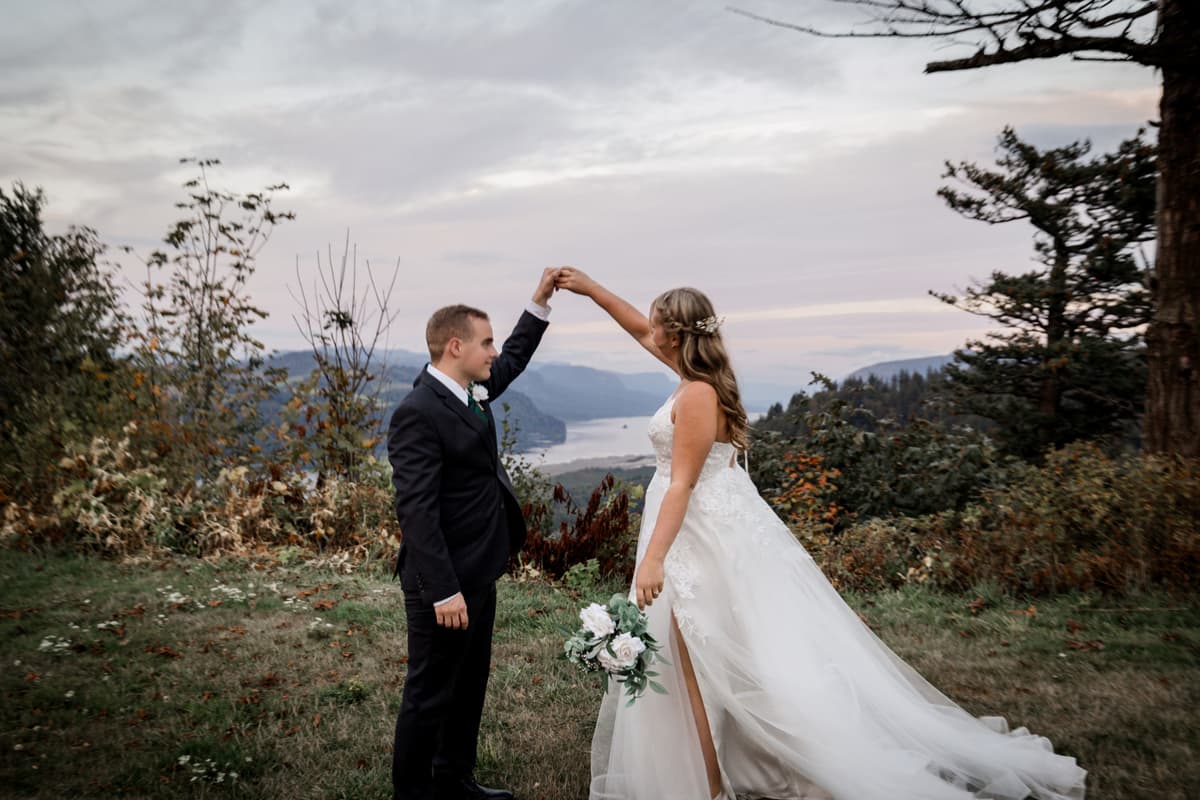
Born and raised in Longview. This is home. Outside the office you'll likely find me at the gym, on a hike or tennis court when the sun's out, or spending time with my wife and our local family. I serve on the board for Habitat for Humanity, worship at our local church on Sundays, and meet monthly with a group of Christian business owners for encouragement and fellowship.
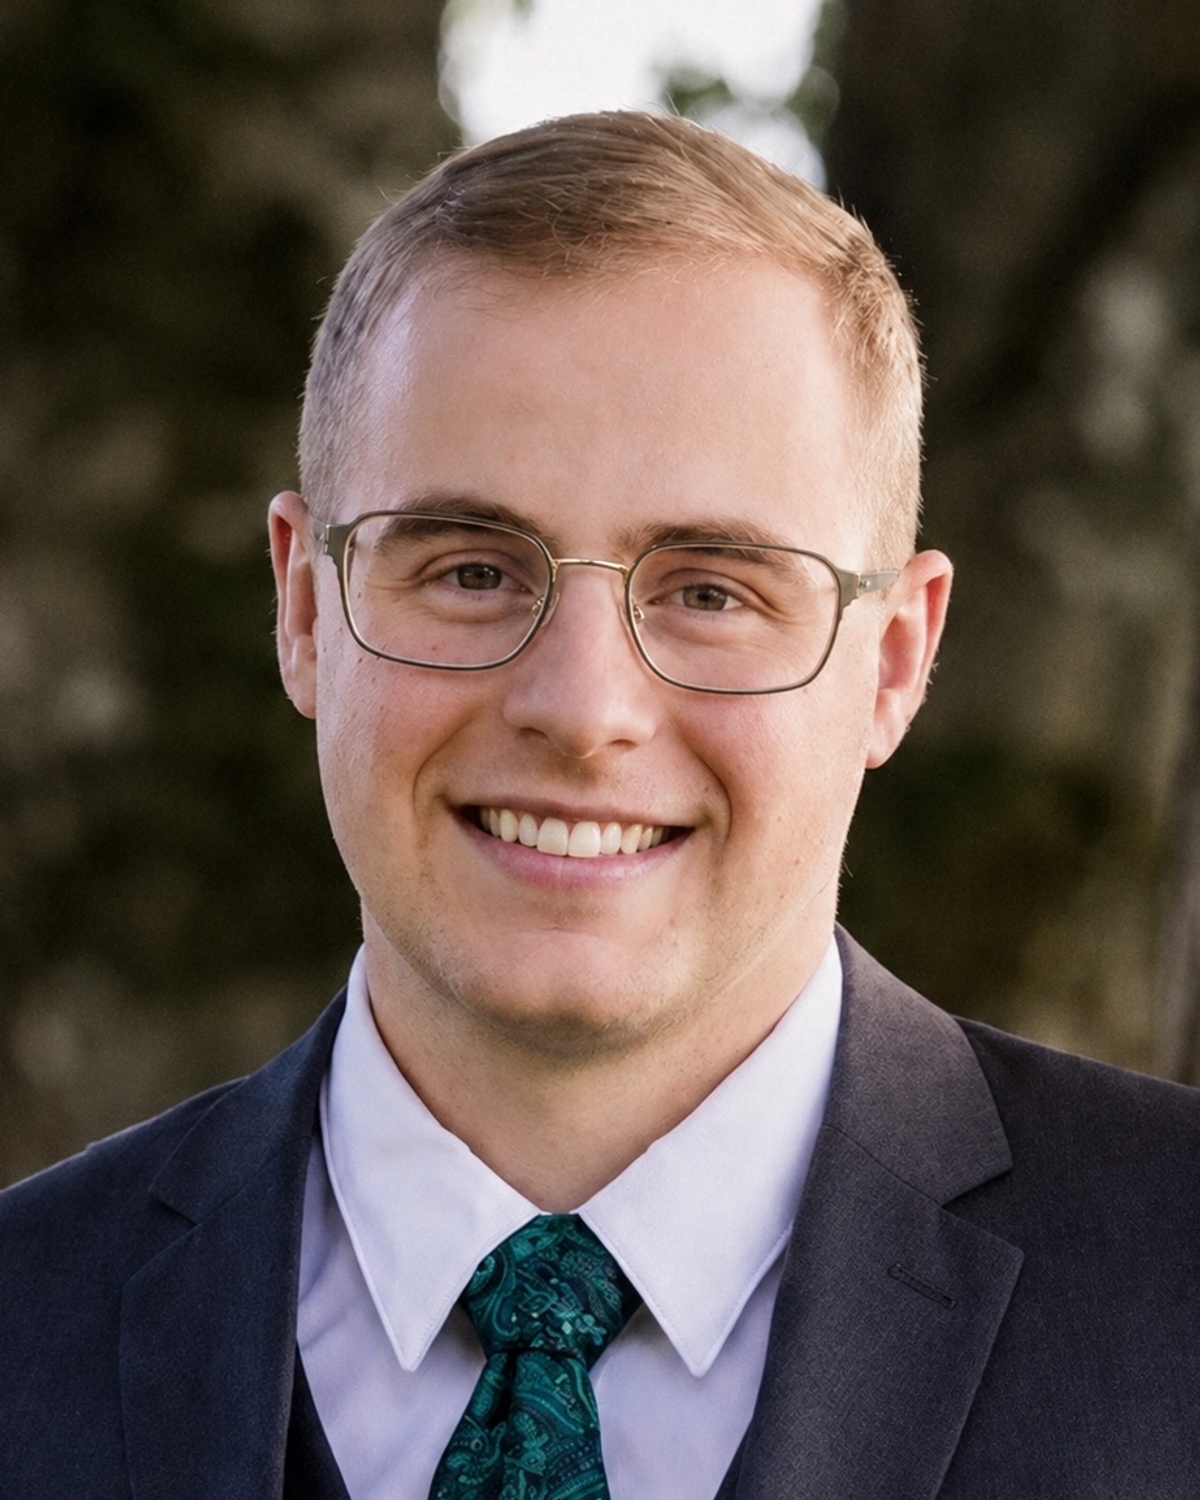
I earned my Bachelor's degree in Financial Planning from Franklin University and built my early career at another firm before finding my home at Thrivent, whose values matches my own. I care about my clients personally, not just their portfolios. My work is about helping people retire with enough confidence that they can spend their time on the people they love instead of worrying about money.
- Bachelors of Finance, Franklin University
- Fraternal Insurance Counselor
- Series 7 - General Securities Representative
- Securities Industry Essentials
- Arizona
- California(Insurance Lic. #4430167)
- Idaho
- Oregon
- Washington
Insights
Should I make my portfolio "safe" right before retirement?
Maybe, but I don't think that's actually the right question.
A better question might be: "Do I have a safe place to get money when I need it?"
A lot of people approaching retirement assume they should move everything into conservative investments. The challenge is that retirement might last 25 or 30 years. If all of your money becomes too conservative too soon, you could lose some of the growth needed to support a long retirement.
Instead, I often think about retirement assets in buckets based on when the money will be spent.
The first bucket is money you expect to spend during your first 0-3 years of retirement. Since that money will be needed soon, the focus should be on stability. We can't afford for money needed next year to be heavily exposed to market swings.
The second bucket is money you expect to spend during years 4-7 of retirement. Since you have a little more time before you'll need those dollars, this bucket can typically take on a bit more investment risk while still maintaining a focus on future income needs.
The third bucket is money you don't expect to spend until year 8 and beyond. Since time is on our side, this money often has the opportunity to be invested more for growth. If the market experiences a downturn, there may be years available for recovery before those dollars are needed.
This becomes especially important during what's often called the retirement red zone, which is generally the five years before retirement and the first five years after retirement. A major market decline during this period can have a much bigger impact than it would earlier in life because you're preparing to withdraw money or may already be doing so.
Think about a couple retiring at age 65 who plans to wait until age 67 to begin Social Security. For those two years, they'll need income from somewhere. If all of their investments are tied up in the stock market and the market drops significantly, they may be forced to sell investments while they're down just to cover living expenses.
That's one reason I like the bucket concept. If we know certain money will be needed during the first few years of retirement, we can set it aside appropriately and avoid relying on the stock market to provide income at exactly the wrong time.
Retirement planning isn't necessarily about making your entire portfolio safe. It's about making sure the money you'll spend in the next few years is available when you need it while giving your longer-term dollars the opportunity to continue growing.
Having a plan for where your income will come from, regardless of what the market is doing, can provide a lot of confidence and peace of mind as you approach retirement.
See thrivent.com/social for important disclosures.
Am I too late to start saving for retirement?
The brutal reality is: maybe. Hear me out. Some folks dream of retiring on more income than they're earning while they're working. If you're behind schedule, that might not be possible if you want to retire soon. But here's the thing: retirement isn't all about income. Let me tell you about some expenses that should be gone by retirement, like your mortgage, FICA taxes (social security), and saving for retirement itself. What if having a similar income in retirement as you earn now is actually a raise? Even if extra retirement income is off the table, it might still work out just fine.
But really, the most dangerous move is doing nothing. Putting your head in the sand. One day, you will be in retirement. One day, you'll need to create income from your savings. It's simple: saving now makes it easier later. So how much should you start saving? That's a great question. Take a look at my last post for a guide, then use a future value calculator to figure out how much you might have in retirement based on a new savings level. Add that into the calculations from the previous post.
Here are a few last resort ideas. You can move. Downsize, live with your kids, or use the equity in your home. Be aware of tax implications, but this is a common decision later in life, and it can help both you and your kids. You could get cheaper rent and they get a stream of income. They can even use that to save for their own retirement (wink). I'd encourage you to sit down and create a plan now instead of later. Remember, saving now makes it easier later.
See thrivent.com/social for important disclosures.
Can you retire when you want to?
Here's how to figure out a rough idea. Grab a piece of paper and write down your ideal retirement age. Then write down your expected monthly income sources, like social security and a pension if you have one. Next, add in your other retirement savings. Let's say you have $600,000 saved but you're not sure how much income that could provide. For now, use the 4% rule. Take $600,000 x 4% and divide by 12 months, and you get about $2,000 per month.
Add everything together. Maybe it's $3,000 from social security, $1,000 from a pension, and $2,000 from your retirement accounts, which comes out to $6,000 per month. This is where a lot of people stop, but they miss two key pieces: taxes and survivorship.
In this example, that $6,000 is your pre-tax income. To keep the math simple, if you're taxed at 20%, your after-tax income would actually be $4,800.
Second, when you wrote down your pension, did you pick 100% survivorship or single life income? A pension is usually lower if it has to pay out for both of your lifetimes instead of just one. On top of that, a surviving spouse loses the smaller of the two social security checks. So in this same example, if one spouse passes away, the future income could look like $2,000 from social security, $750 from the pension, and $2,000 from retirement accounts, totaling $4,750. That surviving spouse also moves into the single filer tax bracket, which can raise their tax bill even further.
I share this because knowing your actual after-tax income matters more than the number on paper. Run your own numbers. Are you on track? If yes, great. If not, you really only have three options: save more now, spend less later, or work longer.
See thrivent.com/social for important disclosures.
Office location
Longview Location
1402 Broadway St STE 202
Longview, WA 98632
Phone360-747-2669HoursLongview, WA 98632
M – F: 10 a.m. – 5 p.m.
Licensing is available through your State Insurance Department’s website, which can be located through the National Association of Insurance Commissioners website.
Thrivent and its financial advisors and professionals do not provide legal, accounting or tax advice. Consult your attorney or tax professional.
Thrivent financial advisors and professionals have general knowledge of the Social Security tenets. For complete details on your situation, contact the Social Security Administration.
Thrivent provides advice and guidance through its Financial Planning Framework that generally includes a review and analysis of a client’s financial situation. A client may choose to further their planning engagement with Thrivent through its Dedicated Planning Services (an investment advisory service) that results in written recommendations for a fee.
Designations
For additional information on professional designations and the requirements to earn them, visit https://www.thrivent.com/designations