Financial Advisor
.Tax Efficient Planning
Retirement Planning
One coordinated plan covering investments, taxes, Social Security, and risk, built for people in Longview and Kelso within 10 years of retirement.
🗺️ How do all my accounts work together?
Old 401(k)s, IRAs, and savings, coordinated into one income picture instead of managed separately.
💵 How do savings become a stream of income?
There's a specific order to draw from accounts that can help improve the longevity of your retirement assets.
🧾 Am I positioned to be tax-efficient?
We look at the three tax buckets: tax now, tax later, and tax never and plan your income accordingly.
🏠 Is my family protected either way?
A plan should hold up if something bad happens, not just if everything goes right.
To explore working together we'll go through my 3 meeting process:
- Connect. We'll get to know your situation, no numbers required yet.
- Discover. We build your financial plan and your probability of success.
- Deliver. You get your printed financial plan summary and clear next steps.
A printed financial plan summary at your third meeting, covering:
- Net worth summary
- Income projection
- Probability of success
- Risk review
- Tax-efficiency snapshot
- Your action steps
From there, the next step is up to you. If we both feel like it's a good fit, I'll lay out what working together looks like. I won't ask you to decide on the spot. I'd rather you take it home, talk it over, and sleep on it.
✅ You live in or near Longview or Kelso
✅ You're within 10 years of retiring
✅ You'd rather hand this off than manage it yourself
✅ You want your accounts working together, not scattered
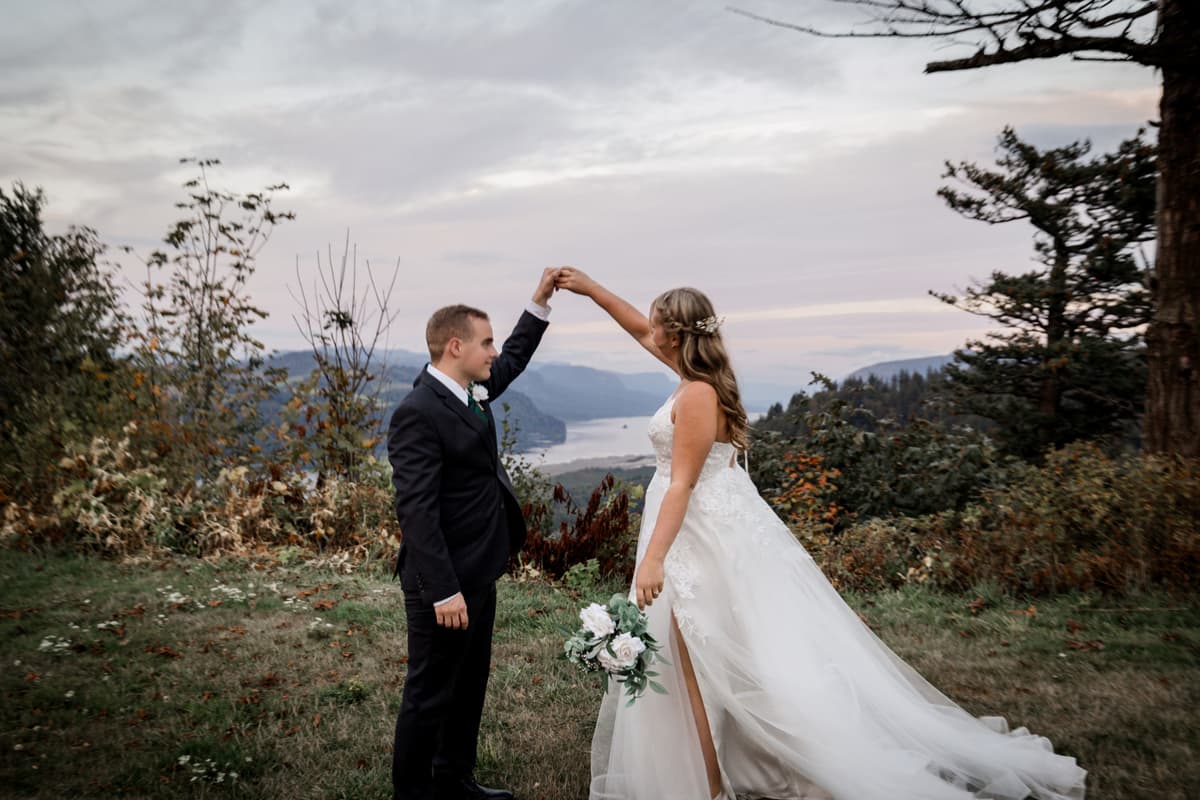
Born and raised in Longview. This is home. Outside the office you'll likely find me at the gym, on a hike or tennis court when the sun's out, or spending time with my wife and our local family. I serve on the board for Habitat for Humanity, worship at our local church on Sundays, and meet monthly with a group of Christian business owners for encouragement and fellowship.
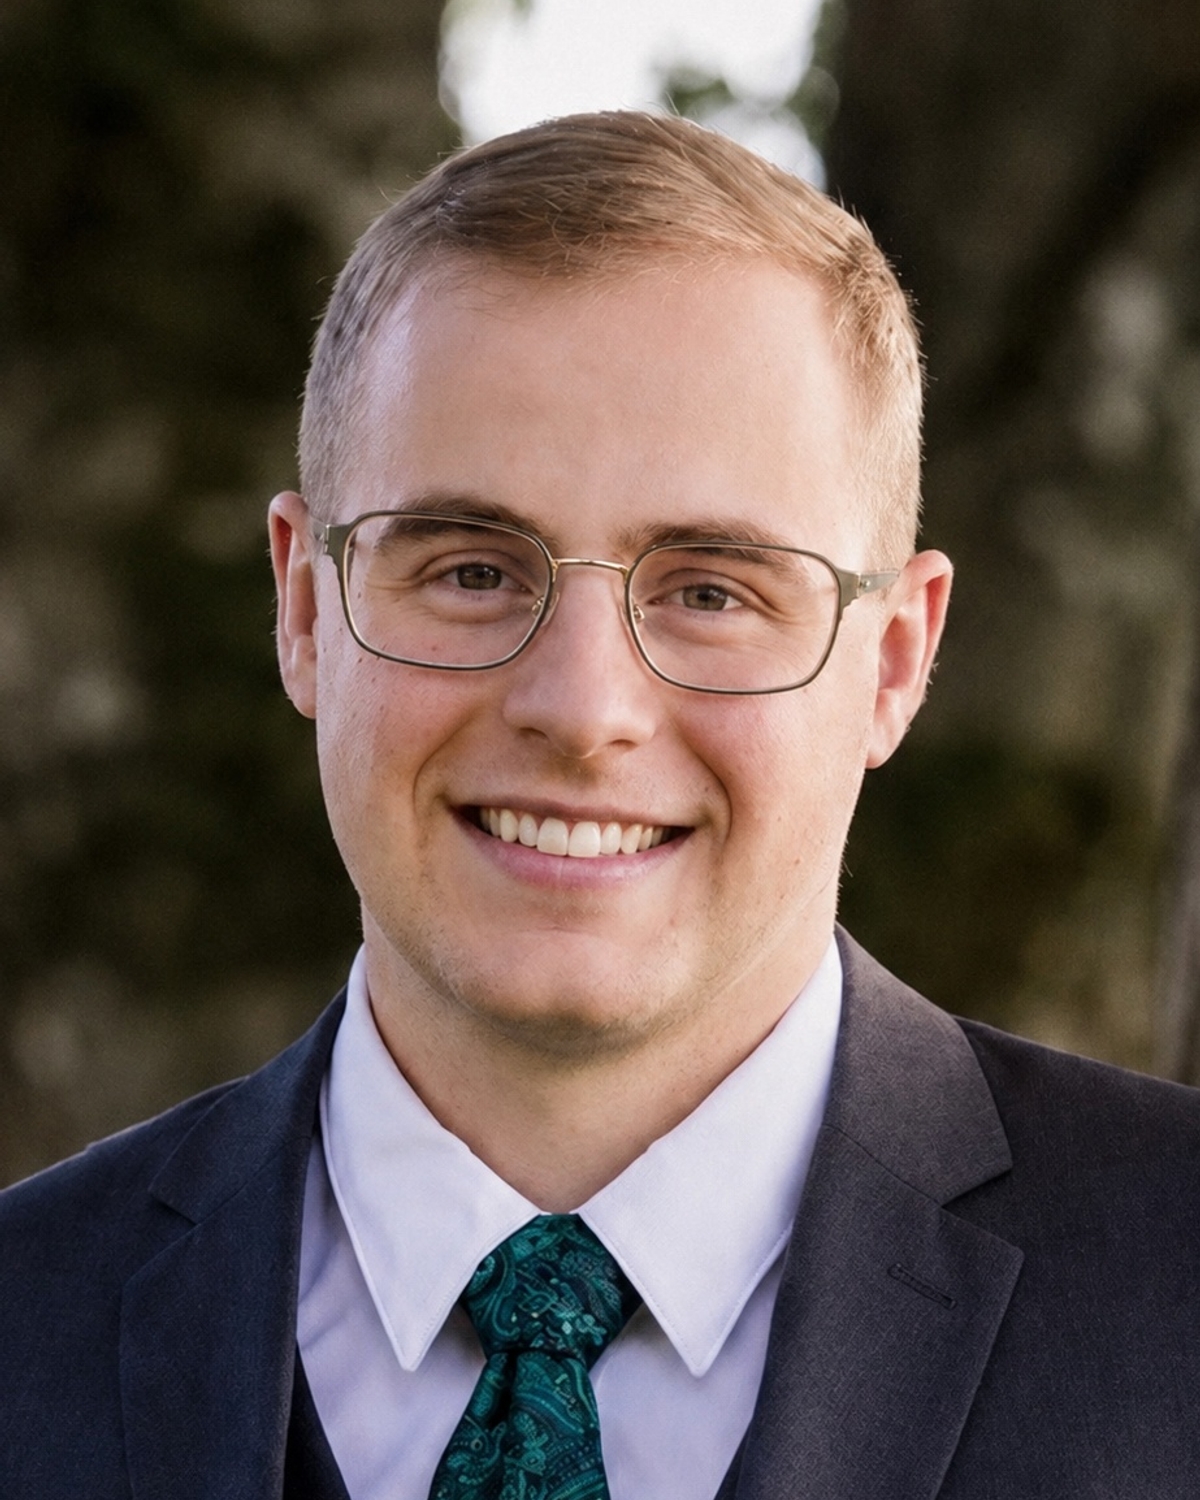
I earned my Bachelor's degree in Financial Planning from Franklin University and built my early career at another firm before finding my home at Thrivent, whose values matches my own. I care about my clients personally, not just their portfolios. My work is about helping people retire with enough confidence that they can spend their time on the people they love instead of worrying about money.
- Bachelors of Finance, Franklin University
- Fraternal Insurance Counselor
- Series 7 - General Securities Representative
- Securities Industry Essentials
- Arizona
- California(Insurance Lic. #4430167)
- Idaho
- Oregon
- Washington
Insights
Can you retire when you want to?
Here's how to figure out a rough idea. Grab a piece of paper and write down your ideal retirement age. Then write down your expected monthly income sources, like social security and a pension if you have one. Next, add in your other retirement savings. Let's say you have $600,000 saved but you're not sure how much income that could provide. For now, use the 4% rule. Take $600,000 x 4% and divide by 12 months, and you get about $2,000 per month.
Add everything together. Maybe it's $3,000 from social security, $1,000 from a pension, and $2,000 from your retirement accounts, which comes out to $6,000 per month. This is where a lot of people stop, but they miss two key pieces: taxes and survivorship.
In this example, that $6,000 is your pre-tax income. To keep the math simple, if you're taxed at 20%, your after-tax income would actually be $4,800.
Second, when you wrote down your pension, did you pick 100% survivorship or single life income? A pension is usually lower if it has to pay out for both of your lifetimes instead of just one. On top of that, a surviving spouse loses the smaller of the two social security checks. So in this same example, if one spouse passes away, the future income could look like $2,000 from social security, $750 from the pension, and $2,000 from retirement accounts, totaling $4,750. That surviving spouse also moves into the single filer tax bracket, which can raise their tax bill even further.
I share this because knowing your actual after-tax income matters more than the number on paper. Run your own numbers. Are you on track? If yes, great. If not, you really only have three options: save more now, spend less later, or work longer.
See thrivent.com/social for important disclosures.
"How much can I safely take out of my retirement account every year?"
That's one of the most common questions I hear from people approaching retirement.
For many people, the biggest concern isn't growing their money anymore. It's making sure they don't run out of it.
The reality is that there isn't one right answer. There are several approaches people use to create retirement income, and each comes with tradeoffs.
One approach is often called the 4% rule. As a rough guideline, someone with a $500,000 portfolio might start by withdrawing about $20,000 per year and adjust that amount over time for inflation. The goal is to create a consistent paycheck while leaving the rest of the portfolio invested.
Another approach is a flexible spending strategy. Instead of withdrawing the same dollar amount every year, withdrawals adjust based on the value of the portfolio. When markets are up, income can increase. When markets are down, spending may need to be reduced. This approach can work well for people who have flexibility in their budget.
A third option is to use a portion of your savings to create a guaranteed income stream through an annuity. Some people like the idea of receiving a predictable monthly payment that isn't directly tied to market performance. Others prefer to keep more of their assets invested and maintain greater flexibility.
None of these approaches are inherently right or wrong. The best fit often depends on factors like your spending needs, risk tolerance, other sources of income, and how much certainty you want in retirement.
The important thing is understanding that retirement income isn't limited to a single strategy. Most retirees have more than one option available to them, and the right plan is often a combination of approaches that work together.
See thrivent.com/social for important disclosures.
What if you're just working the wrong job?
I'd encourage you to spend some time thinking about what you're retiring to, not just what you're retiring from.
Some of the people I work with are burned out. They're in their 50s, have worked the same job for 30 years, and they're tired. They've done their share of overtime, shift work, and mandatory training days. Their mindset becomes, "Once my portfolio reaches X, I'm done. I'm not working a day longer."
If that sounds like you, here's something to consider: maybe the goal isn't to stop working altogether. Maybe the goal is to stop doing work you no longer enjoy.
I've been surprised by how many people retire from a long career only to find a part-time job six months later. What I've realized is that some of them could have "retired" years sooner if they had simply transitioned to part-time work in a field they actually enjoyed.
Here's a simple way to think about it:
It's not a perfect comparison, but using the 4% rule as a rough guideline, $10,000 of annual part-time income can have a similar impact on your retirement income plan as roughly $250,000 in savings.
What if you planned for the first few years of retirement assuming you'd work a little? Maybe you work part of the year and take the rest off. Maybe you find a job that's lower stress, more flexible, and something you genuinely enjoy doing.
This idea won't be right for everyone. But before you focus only on the number you need to retire, it may be worth asking what you want retirement to look like in the first place.
Because sometimes it's not that you're ready to stop working. You may just be ready to stop doing the work you're doing now.
See thrivent.com/social for important disclosures.
Office location
Longview Location
1402 Broadway St STE 202
Longview, WA 98632
Phone360-747-2669HoursLongview, WA 98632
M – F: 10 a.m. – 5 p.m.
Licensing is available through your State Insurance Department’s website, which can be located through the National Association of Insurance Commissioners website.
Thrivent and its financial advisors and professionals do not provide legal, accounting or tax advice. Consult your attorney or tax professional.
Thrivent financial advisors and professionals have general knowledge of the Social Security tenets. For complete details on your situation, contact the Social Security Administration.
Thrivent provides advice and guidance through its Financial Planning Framework that generally includes a review and analysis of a client’s financial situation. A client may choose to further their planning engagement with Thrivent through its Dedicated Planning Services (an investment advisory service) that results in written recommendations for a fee.
Designations
For additional information on professional designations and the requirements to earn them, visit https://www.thrivent.com/designations
Thrivent and its financial advisors and professionals do not provide legal, accounting or tax advice. Consult your attorney or tax professional.
Thrivent financial advisors and professionals have general knowledge of the Social Security tenets. For complete details on your situation, contact the Social Security Administration.
Thrivent provides advice and guidance through its Financial Planning Framework that generally includes a review and analysis of a client’s financial situation. A client may choose to further their planning engagement with Thrivent through its Dedicated Planning Services (an investment advisory service) that results in written recommendations for a fee.
Designations
For additional information on professional designations and the requirements to earn them, visit https://www.thrivent.com/designations